JetBlue Airways (NASDAQ: JBLU) reported a wider third-quarter loss on 26 October 2026, even as revenue climbed 21% year-on-year.
The carrier posted a net loss of $257m, up from a $143m loss in the same quarter last year, according to its 10-Q filing with the SEC. Diluted loss per share came to $0.68, against $0.39 a year earlier.
JetBlue Q3 loss widens despite revenue growth
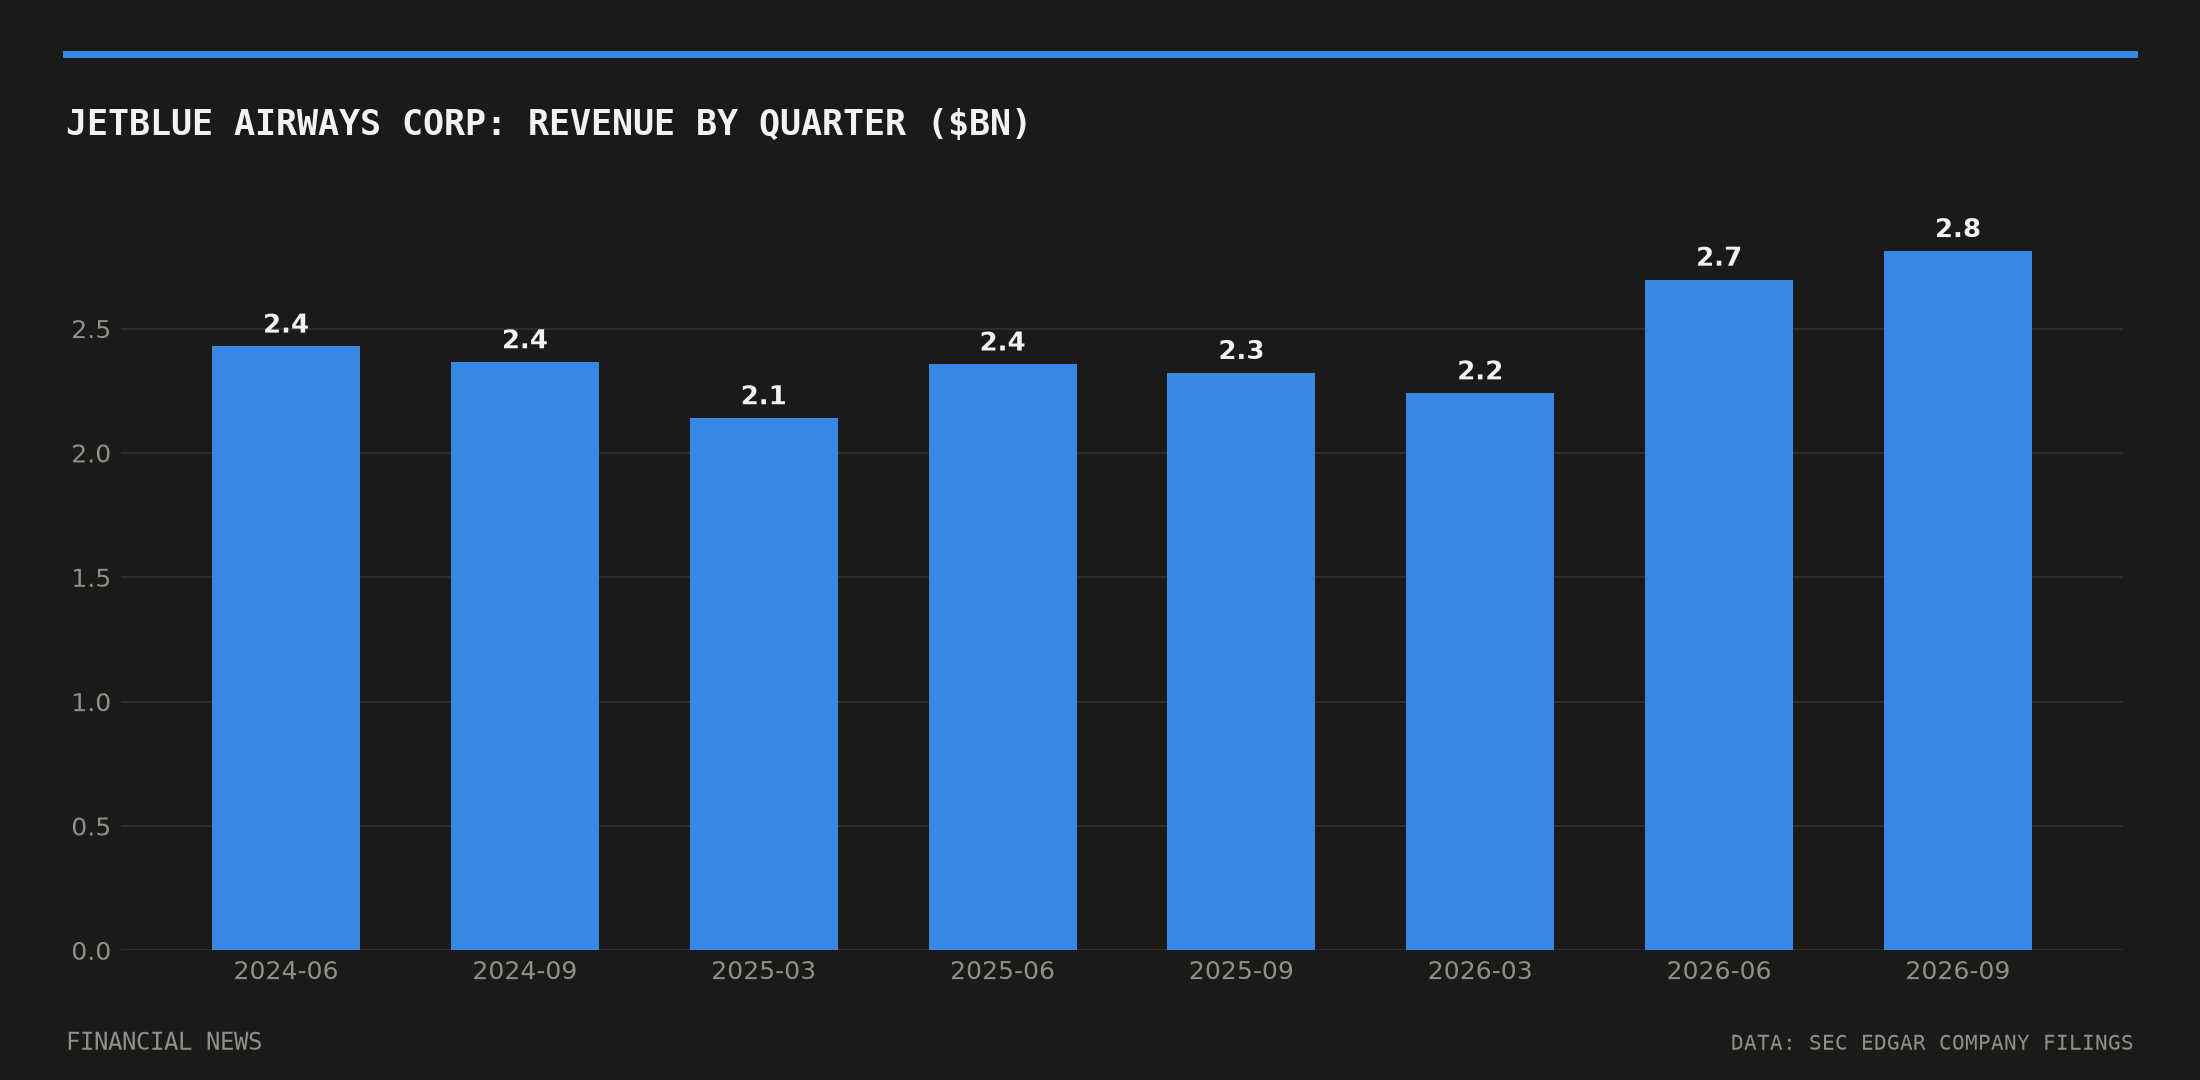
Revenue for the quarter reached $2.812bn, up from $2.322bn in the third quarter of 2025, the filing shows. That growth was not enough to clear Wall Street’s bar: the figure fell short of consensus forecasts, and the quarter’s loss missed the $0.55-a-share estimate from eight analysts, as reported by the Associated Press.
On an adjusted basis, the metric analysts typically track, JetBlue posted a loss of $0.60 a share, against a $0.40 loss a year earlier – a 9.09% miss versus consensus, according to Zacks Investment Research. Operating losses also deepened, to $144m from $100m, widening the operating margin to -5.1% from -4.3%.
CEO points to fuel-cost recapture
Chief executive Joanna Geraghty struck an upbeat tone despite the red ink. ‘Resilient demand and strong yields drove revenue well ahead of our initial expectations, allowing us to recapture more of the increase in fuel costs than we initially expected,’ she said in JetBlue’s earnings statement.
The airline’s own release cited 18.4% growth in revenue per available seat mile and recapture of roughly 87% of higher fuel costs during the quarter, according to JetBlue’s investor relations materials. CNBC reported that Geraghty said the momentum had carried into the fourth quarter.
Shares jump despite the miss
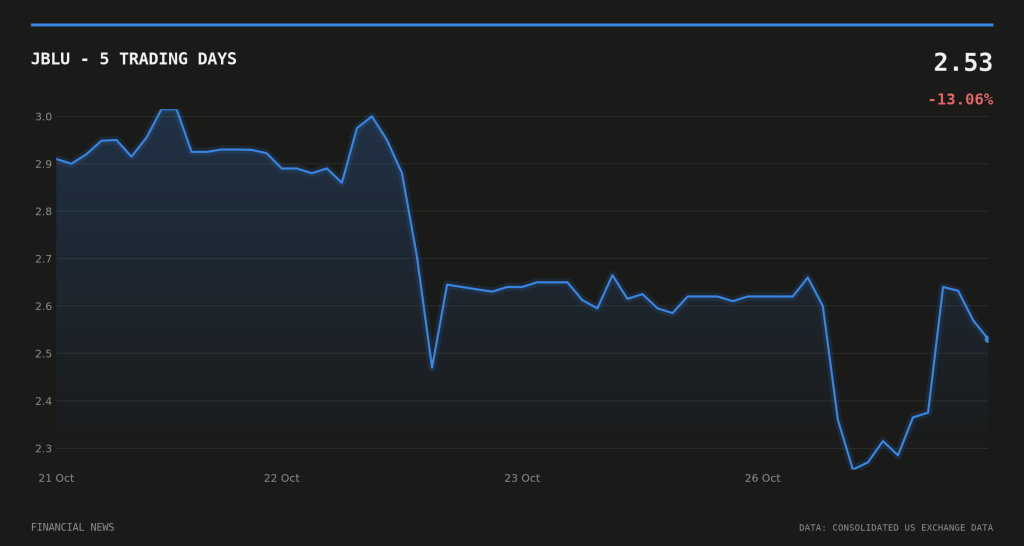
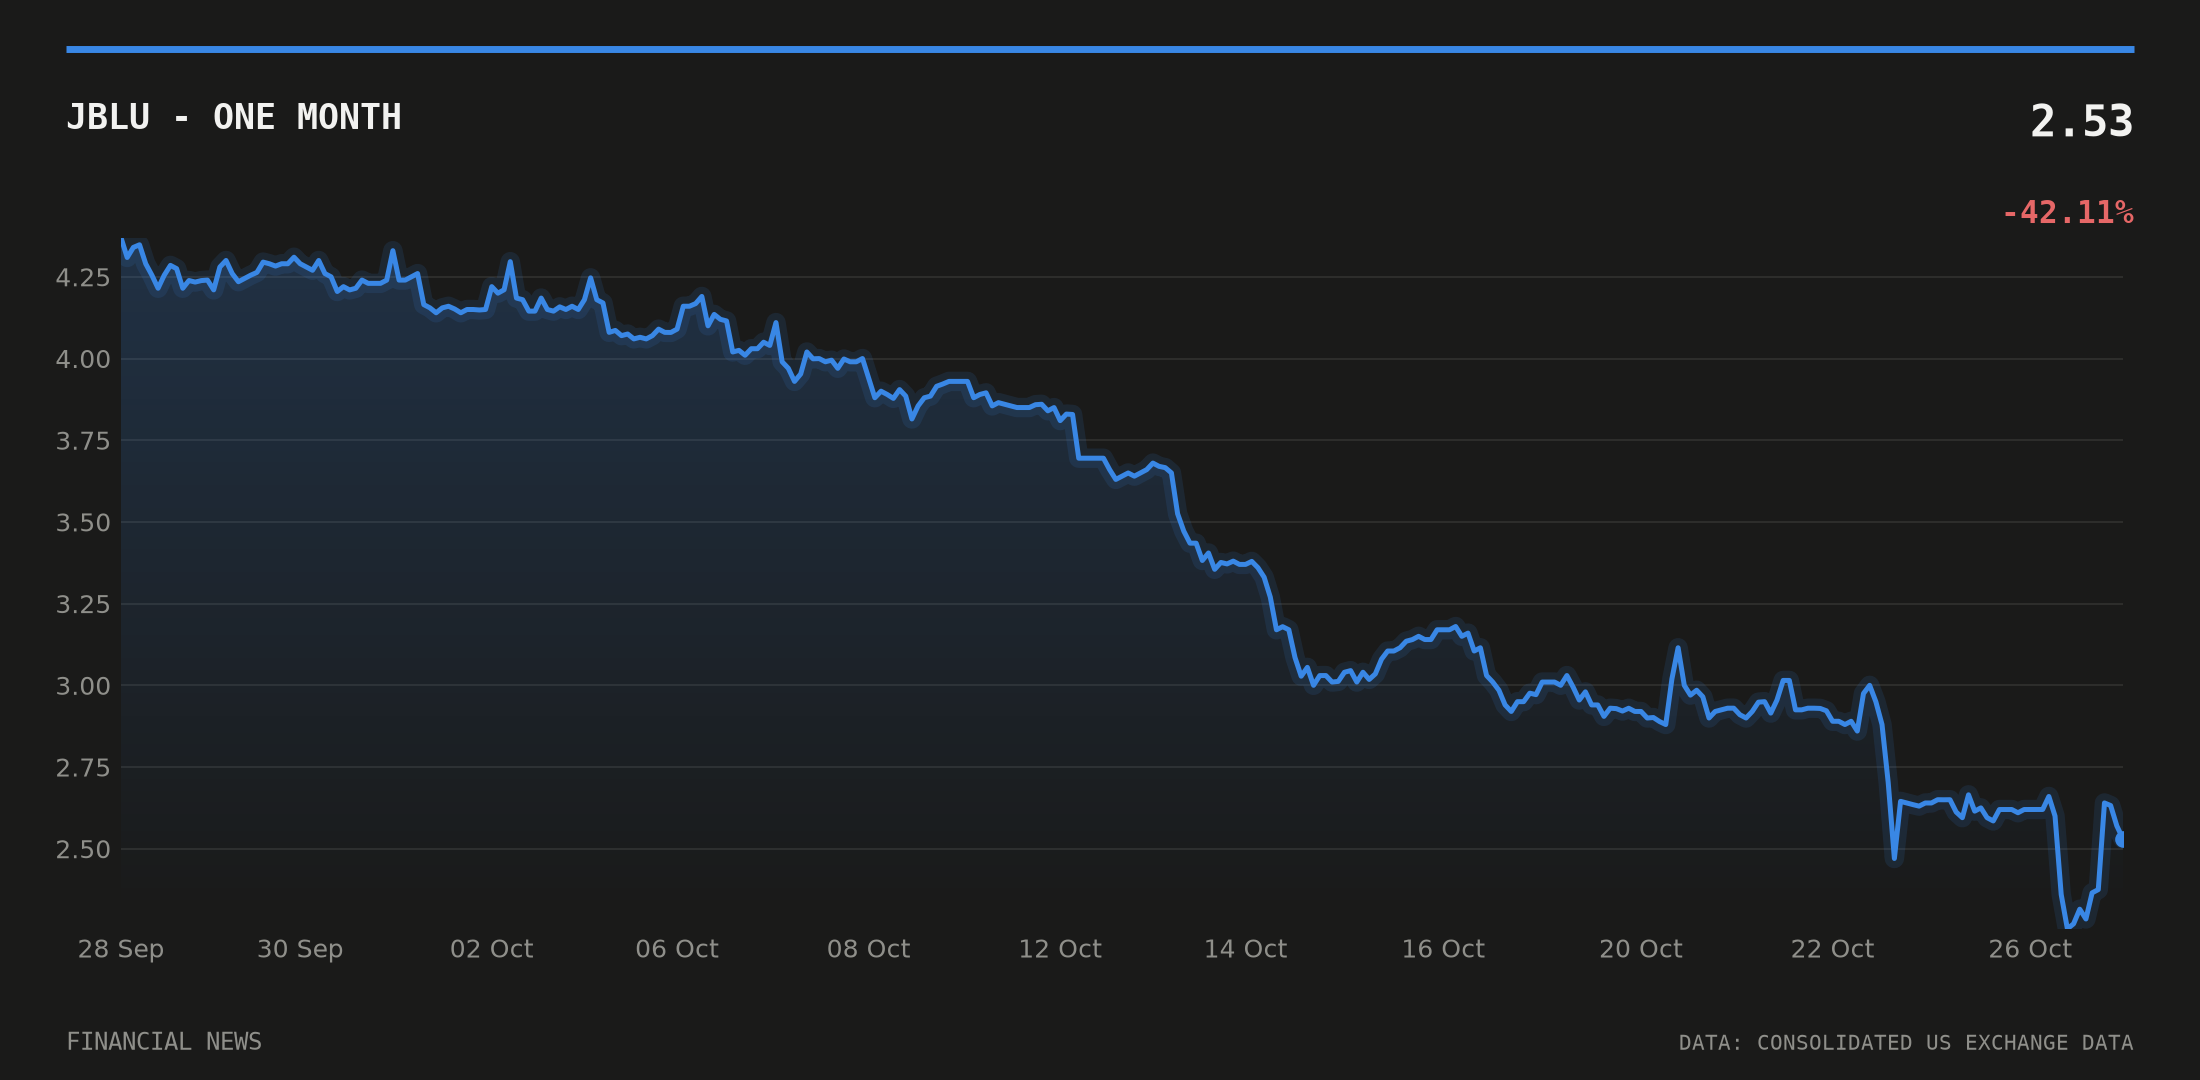
Investors looked past the headline loss. JBLU shares closed up 9.29% at $2.53 as of 11pm UTC on the day of the print, consolidated exchange data show, even after a 38.14% slide over the prior 20 trading days. Investing.com reported the stock was up more than 13% in after-hours trading immediately following the release, before settling into the smaller gain captured in the next session’s close.
FINRA’s daily short-sale volume ratio for JBLU ran between roughly 0.55 and 0.72 across the ten sessions through 26 October, FINRA data show – not the pattern of a stock under unusual short-selling pressure heading into the print.
A longer run of red ink
The third-quarter loss extends a pattern stretching back more than two years. JetBlue’s SEC filings show net losses in six of the last seven reported quarters: a $60m loss in the third quarter of 2024, a $208m loss in the first quarter of 2025, a $74m loss in the second quarter of 2025, a $143m loss in the third quarter of 2025, a $319m loss in the first quarter of 2026, and a $247m loss in the second quarter of 2026, before the $257m loss just reported. The sole profitable period in that run was the second quarter of 2024, when the carrier posted net income of $25m.
Revenue has also been uneven across those quarters. JetBlue took in $2.428bn in the second quarter of 2024, $2.365bn in the third quarter of that year, then dipped to $2.140bn in the first quarter of 2025 before recovering to $2.356bn and $2.322bn in the following two quarters. This year’s figures have trended higher: $2.240bn in the first quarter, $2.697bn in the second, and now $2.812bn in the third – the strongest quarterly revenue total in the run, even as losses persisted alongside it.
The results land against a backdrop of rising US borrowing costs. The 10-year Treasury yield stood at 5.0% on 23 October 2026, up from 4.96% a session earlier, while the 2-year yield rose to 4.69% from 4.65%, according to Federal Reserve data. Higher rates raise financing costs for capital-intensive carriers like JetBlue, which has leaned on aircraft financing and leasing to fund its fleet. US unemployment also edged up to 4.2% in September from 4.1% the prior month, Fed data show, a signal watched closely by airlines gauging consumer travel demand heading into next year.
A Form 4 filed by Eileen P. McCarthy on 26 October, the same day as the earnings release, was disclosed alongside the results, according to SEC EDGAR records. Investors will next watch JetBlue’s fourth-quarter guidance and whether the fuel-cost recapture Geraghty described can be sustained into 2027.
This article is for information only and is not investment advice or a recommendation to buy or sell any asset. Markets move quickly; figures are correct as sourced at the time of writing. Always do your own research before making financial decisions.