Procter & Gamble (NYSE: PG) reported a fiscal first-quarter earnings beat on 22 October 2026, with net sales rising 4% year-on-year.
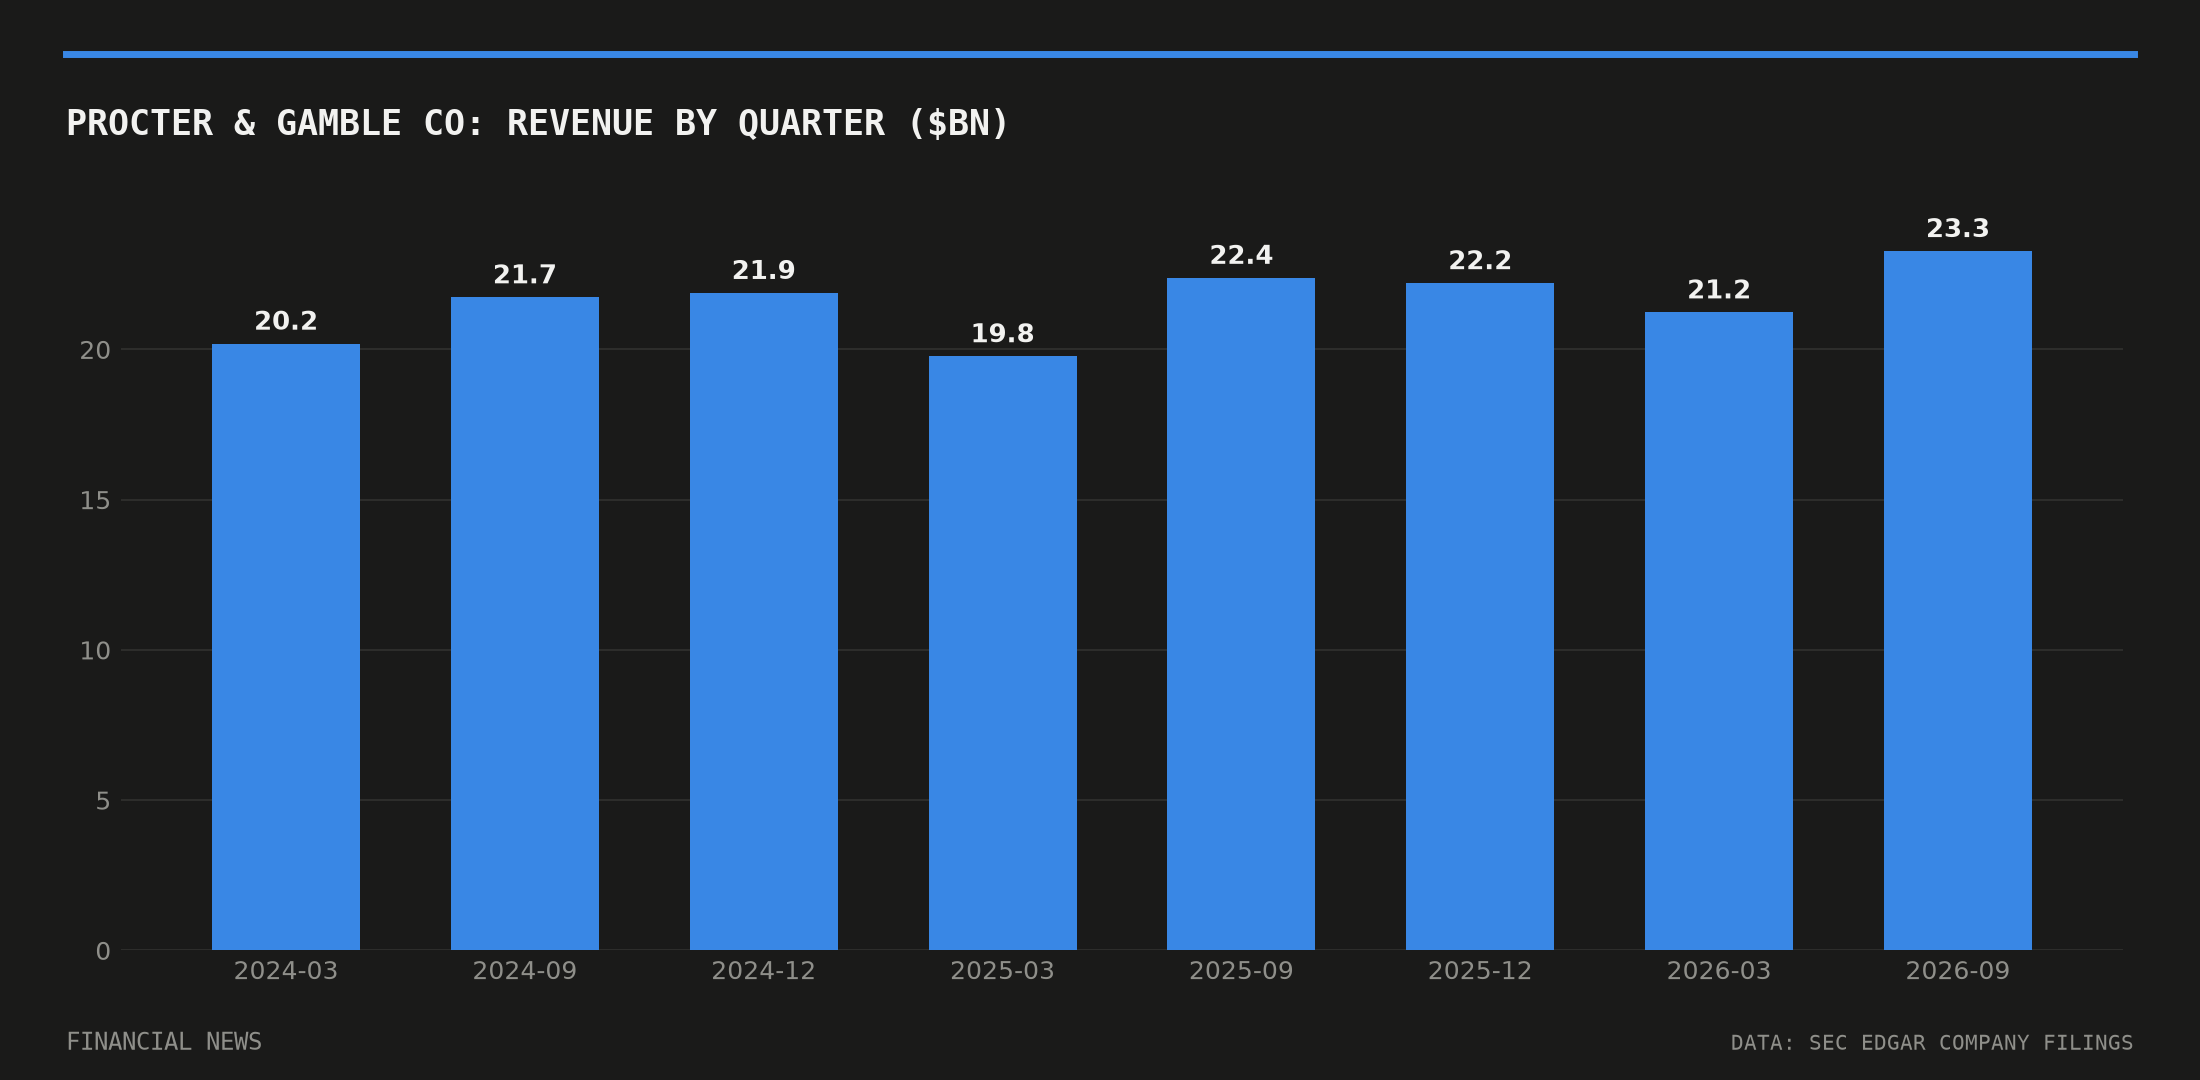
Net sales reached $23.28bn in the quarter ended 30 September 2026, up from $22.39bn a year earlier, according to the company’s 10-Q filed with the SEC. That topped analyst estimates of $22.82bn.
P&G earnings beat driven by laundry and home care
Core earnings per share came in at $2.00, beating the $1.89 consensus estimate, as first reported by Investing.com. Organic sales growth hit 4.0%, split between volume gains of 2.4 percentage points, pricing of 0.4 points and favourable mix of 1.1 points, P&G’s earnings release slides show.
Fabric & Home Care, which includes laundry detergents such as Tide and Ariel, grew organic sales 5%, faster than the group average, according to a transcript of the earnings call. Beauty and Grooming each also grew 5%, while Health Care rose 3% and Baby, Feminine and Family Care rose 3%, a separate recap carried by Yahoo Finance showed.
The growth pattern marks a shift from recent quarters, when P&G leaned more heavily on price increases to offset input-cost pressure. This time, volume and product mix did most of the work, with pricing contributing less than half a percentage point.
Profit lagged the top line
Beneath the revenue beat, profit growth was muted. GAAP diluted earnings per share came to $1.97, up from $1.95 a year earlier, a 1% rise, the filing shows. Net income attributable to the company was $4.73bn, against $4.75bn in the same quarter last year, a slight decline.
That gap between a 4% sales gain and roughly flat net income suggests the quarter’s strength was a genuine demand story in laundry and home care rather than one engineered through margin expansion.
The quarter extends a run of sales recovery after a softer patch earlier in the year. P&G’s net sales dipped to $19.78bn in the quarter ended March 2025 and $21.24bn in the quarter ended March 2026, before rebounding to $23.28bn in the latest print, filings show. Diluted EPS over that stretch moved from $1.54 to $1.63 to $1.97, tracking the same uneven pattern before this quarter’s acceleration.
P&G raised its full-year outlook for all-in sales growth to a range of 2% to 4%, reflecting its acquisition of supplement maker Thorne, while leaving organic sales growth guidance unchanged at 1% to 3%, according to Tradingpedia. That split, a higher headline target alongside steady underlying guidance, signals management is not yet banking on the quarter’s demand strength continuing at the same pace.
Shares pare early gains
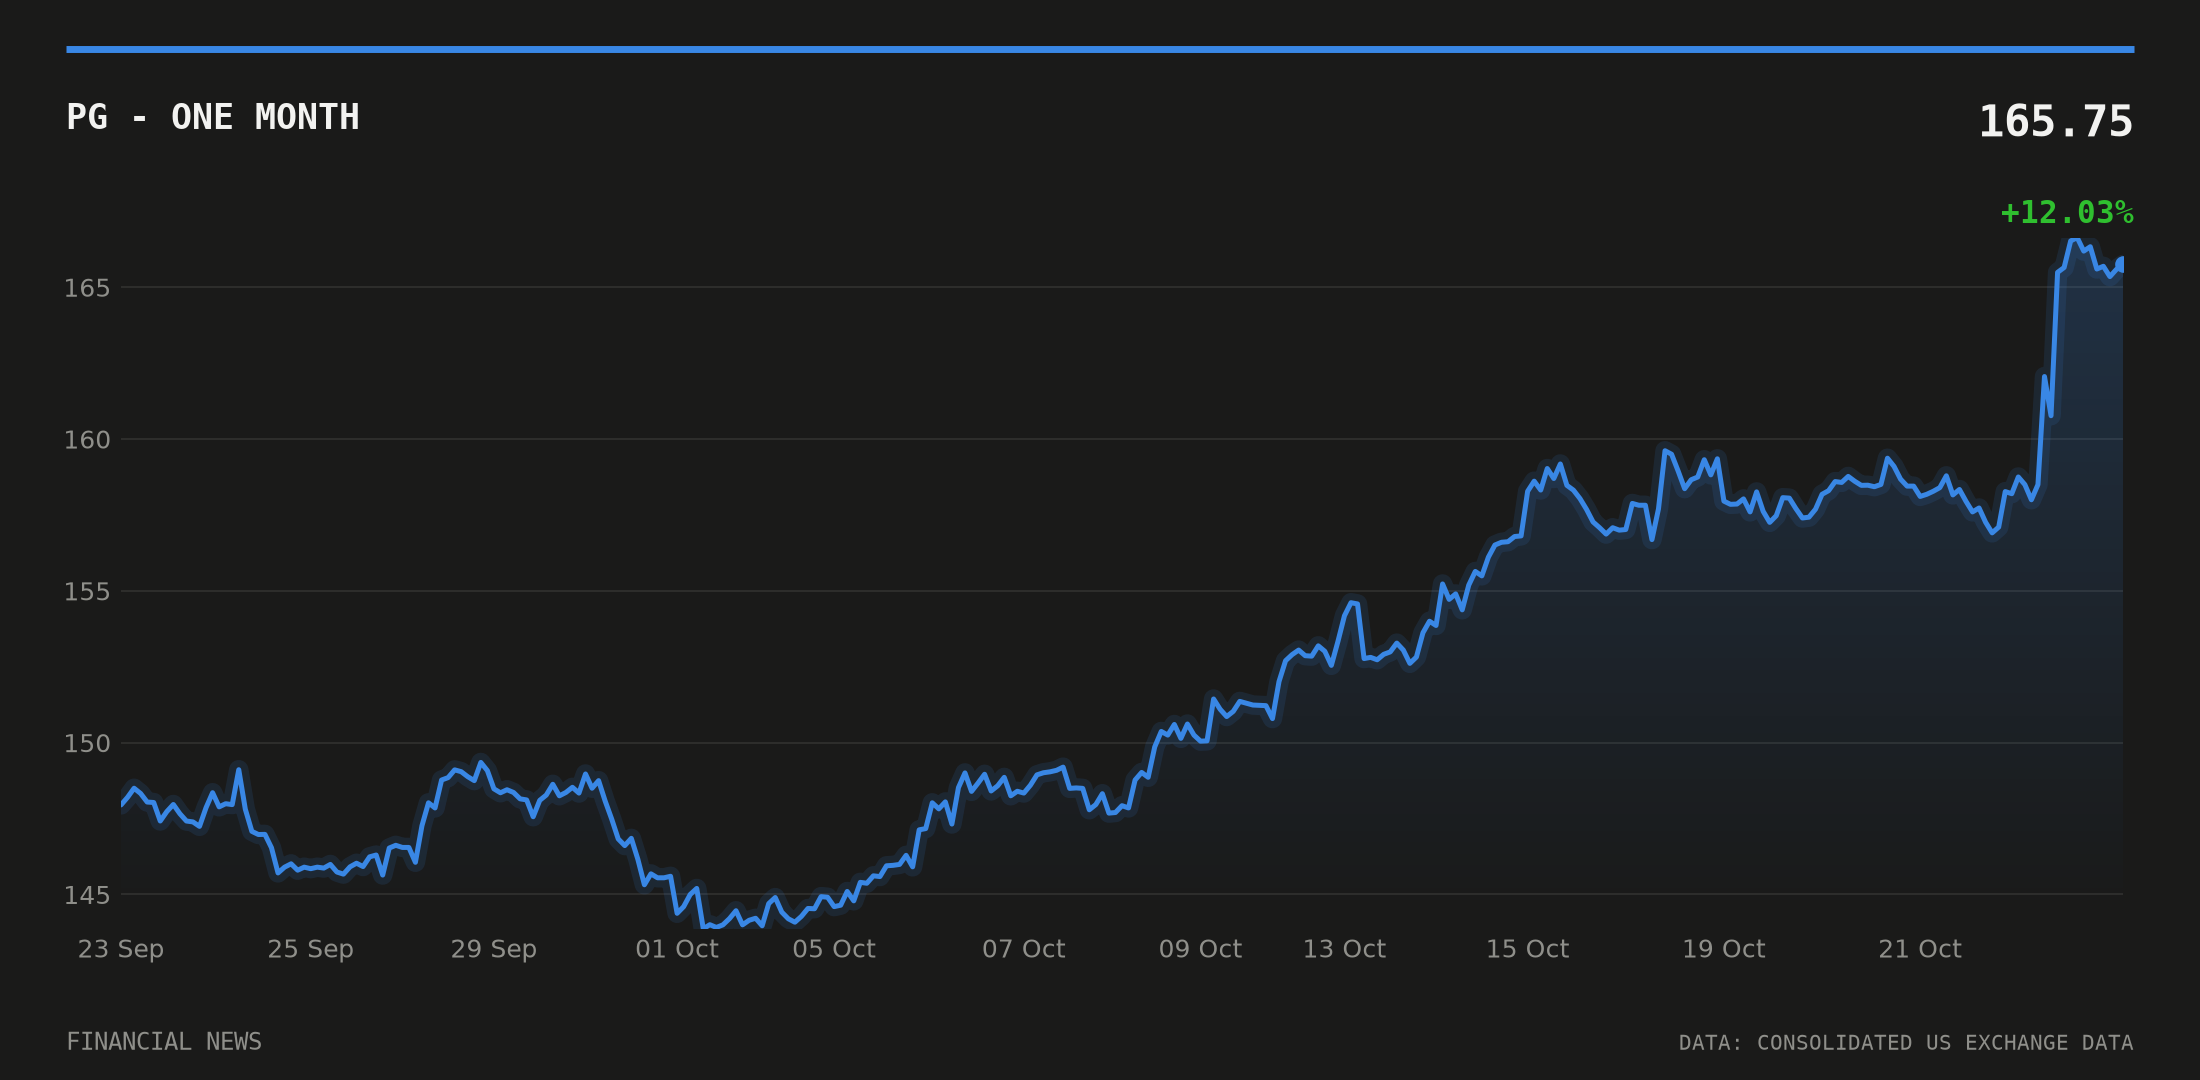
PG shares rose more than 5% in morning trading on the results, CNBC reported, but closed the session down 0.53% at $165.75. The stock had already climbed 15.13% over the prior 20 trading sessions, putting it near its 20-day high of $166.64 before the print, consolidated exchange data show.
Volume on the day ran at twice the 20-day average, pointing to heavy turnover even as the early rally faded. FINRA short-sale data showed no unusual build-up in bearish positioning ahead of the report: the daily short-sale ratio ranged between roughly 0.27 and 0.51 across the two weeks into earnings, broadly in line with recent norms.
The figures leave P&G’s finance team facing a familiar question for the rest of the fiscal year: whether the volume-led demand seen in laundry and home care in this quarter can be sustained without reverting to the pricing-led growth of previous years. P&G’s second-quarter results, covering the holiday-shopping period, are due in January.
This article is for information only and is not investment advice or a recommendation to buy or sell any asset. Markets move quickly; figures are correct as sourced at the time of writing. Always do your own research before making financial decisions.