Nucor (NYSE: NUE) reported third-quarter 2026 net earnings attributable to stockholders of $1.32bn, or $5.80 a diluted share, on 26 October 2026.
Net sales for the quarter came to $11.25bn, the steelmaker said in its results statement, with net earnings before noncontrolling interests of $1.47bn and EBITDA of $2.28bn.
The figures, filed in an exhibit to Nucor’s 8-K with the SEC, beat Wall Street’s going estimates. Bloomberg reported the $5.80 print topped a $5.77 average analyst estimate, on sales of $11.2bn against expectations nearer $10.8bn.
Year-on-year, net earnings more than doubled from $607m in the third quarter of 2025, when diluted EPS was $2.63, according to Nucor’s SEC filings. Net sales rose roughly 32% from $8.52bn a year earlier.
Clearing a bar it lowered itself
The third-quarter Nucor earnings beat follows a September guidance cut. On 17 September 2026 Nucor had pointed to EPS of $5.55 to $5.65, well below the then-consensus of $6.20, and shares fell 3.7% in after-hours trading at the time, Investing.com reported.
The eventual $5.80 figure cleared that lowered guidance range comfortably, even though it remained short of the original Street consensus set earlier in the year. Sequentially, earnings rose from $1.16bn, or $5.04 a share, in the second quarter, though that figure had included a one-off $61m non-cash gain tied to Nucor’s stake in fusion-energy company Helion, equivalent to $0.20 a share.
Chief executive Leon Topalian said 2026 had been “the safest summer in Nucor history,” according to the company’s results statement, and noted the group had generated around $2.7bn of free cash flow and returned nearly $1.4bn to shareholders over the first nine months of the year.
Shares fall despite the beat
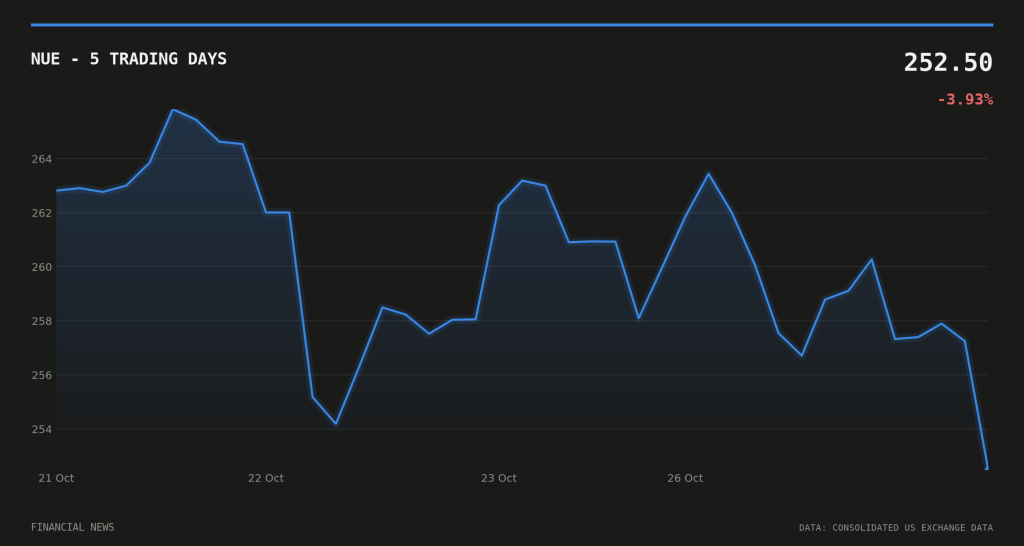
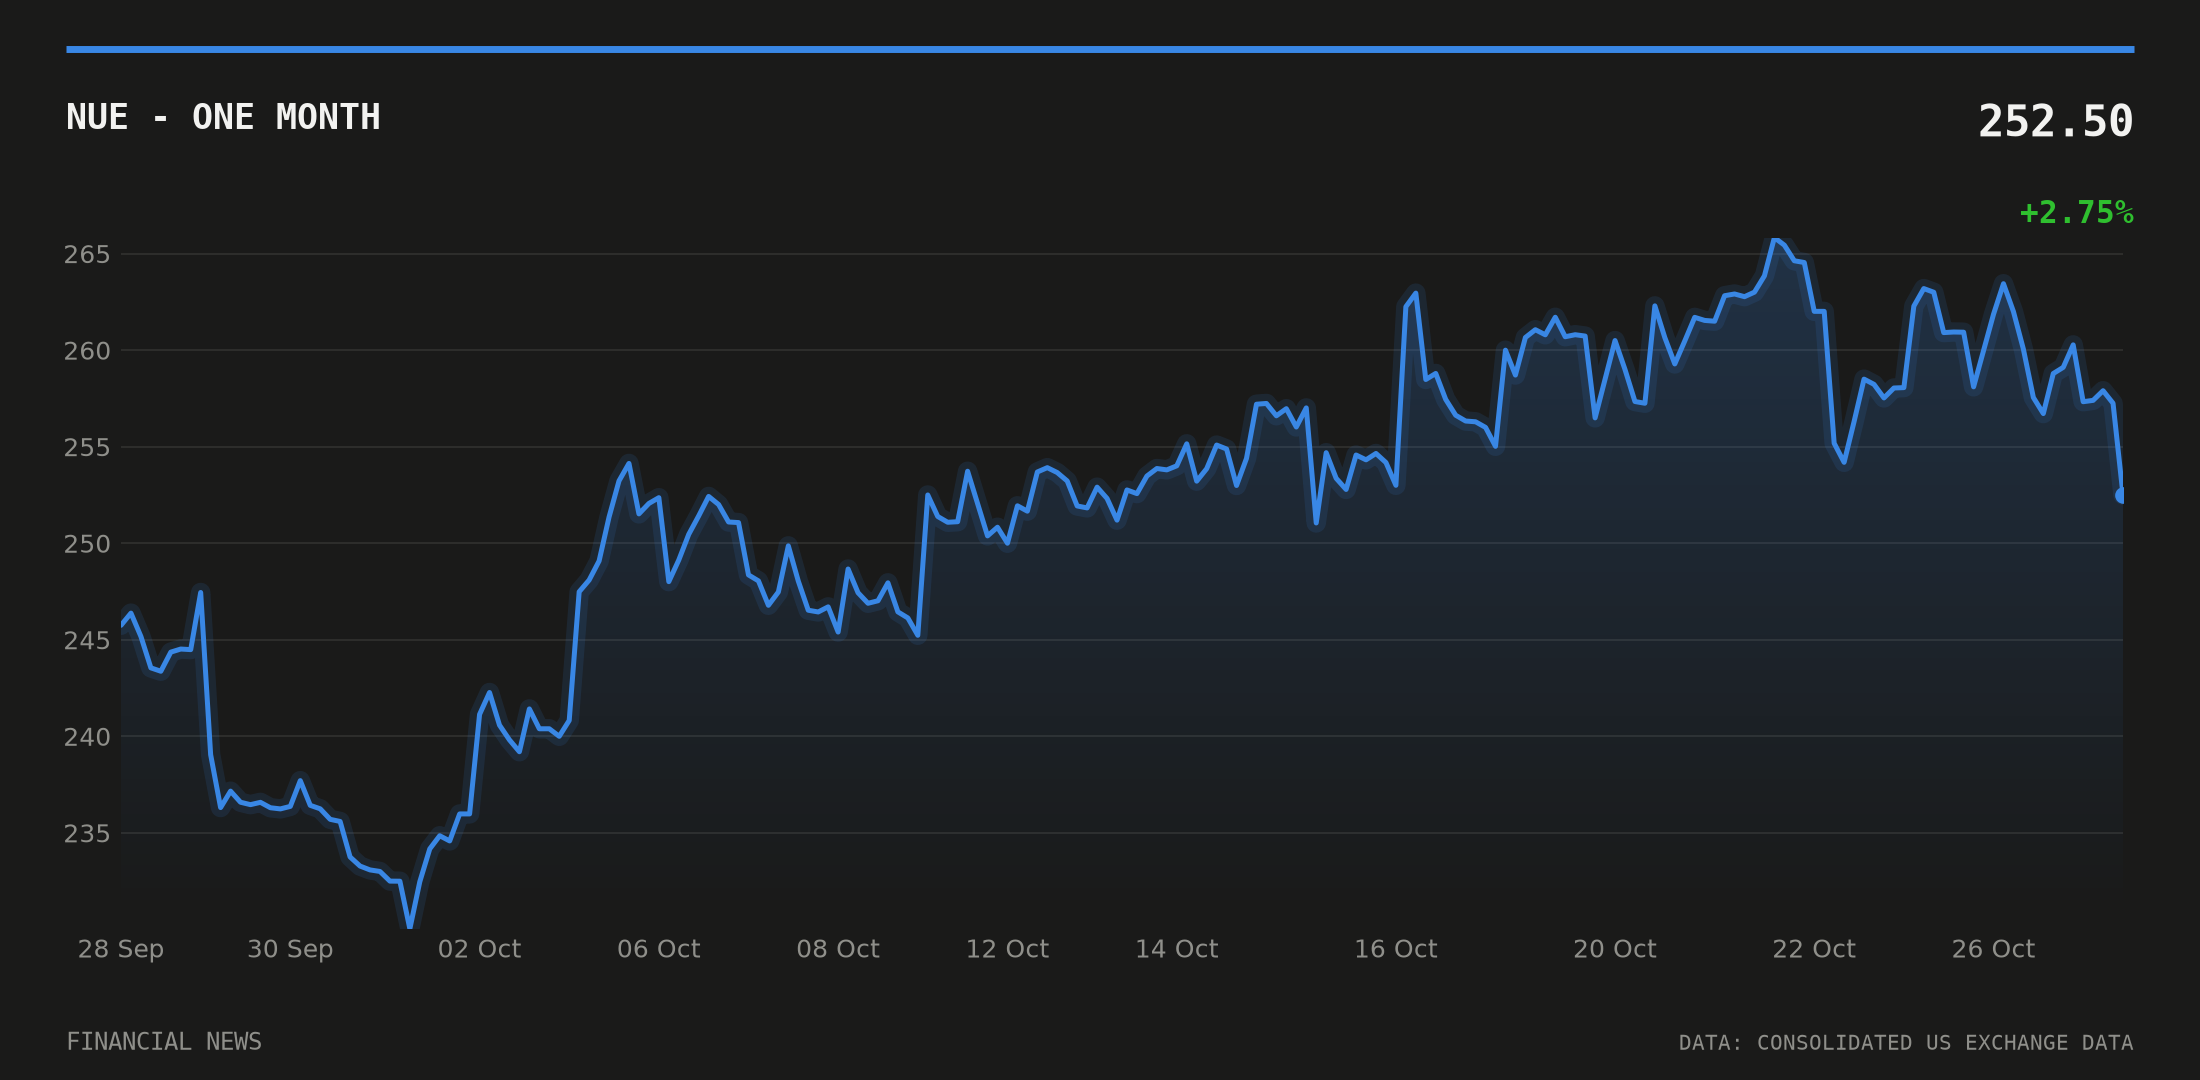
Nucor stock closed at $252.50 on 26 October, down 2.43% on the day, having traded between $245.23 and $265.83 over the prior 20 sessions. Volume ran 33% above the 20-day average.
FINRA short-sale data show the stock’s daily short ratio climbing steadily into the print, from 0.487 on 15 October to 0.736 on earnings day itself, pointing to short-side positioning building ahead of the release.
Revenue math gets garbled downstream
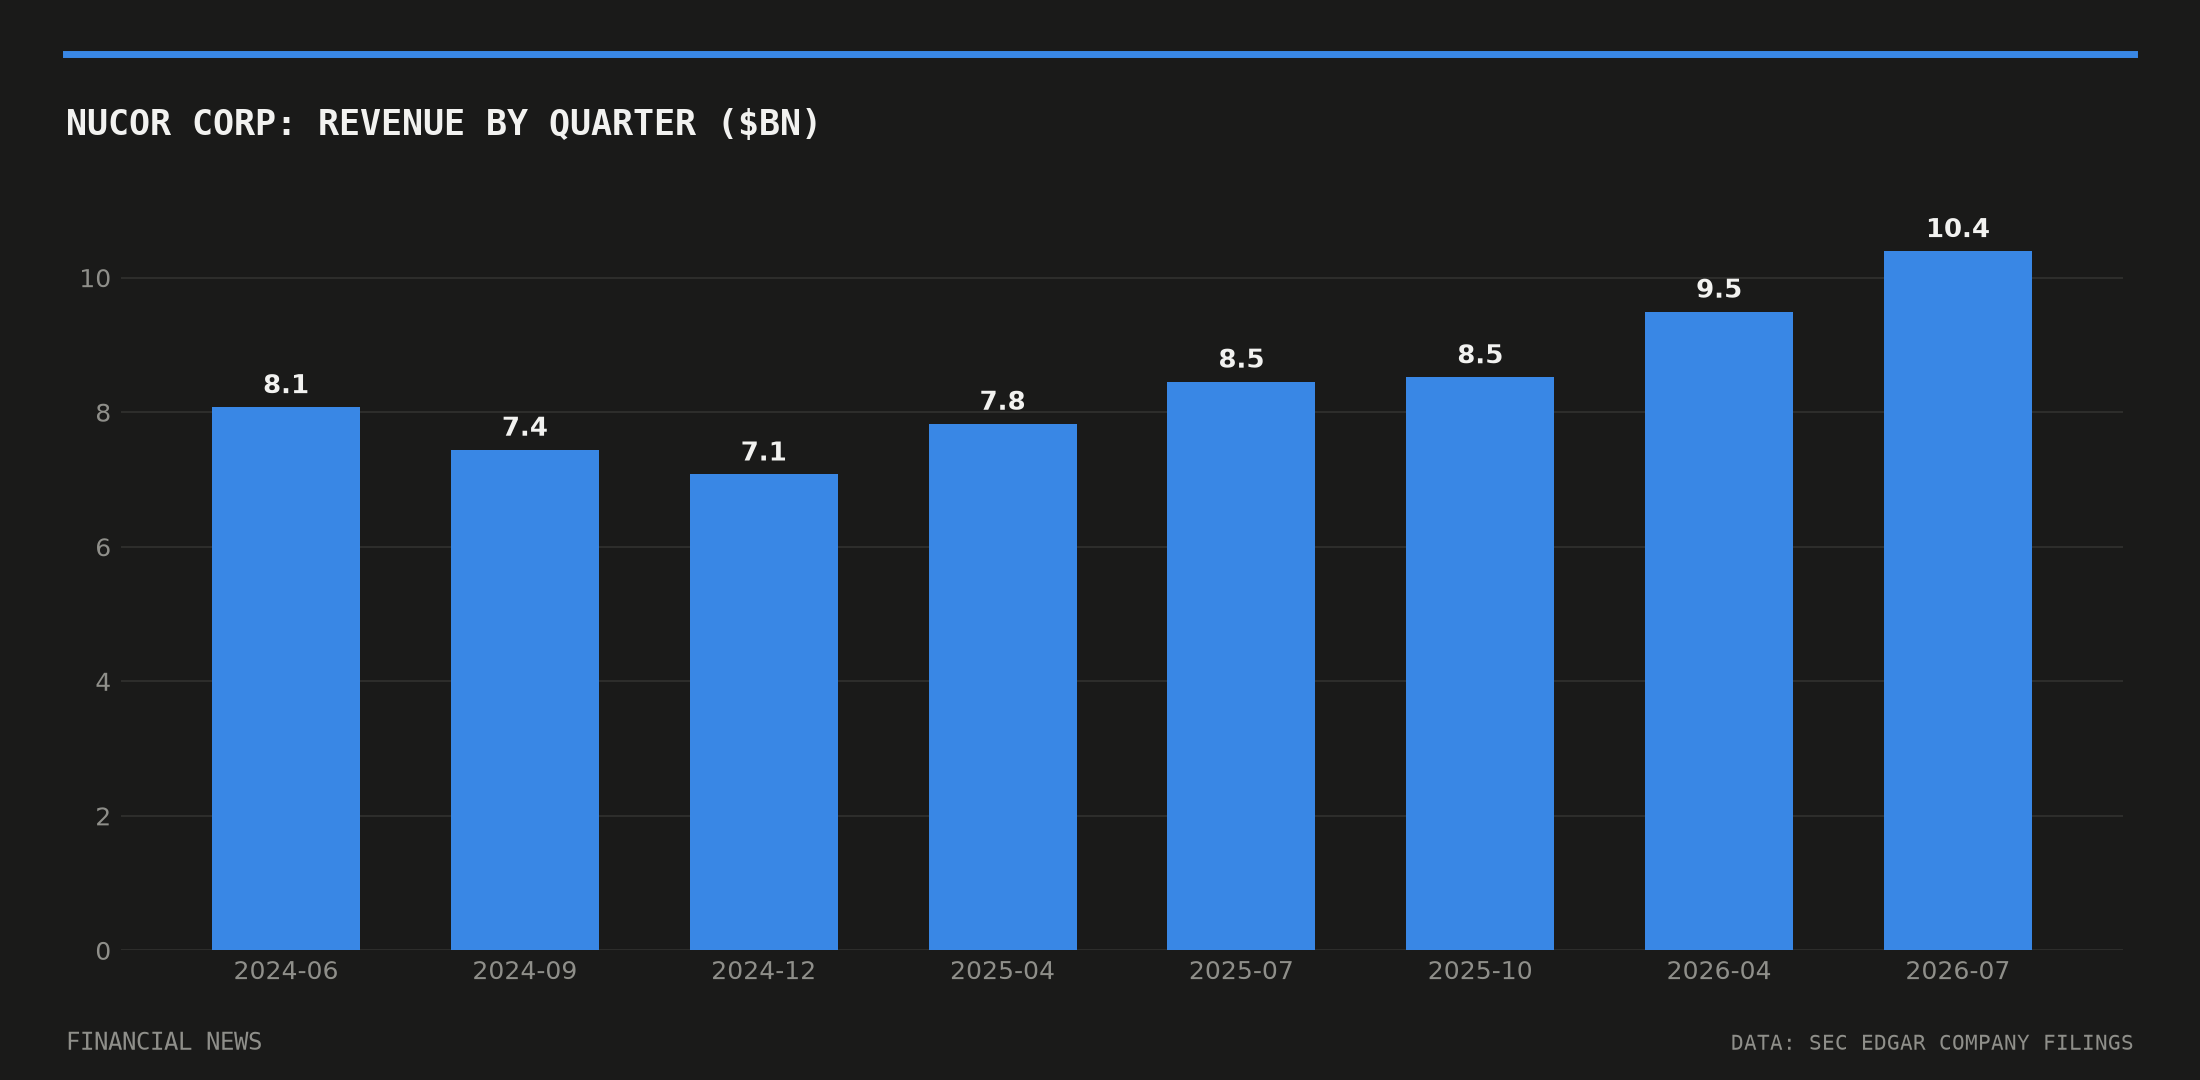
Not every account of the quarter matched Nucor’s own numbers. Investing.com’s write-up of the results cited prior-year revenue of $7.78bn and growth of 44%, a figure that does not square with the $8.52bn Nucor itself reported for the third quarter of 2025 in its SEC filings. On that base, growth works out closer to 32%, a figure independently calculated by GuruFocus.
The discrepancy sits in secondary reporting rather than in Nucor’s own disclosures, which have been consistent across its quarterly SEC filings dating back through 2024.
A higher-rate backdrop for capacity spending
The results land against a steadily firming rate environment. The 10-year Treasury yield stood at 5.00% on 23 October 2026, up from 4.96% the prior reading, according to data from the Federal Reserve Bank of St. Louis.
That matters for a capital-intensive steelmaker: Nucor continues to finance capacity additions, including a new sheet mill in West Virginia, in a market where borrowing costs have crept higher rather than lower through the year.
Investors will next watch whether Nucor’s fourth-quarter guidance, typically issued alongside the next results release, signals further margin improvement or a pause after a quarter in which the company outran its own cautious September outlook.
This article is for information only and is not investment advice or a recommendation to buy or sell any asset. Markets move quickly; figures are correct as sourced at the time of writing. Always do your own research before making financial decisions.