SLB (NYSE: SLB) reported third-quarter 2026 revenue of $9,449m on 23 October 2026, a record for the oilfield services group.
That marks a 5% rise from the second quarter and a 6% increase on the same period last year, according to the company’s filing with the US Securities and Exchange Commission. GAAP net income attributable to SLB came in lower, at $735m, down 6% sequentially and 1% year-on-year.
Record revenue, softer GAAP profit
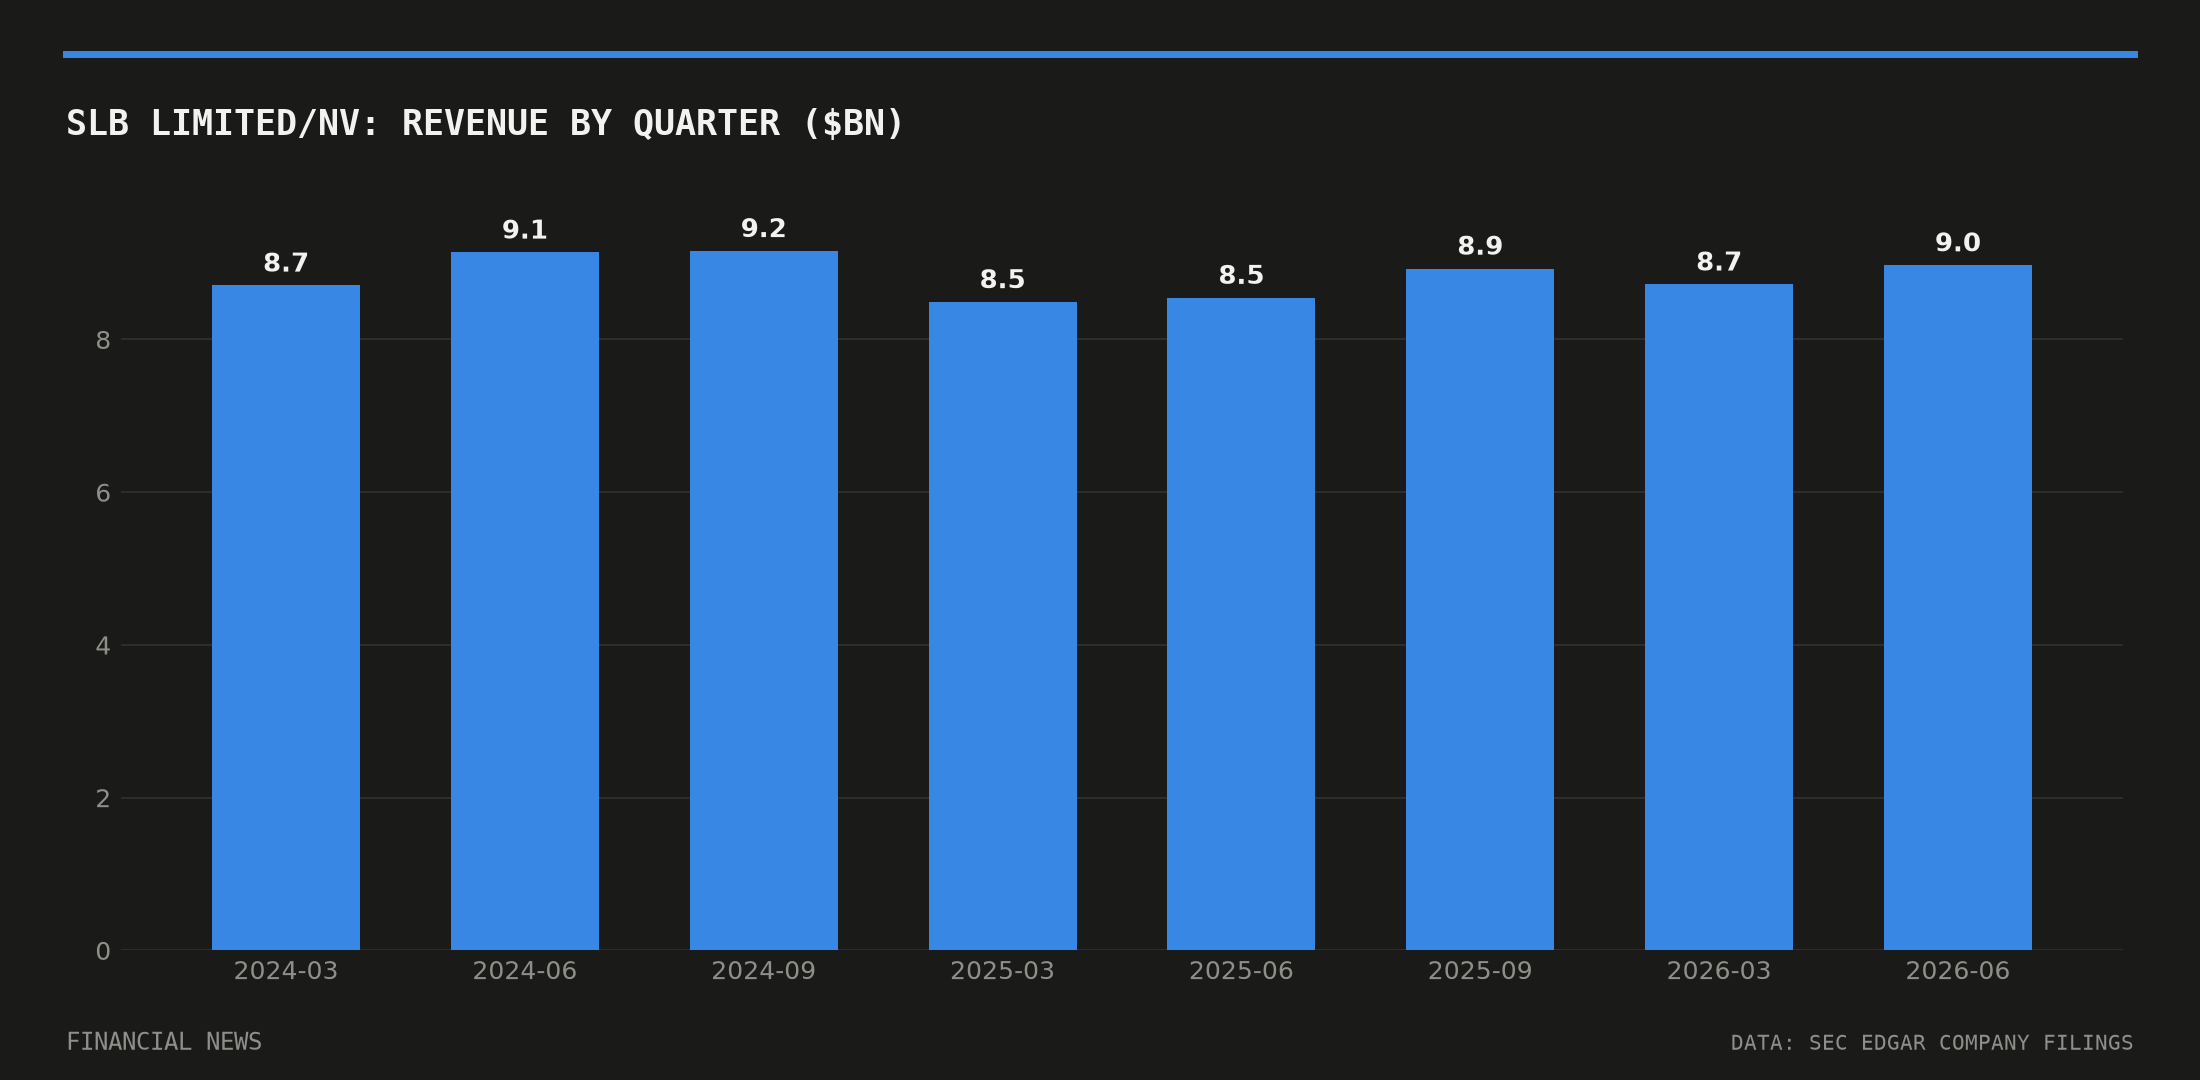
The headline figures tell two stories at once. Revenue climbed to its highest level in the period under review, but profitability narrowed. GAAP income before taxes was $1,019m, broadly flat against the second quarter’s $1,018m, with the margin slipping to 10.8% from 11.4% – a drop of 57 basis points sequentially and 42 basis points year-on-year, the filing shows.
GAAP diluted earnings per share fell to $0.49, down from $0.52 in the second quarter and $0.50 a year earlier. On a non-GAAP basis, SLB reported EPS of $0.64, ahead of the $0.62 consensus tracked by analysts, as Yahoo Finance and Zacks reported. The same figures beat the Zacks revenue consensus by 1.72%, while a separate estimate tracked by GuruFocus put consensus revenue at $9.27bn against SLB’s actual $9.45bn.
The gap between the non-GAAP beat and the GAAP softening is the real story in this print. Revenue growth has outpaced bottom-line growth for two straight quarters, with net income attributable to SLB sliding from $786m in the second quarter to $735m now – even as the top line hit a new high.
ChampionX and Middle East lift the top line
SLB pointed to broad-based regional strength behind the revenue gain, including a 13% sequential increase in Middle East activity, according to GuruFocus. The quarter also included record revenue contribution from the ChampionX production-chemicals business, which SLB acquired and has layered into reporting since the deal closed.
Those additions have helped offset margin pressure elsewhere in the business. The board approved a quarterly cash dividend of $0.295 per share alongside the results, maintaining the payout even as GAAP profitability eased.
Shares rise as short interest had been building
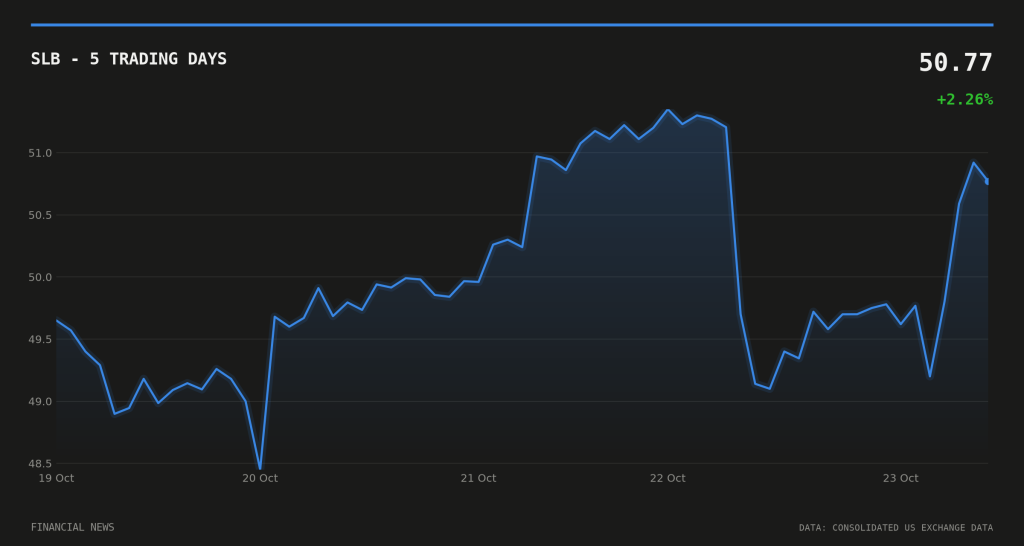
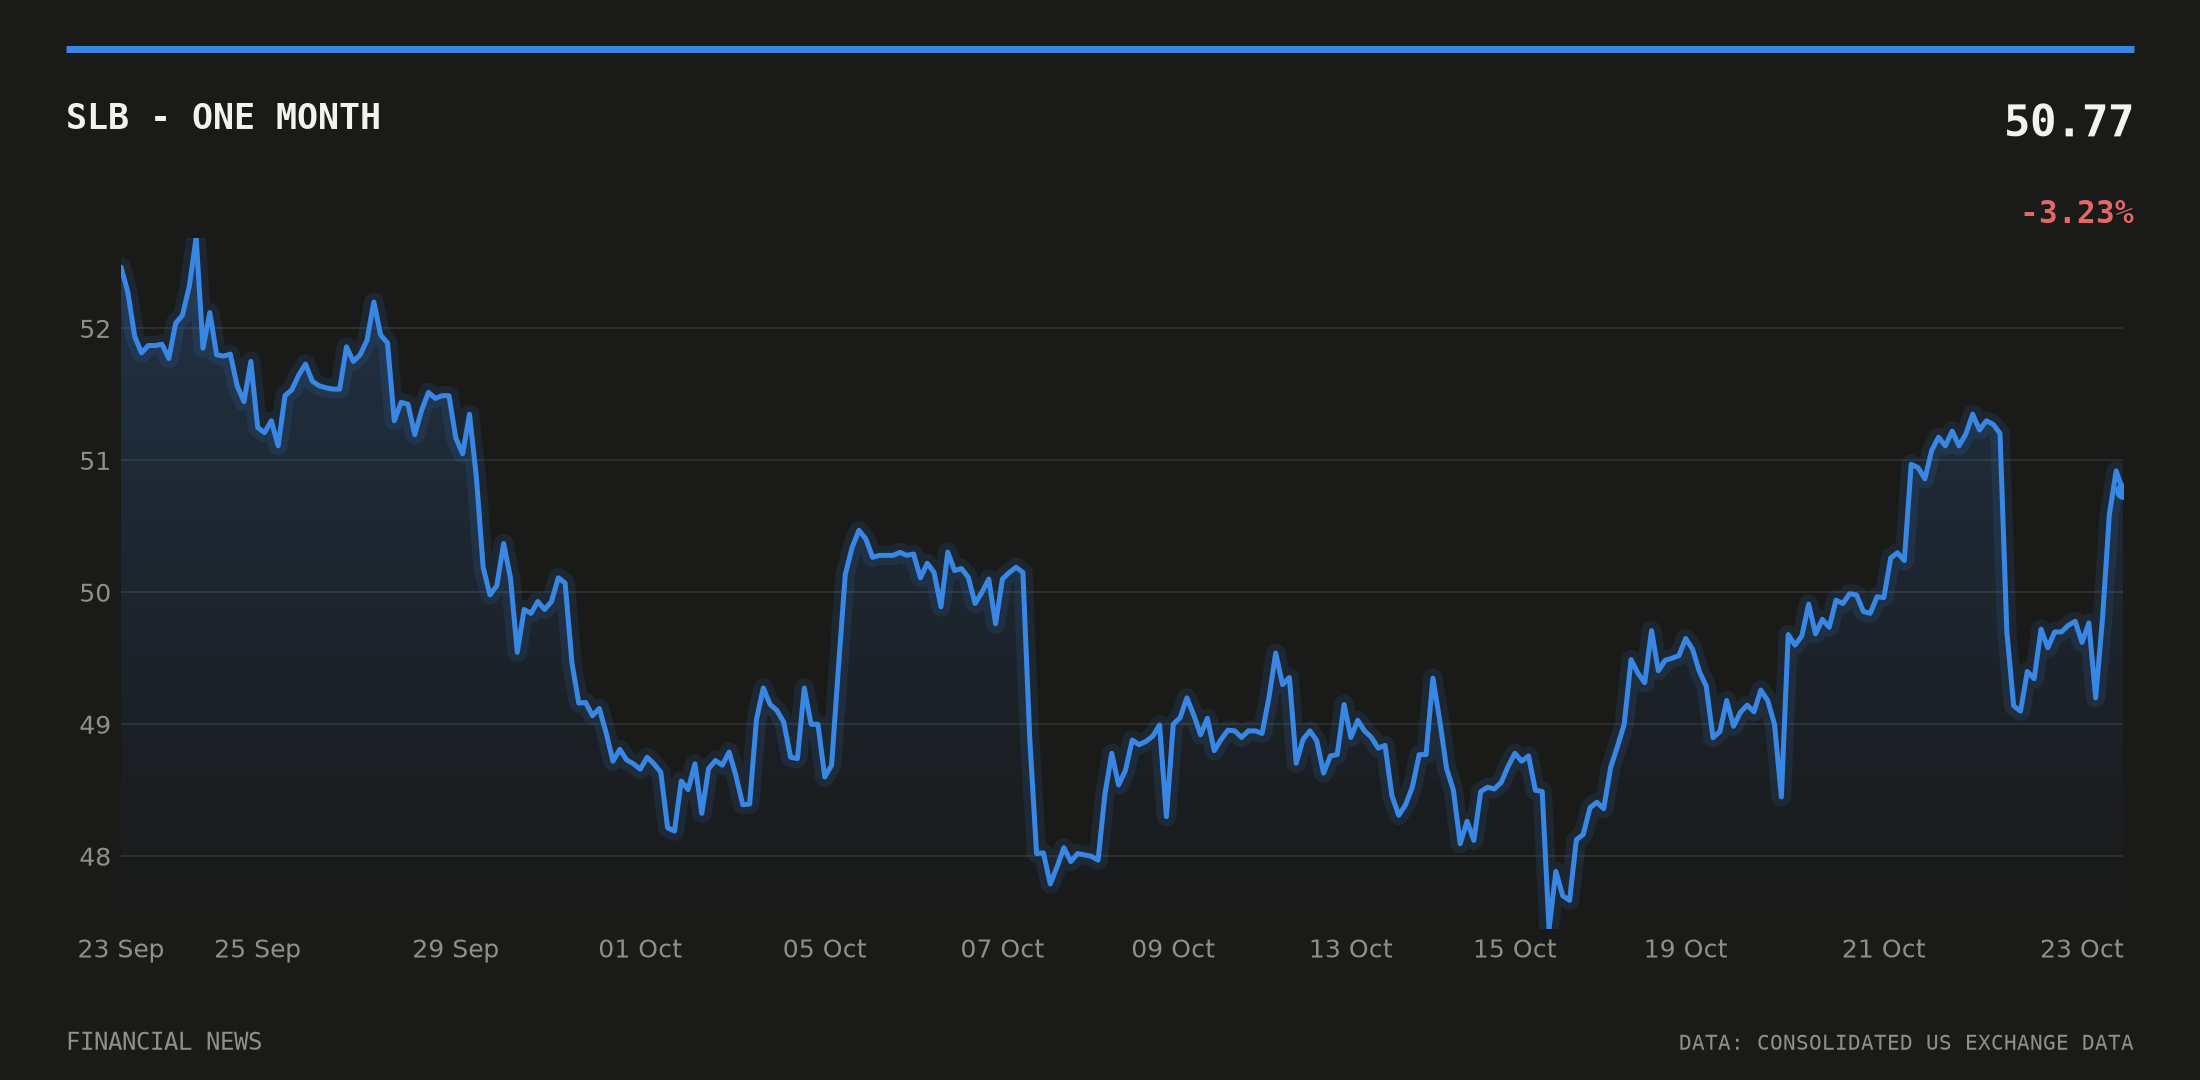
SLB shares closed at $50.92, up 2.29% on the day the results were digested and 3.34% higher over the past 20 trading days, against a 20-day range of $47.45 to $51.35. Trading volume ran at roughly a third of the 20-day average, suggesting the move came on lighter-than-usual turnover.
The rally followed a build-up in bearish positioning. FINRA short-sale volume data show SLB’s short-volume ratio climbing steadily from 0.381 on 9 October to 0.745 by 22 October, the session before the results landed – a rise in short-side activity heading into the print that the release’s revenue beat appears to have confronted directly.
The results arrive against a backdrop of elevated US long-term borrowing costs, with the 10-year Treasury yield at 5.13% on 21 October, according to Federal Reserve data. Energy-services capital spending decisions, including the pace of further acquisitions, are being weighed against that rate environment.
For SLB, the quarter leaves a clear pattern across recent filings: revenue has grown in five of the last six quarters, while GAAP net income has been the more volatile line, swinging between $752m and $1,186m since the start of 2024. Whether the ChampionX integration and Middle East activity can translate record top-line growth into a matching recovery in GAAP margins is the question investors will carry into the next quarterly report.
This article is for information only and is not investment advice or a recommendation to buy or sell any asset. Markets move quickly; figures are correct as sourced at the time of writing. Always do your own research before making financial decisions.