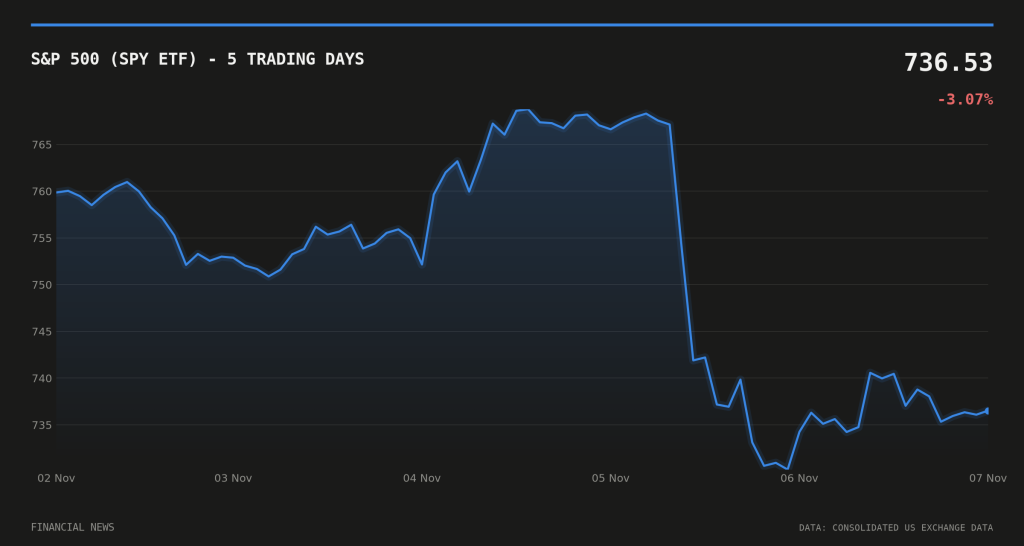
Wall Street booked its worst week in months as a rout in memory-chip and storage names overwhelmed scattered pockets of strength elsewhere in the market. The S&P 500 (SPY ETF) fell 3.07% over the week to close at 736.53.
The damage was sharper further up the risk curve. The Nasdaq 100 (QQQ ETF) dropped 5.65% to 657.50, nearly double the S&P’s decline, while the Dow (DIA ETF) held up better, losing 1.42% to finish at 512.52.
The scoreboard
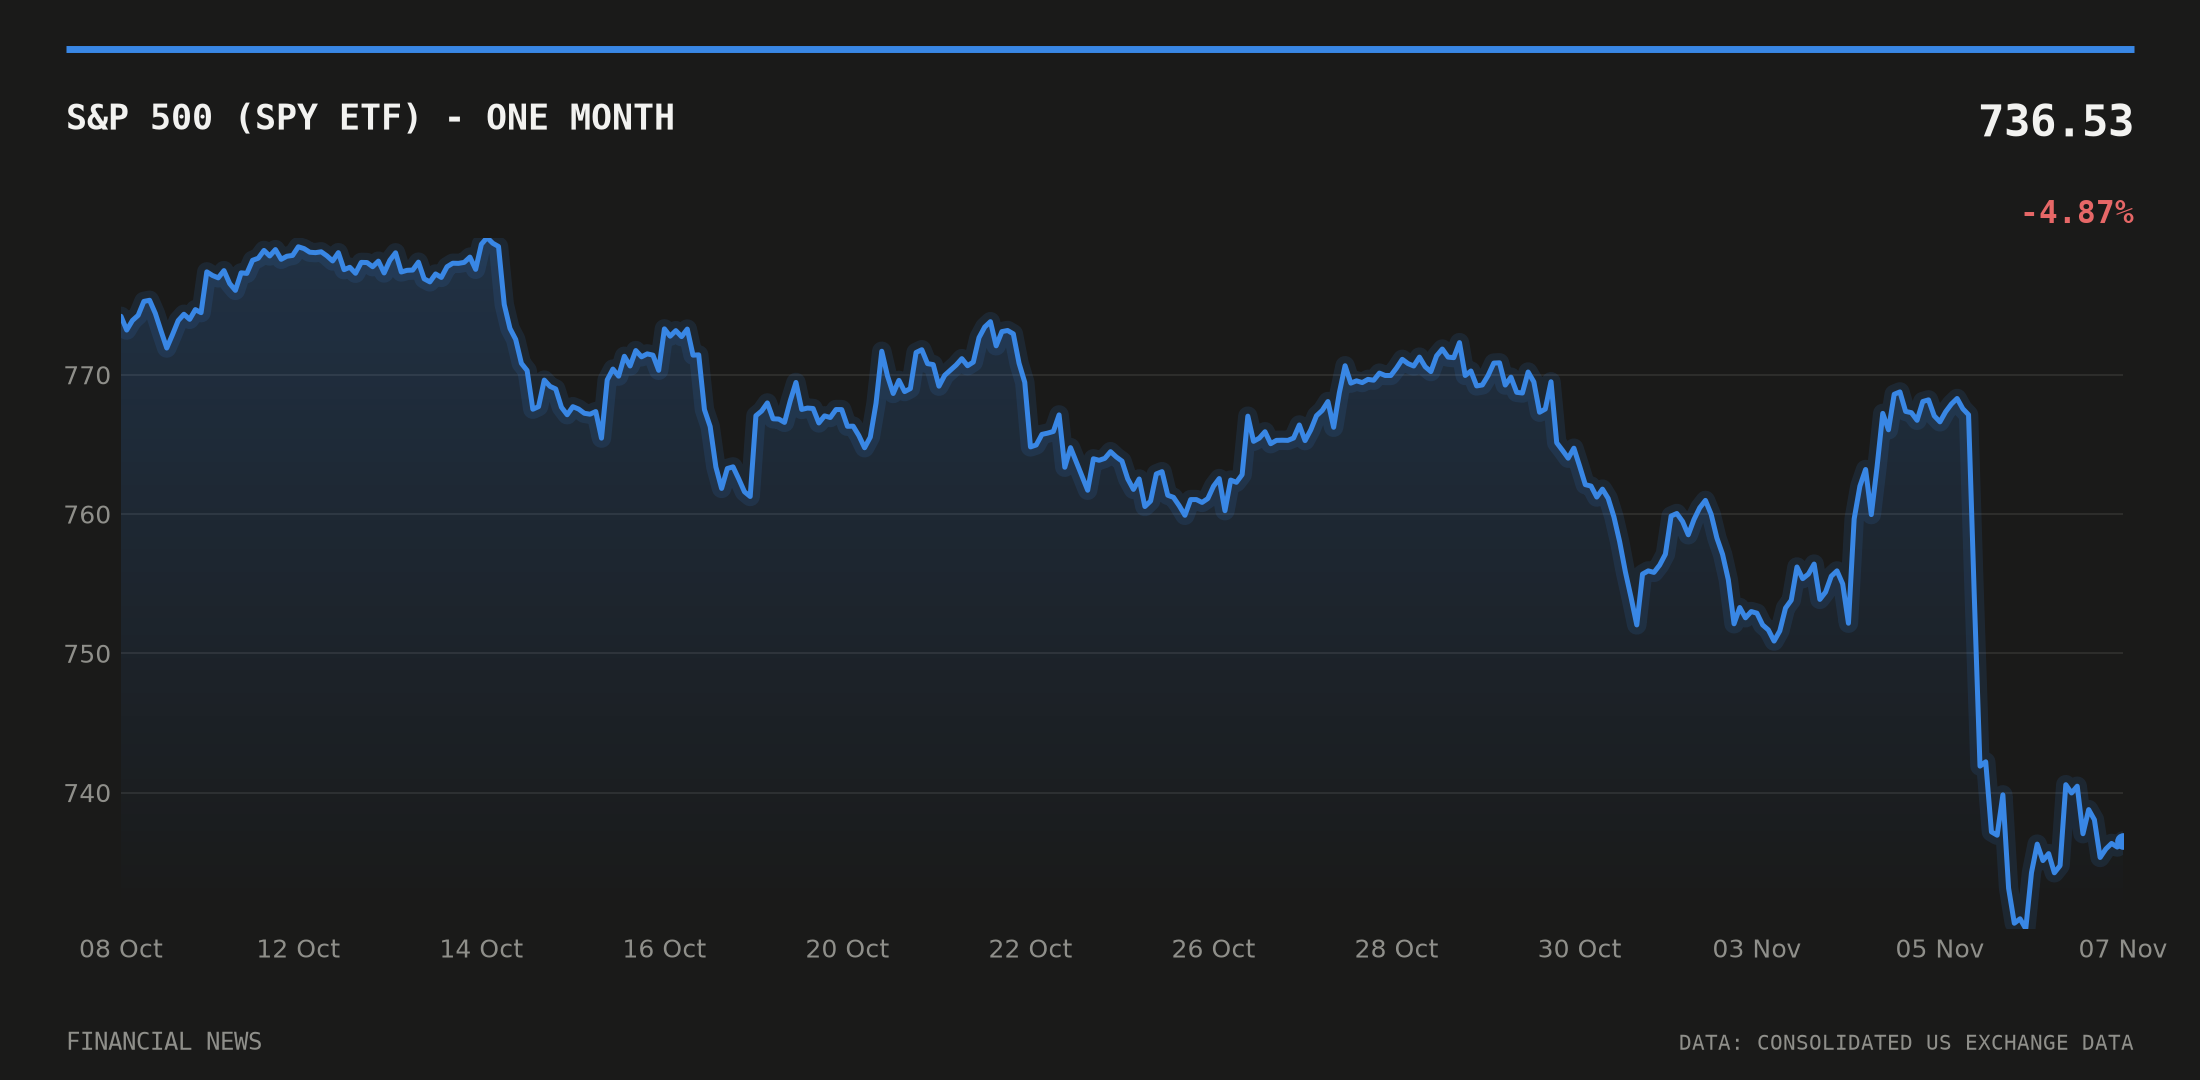
The gap between the three major gauges tells its own story this week. Blue-chip, value-tilted names in the Dow proved far more defensive than the growth and semiconductor-heavy Nasdaq 100, which bore the brunt of the selling. The S&P 500’s 3.07% decline sat roughly midway between the two, a reminder of how concentrated this week’s losses were in a specific corner of the market rather than spread evenly across sectors.
That divergence matters for anyone marking portfolios this weekend: an index-level loss in the low single digits masked far deeper damage in the names most exposed to data-centre and storage hardware demand.
Winners and losers of the week
Applovin Corp (NASDAQ: APP) led the gainers by a wide margin, surging 64.59% to 390.02. Fiserv Inc (NASDAQ: FISV) added 25.88% to close at 62.75, while Idexx Laboratories Inc (NASDAQ: IDXX) climbed 23.36% to 676.04. Mosaic Co (NYSE: MOS) rose 21.50% to 22.32, and Airbnb, Inc. (NASDAQ: ABNB) gained 15.60% to 190.74.
The losers’ column told a starkly different story, dominated almost entirely by storage and memory hardware. Lumentum Holdings Inc (NASDAQ: LITE) was the week’s heaviest faller, down 37.65% to 540.32. Seagate Technology Holdings Plc (NASDAQ: STX) dropped 30.17% to 462.99, Western Digital Corp (NASDAQ: WDC) fell 29.96% to 264.18, Marvell Technology, Inc. (NASDAQ: MRVL) slid 29.68% to 141.52, and Sandisk Corp (NASDAQ: SNDK) lost 29.24% to close at 835.65.
Five of the week’s biggest movers sitting in the same hardware supply chain, all falling by roughly 30% or more in five trading days, points to a sector-specific reckoning rather than broad market stress. Elsewhere this week, earnings reactions were just as uneven: Qualcomm’s SpaceX 5G deal failed to offset a weaker earnings print, while Emerson Electric’s order book told a more encouraging story for industrials.
The macro shift
Treasury yields eased across the curve over the week, a move that would normally offer some support to equities but did little to cushion the hardware sell-off. The 10-year yield slipped to 4.84% as of 5 November, from 4.90% previously, according to FRED data from the Federal Reserve Bank of St. Louis. The 2-year yield fell further, to 4.46% from 4.58%, per the same source.
The 10-year/2-year spread narrowed slightly to 0.35 percentage points from 0.38, FRED figures show, keeping the curve positively sloped but only modestly so. Oil drifted lower too, with West Texas Intermediate crude easing to $99.64 a barrel as of 3 November from $100.06 previously, according to FRED. None of these moves were large enough to explain the scale of the equity declines; this was a sector story, not a rates story.
What else moved the market
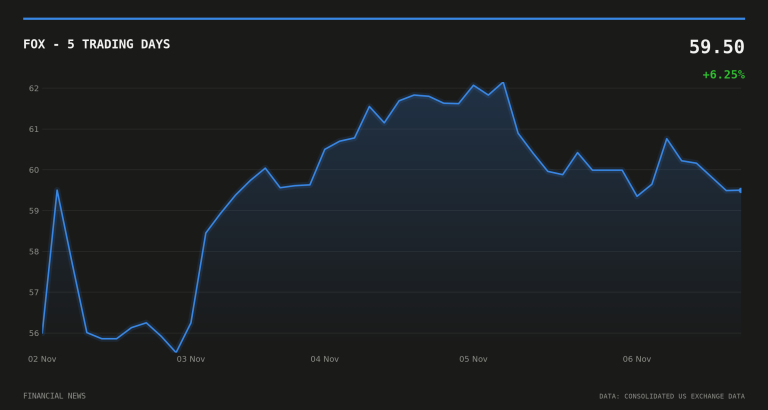
Corporate news flow stayed busy even as the chip rout dominated headlines. Fox completed its $22bn acquisition of Roku, closing one of the year’s larger media deals, while Blackstone led a $3.1bn investment in an LNG Canada stake, underlining continued private-capital appetite for energy infrastructure. Apollo also pressed ahead with its credit ambitions, launching a €10bn European Credit Company.
Earnings reactions elsewhere reinforced the week’s theme of beats that failed to satisfy. Apple fell despite a record quarter as margin guidance disappointed investors, and Sysco shares dropped around 8% even after an earnings beat, as a revenue miss overshadowed the headline number. Gartner suffered a similar fate, with a 13% share slide following results that technically beat forecasts.
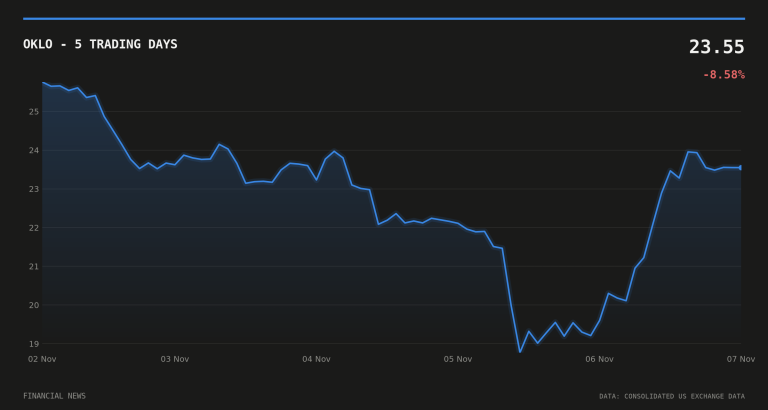
Not every surprise was negative. Oklo’s shares rose on a new manufacturing partnership alongside an earnings beat, and Sunstone Hotel lifted its 2026 guidance for a second consecutive quarter after beating forecasts. Rocket Lab was among the casualties of the broader tech reassessment, with its stock falling 12% in an AI-linked sell-off that echoed the week’s wider caution toward high-multiple growth names.
The number of the week
Set against a 3.07% weekly decline for the S&P 500, the 37.65% collapse in Lumentum stands as the number that defined the week. A single storage-and-optics supplier lost more value in five sessions than the broad market lost in the entire month before it, a gap that underscores how unevenly this week’s stress was distributed across the market. For a market otherwise navigating a gently easing yield environment, the chip and storage sell-off was the exception that drove the headline numbers, not the macro backdrop that usually gets the blame.
This article is for information only and is not investment advice or a recommendation to buy or sell any asset. Markets move quickly; figures are correct as sourced at the time of writing. Always do your own research before making financial decisions.