Emerson Electric (EMR) delivered a Q4 earnings beat on 4 November 2026, topping Wall Street forecasts on both profit and sales for the quarter ended 30 September.
Adjusted earnings per share came in at $1.86, a cent above the $1.85 consensus tracked by Zacks, while revenue of $5.20bn beat the roughly $5.12bn analysts had pencilled in, according to Zacks.
Emerson Q4 earnings beat driven by orders and backlog
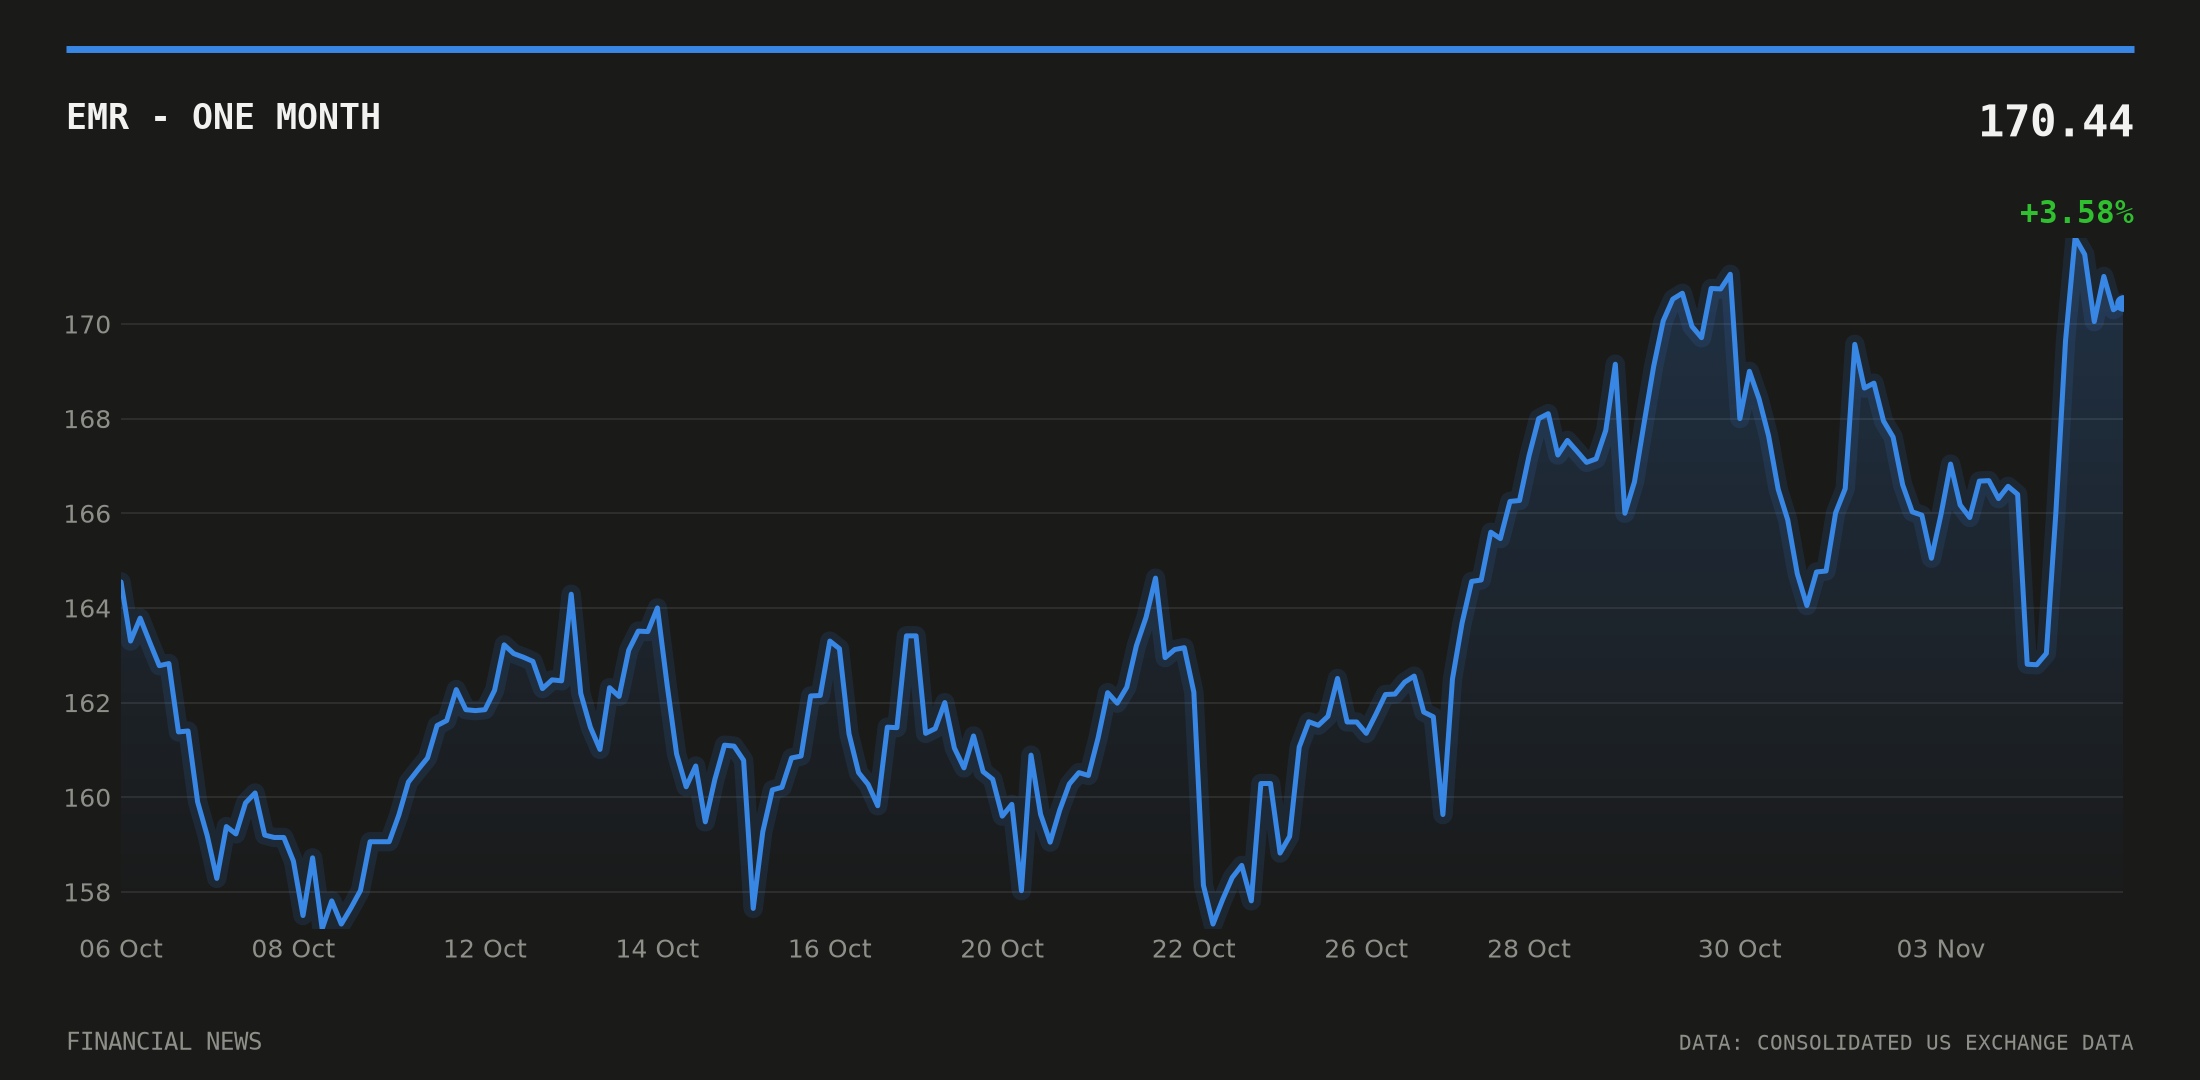
Net income for the quarter reached $744m, with GAAP diluted earnings per share of $1.33, as first reported by the Associated Press. That compares with sales of $4,855m and net income of $609m a year earlier, according to MarketScreener’s summary of the official results.
Underlying sales growth ran at 7% in the quarter, Emerson’s own investor relations release confirmed, alongside the headline adjusted EPS figure of $1.86.
The stronger signal sat beneath the headline numbers. Underlying orders grew 14% in the quarter, and backlog excluding AspenTech rose 11% to $8.2bn, giving management visibility into the new fiscal year, according to Investing.com’s coverage of the results presentation. On the earnings call, Emerson said full-year adjusted EPS of $6.59 marked a sixth consecutive year of double-digit adjusted growth, and guided fiscal 2027 adjusted EPS to approximately $7.25 – roughly 10% higher – as reported by Yahoo Finance’s transcript of the call.
Shares already running hot into the print
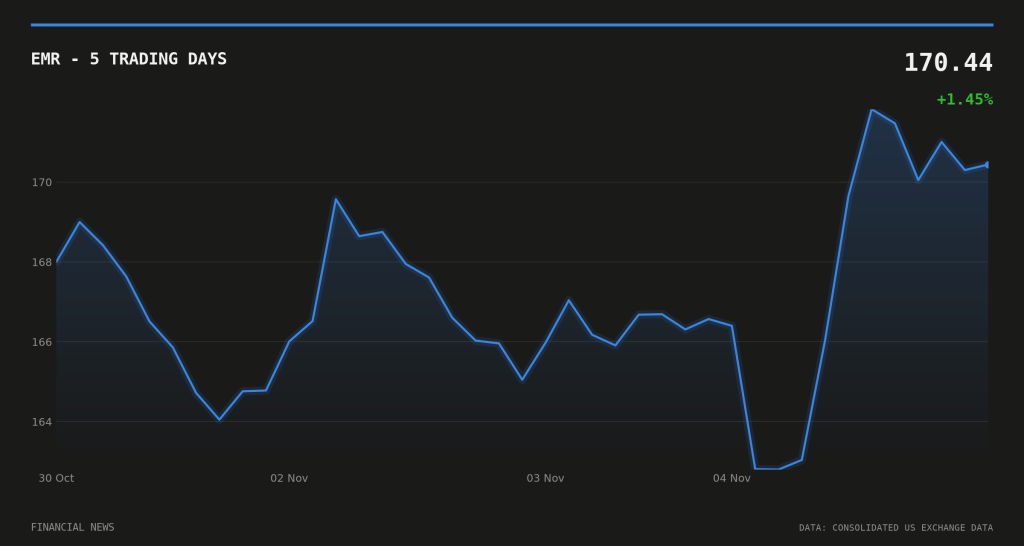
EMR shares traded at $170.44 as of 21:00 UTC on 4 November, up 2.65% on the day. The stock had already climbed 6.01% over the prior 20 trading sessions and was sitting close to its 20-day high of $171.825 heading into the release, with volume on report day running at 1.8 times the 20-day average, according to consolidated US exchange data. Daily short-sale volume on EMR had ranged between roughly 0.25 and 0.76 of total volume over the ten sessions to 4 November, per FINRA data, with no sign of a short squeeze building into the print.
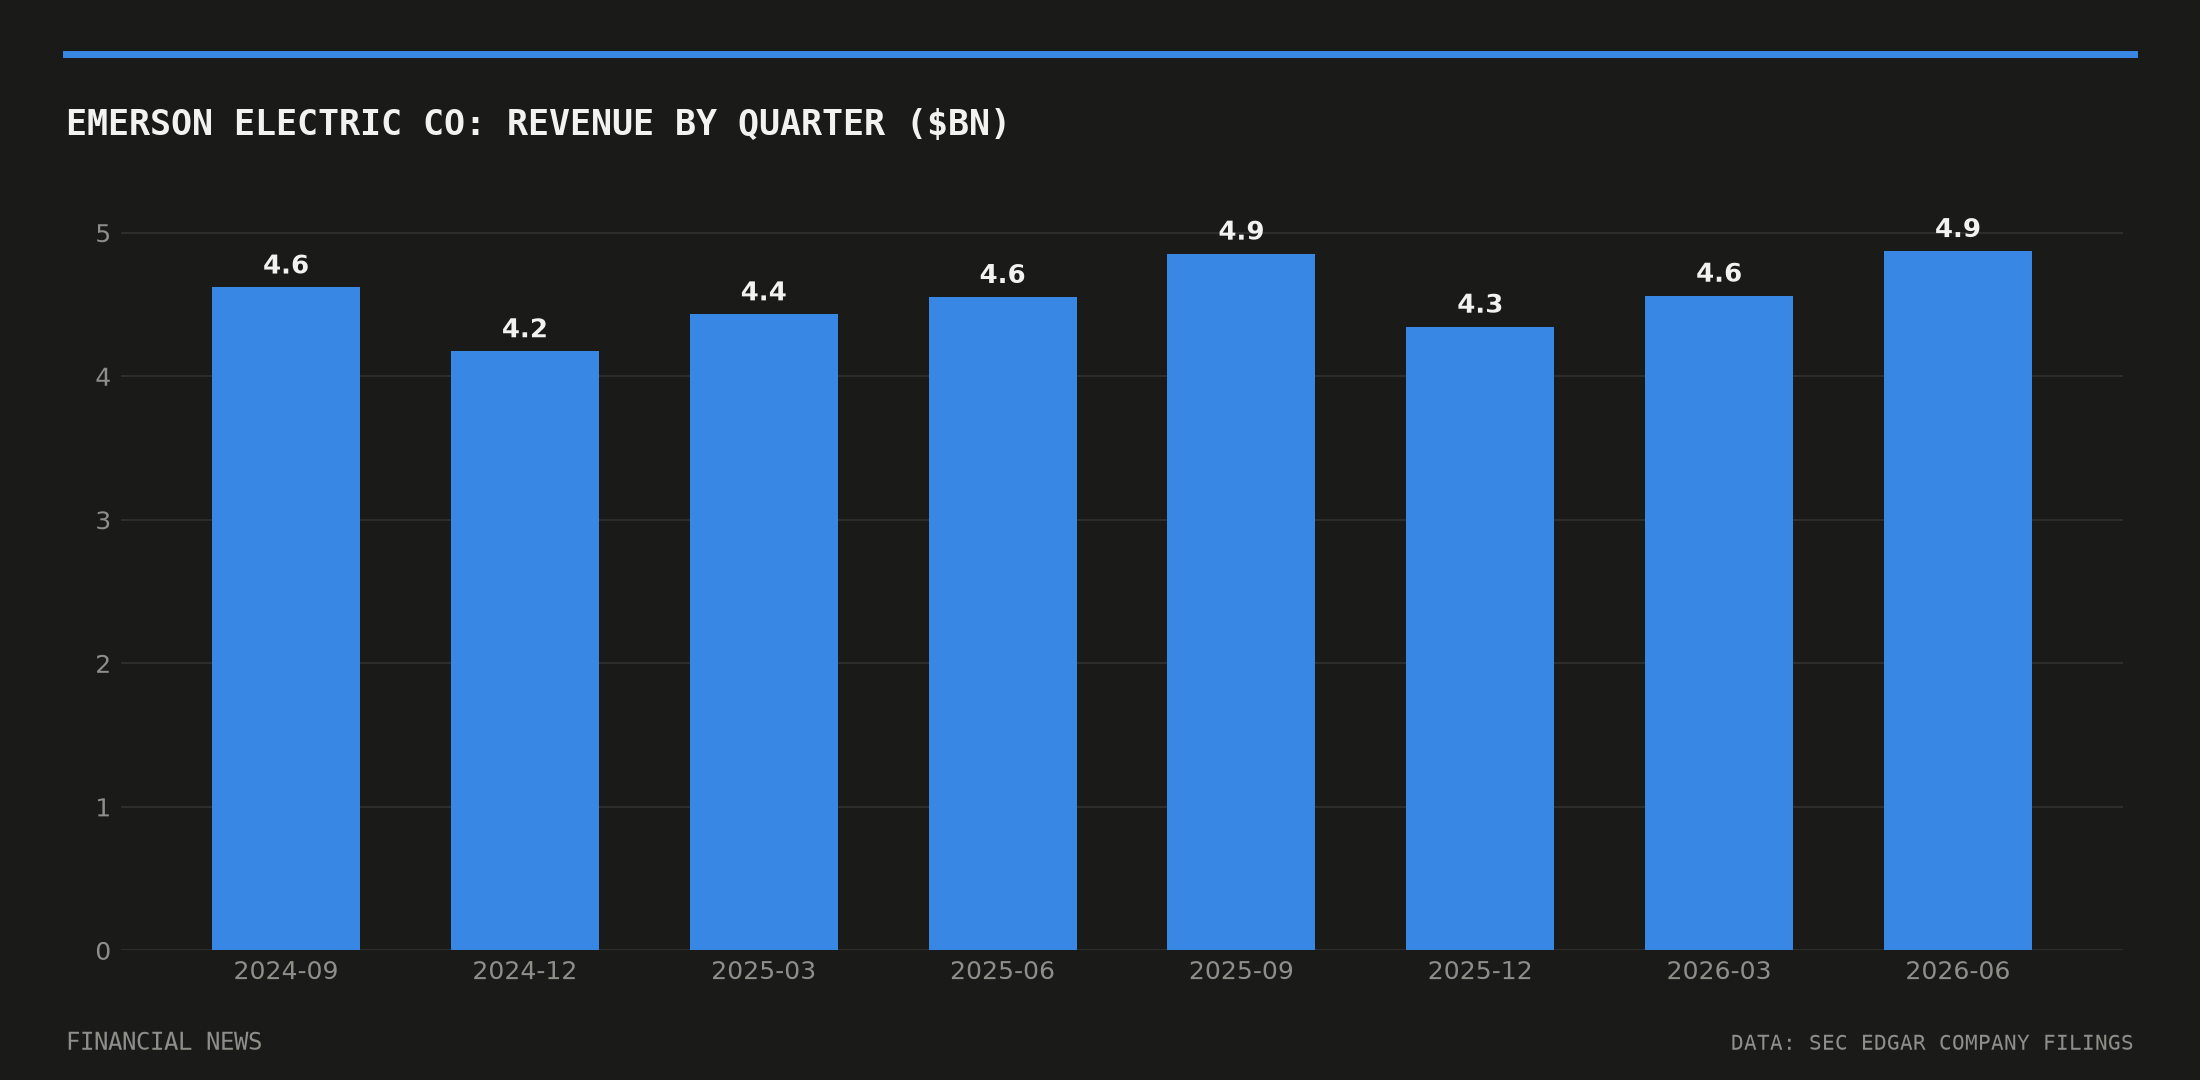
The beat extends a run of sequential revenue gains through fiscal 2026. Quarterly revenue climbed from $4,346m in the first fiscal quarter to $4,562m in the second and $4,873m in the third, according to Emerson’s 10-Q filings with the SEC, before the fourth quarter’s $5,201m closed out the year at its highest quarterly level. Diluted EPS over the same three quarters moved from $1.07 to $1.28, tracking the broader climb in profitability that carried into the fourth-quarter print.
Eleven Form 4 filings landed with the SEC within hours of the earnings release, covering executives including chief financial officer Michael H. Train and other senior officers, filings show. The timing is typical of routine post-earnings equity award reporting rather than any reaction to the results themselves.
Macro backdrop stays mixed for industrials
The report lands against a backdrop of still-elevated US borrowing costs. The 10-year Treasury yield stood at 4.95% on 3 November, up from 4.91% previously, according to FRED data from the Federal Reserve Bank of St Louis. The 10-year/2-year spread narrowed slightly to 0.32 percentage points from 0.34, a backdrop that keeps financing costs in focus for capital-intensive industrial names even as order books fill up.
Management flagged a cautious note on parts of its international demand picture even as it raised full-year guidance, pointing to the gap between robust US order momentum and softer conditions elsewhere. With backlog at $8.2bn and 2027 adjusted EPS guidance set at roughly $7.25, investors will watch Emerson’s first-quarter update early next year for confirmation that order strength is converting into delivered revenue.
This article is for information only and is not investment advice or a recommendation to buy or sell any asset. Markets move quickly; figures are correct as sourced at the time of writing. Always do your own research before making financial decisions.