Blackstone (NYSE: BX) has agreed to lead a $3.1bn investment in a Mitsubishi Corporation subsidiary that holds the Japanese trading house’s stake in LNG Canada, the private equity firm said on 2 November 2026.
Funds managed by Blackstone Credit & Insurance, together with Canadian pension investors, will take a 49.9% non-controlling interest in the subsidiary. The group includes CPP Investments, OMERS, IMCO and PSP Investments, Blackstone said.
What the $3.1bn figure covers
Blackstone’s own release and the Wall Street Journal both put the headline investment at $3.1bn. Separate reporting citing Reuters, however, values the immediate stake purchase from Mitsubishi at roughly $1.6bn, as reported.
The gap suggests the $3.1bn figure bundles the upfront purchase price with future capital commitments tied to LNG Canada’s planned Phase 2 expansion, which aims to roughly double the terminal’s export capacity to 28 million tonnes a year. Mitsubishi is expected to retain its full LNG offtake and remain the controlling partner in the project, meaning Blackstone’s investor group is buying financial exposure to the asset rather than operational control.
No 8-K disclosing the transaction’s full terms had appeared in Blackstone’s SEC filings as of the deal announcement; the most recent Blackstone-related filing on record was an unrelated Form 4 insider transaction by executive John G. Finley, dated 30 October 2026 and lodged with EDGAR. Readers should treat the $3.1bn figure as Blackstone’s own characterisation of total committed investment rather than a confirmed, line-itemed purchase price.
A strategic Canadian asset
LNG Canada is Canada’s first and only large-scale liquefied natural gas export terminal, a status Blackstone’s release cited as central to the asset’s appeal. CPP Investments’ Geoff Souter, managing director and head of real assets credit, called LNG Canada ‘a high-quality, globally strategic asset with strong long-term fundamentals and attractive return potential’ for the pension fund.
The deal extends a pattern of Blackstone teaming with Canadian pension capital on large domestic infrastructure assets. The firm completed a CDN$7bn equity investment in Rogers Communications alongside similar Canadian institutional partners last year. Blackstone’s Infrastructure and Asset Based Credit platform, which is leading the LNG Canada transaction, manages roughly $140bn across more than 100 investment professionals, according to the firm.
Balance sheet capacity
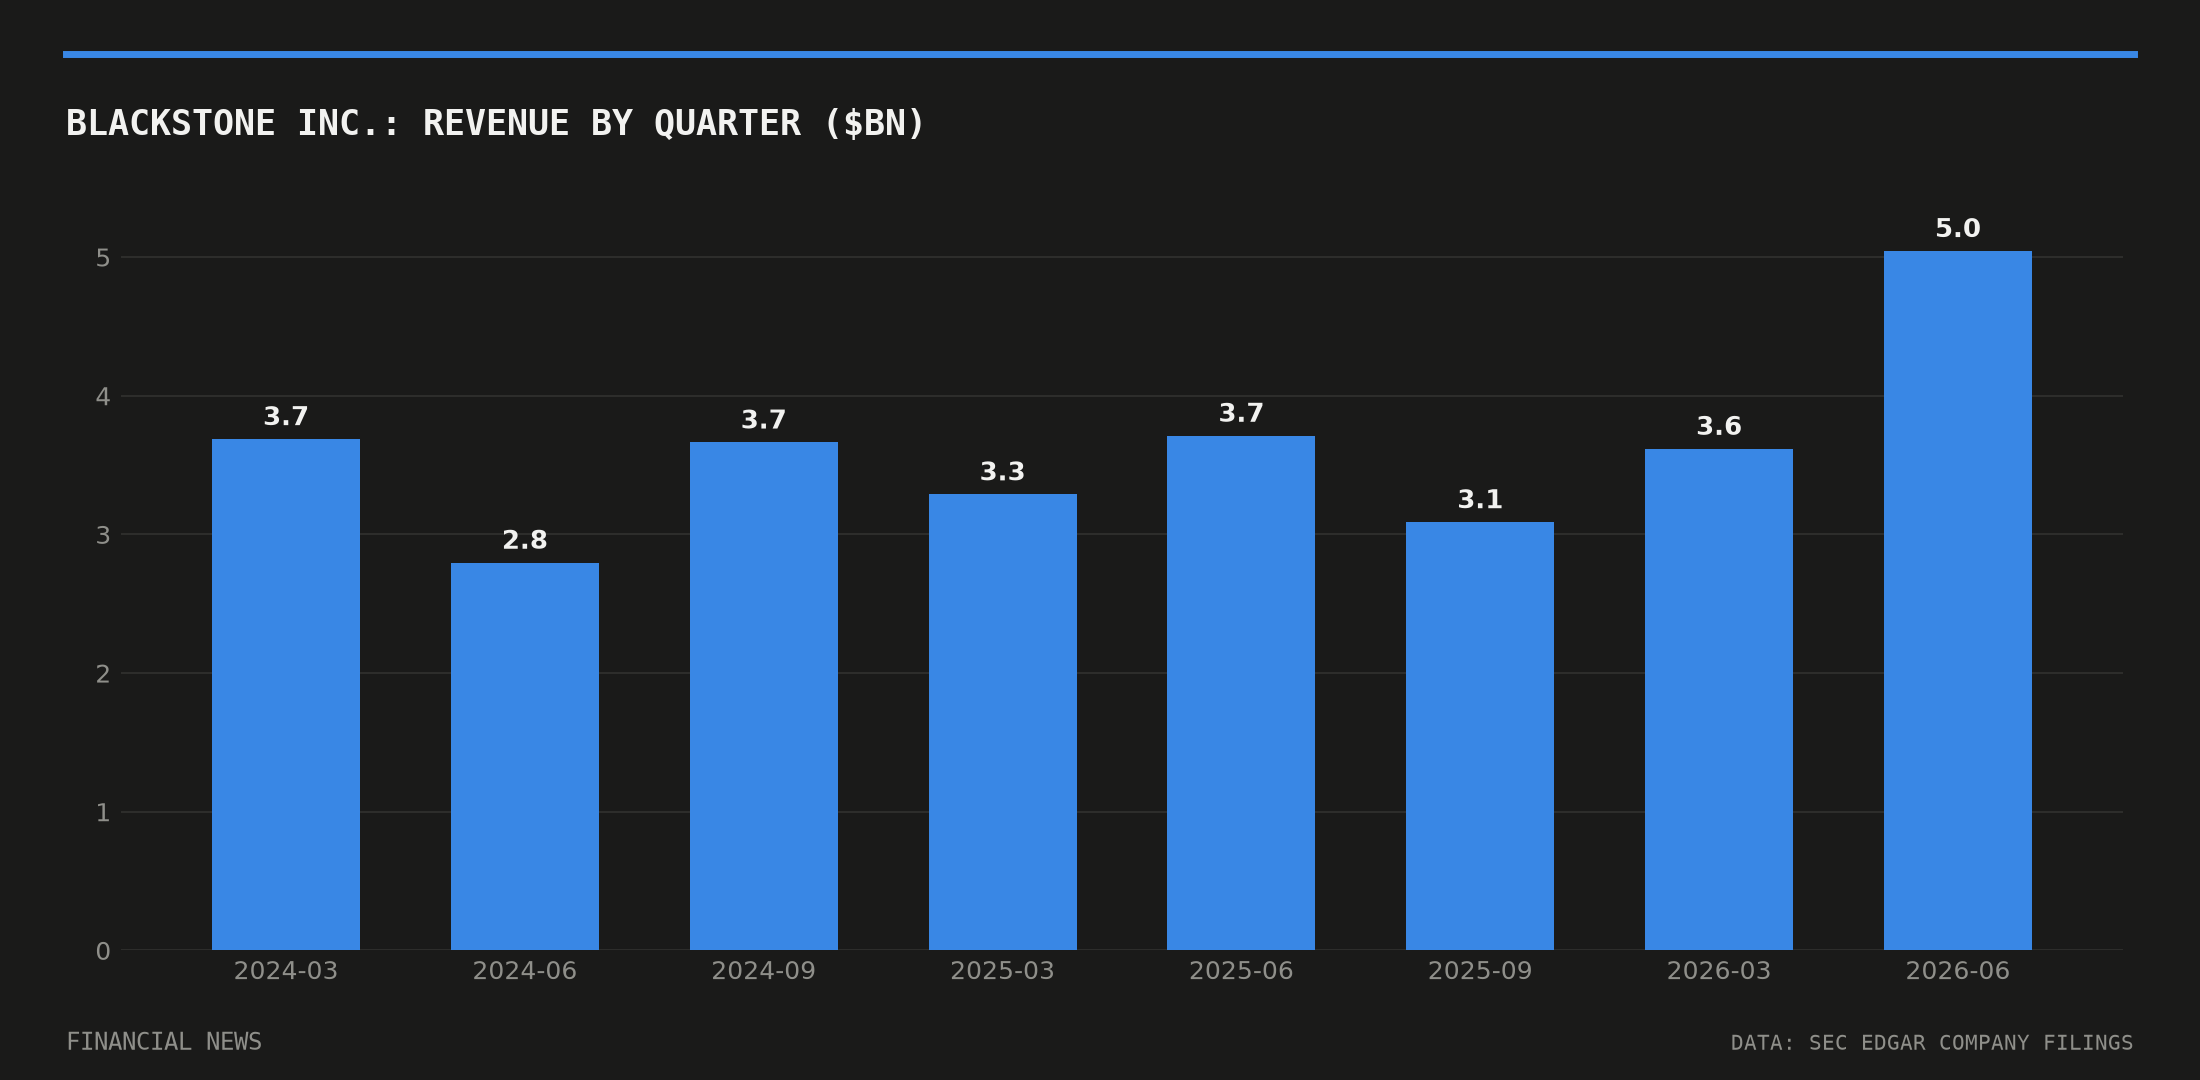
Blackstone has the earnings base to support large-scale commitments of this size. The firm reported net income of $1.23bn for the quarter ended 30 June 2026, with diluted earnings per share of $1.54, according to its 10-Q filing. That compares with quarterly net income ranging between roughly $444m and $847m across 2024 and 2025, reflecting the lumpy nature of performance fees and realisations in the business.
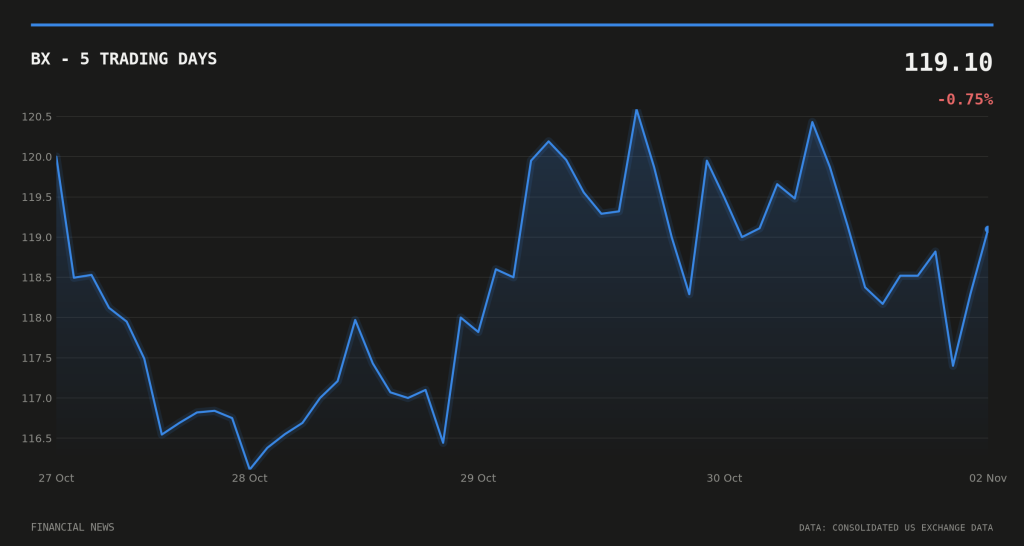
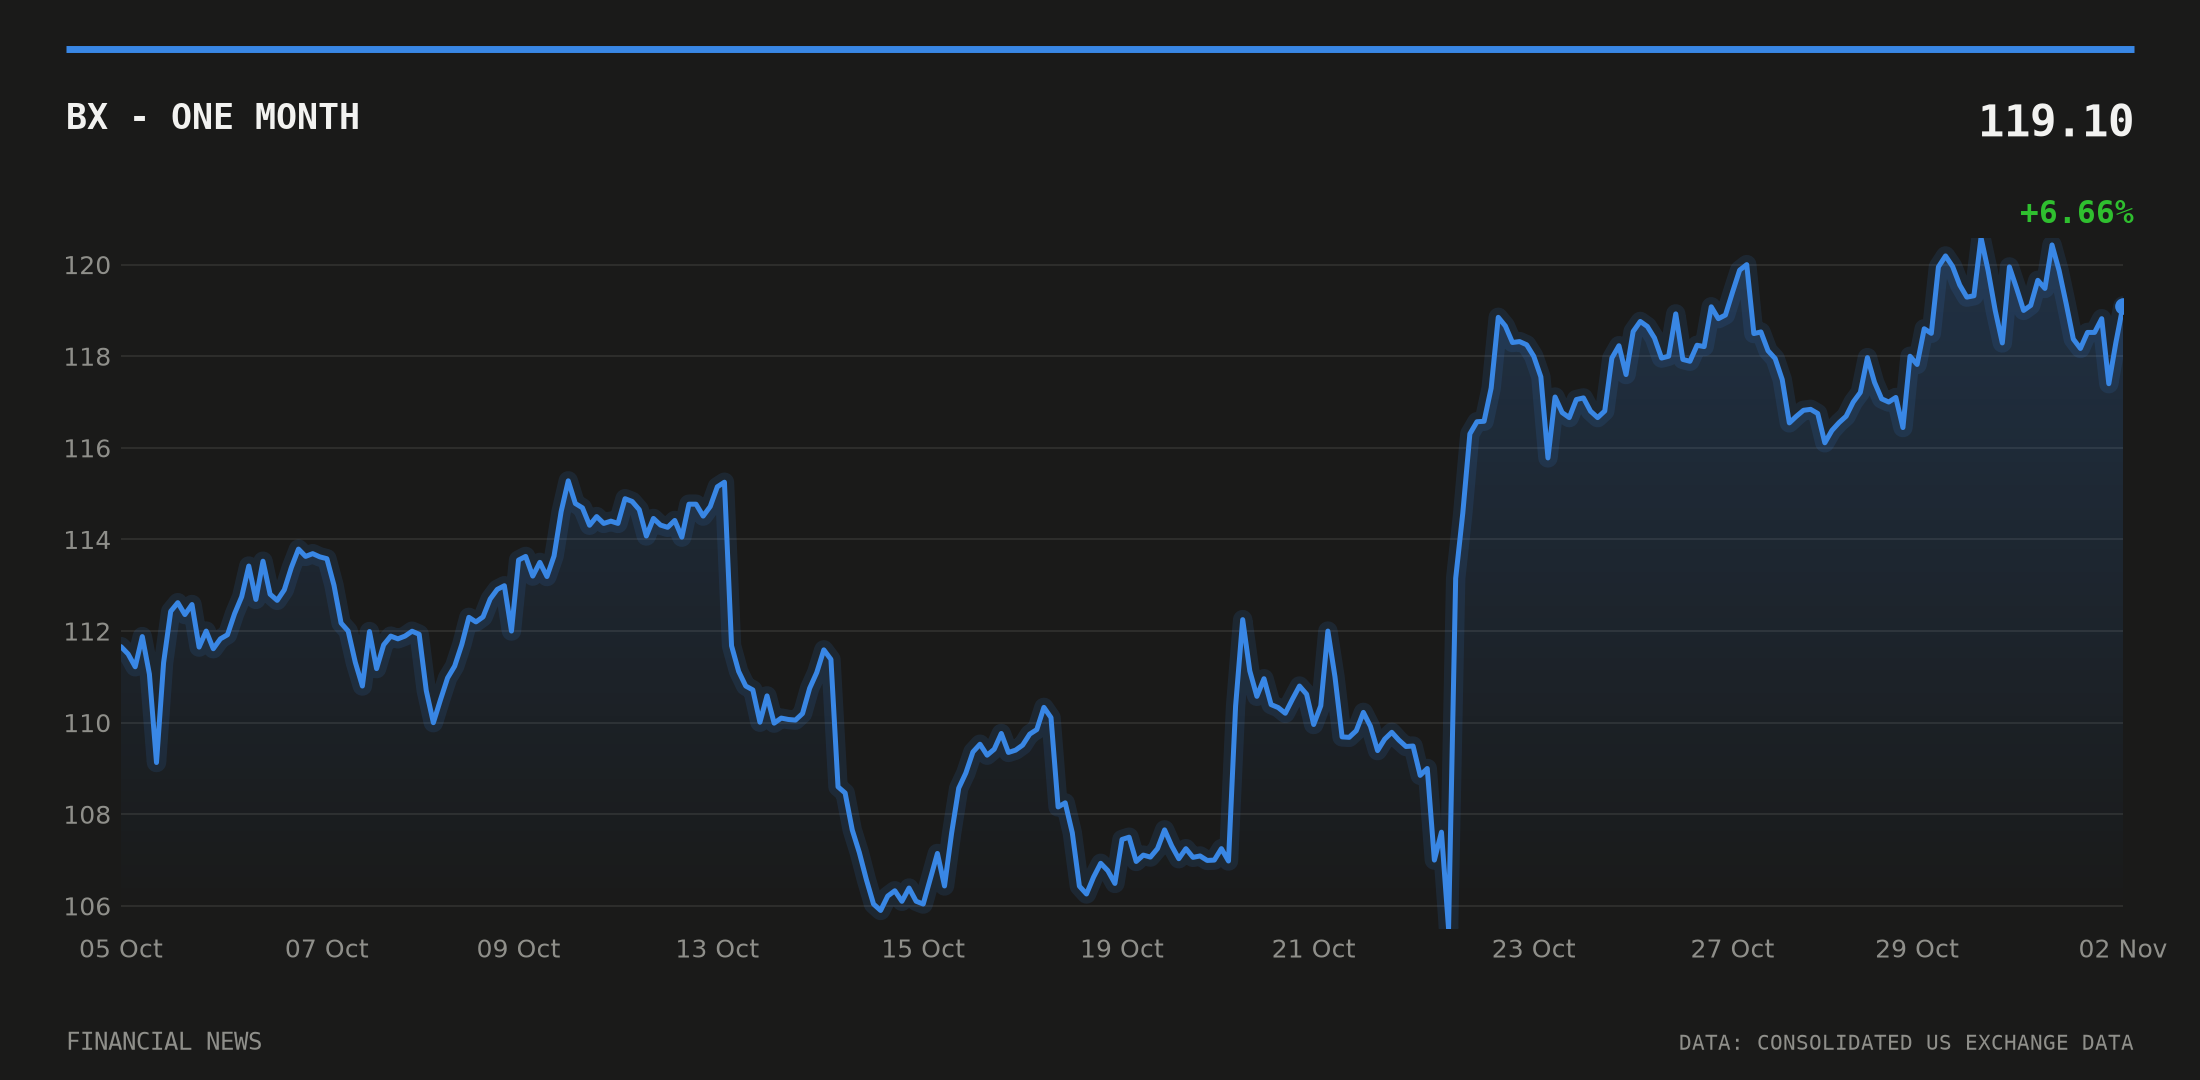
Shares in Blackstone last changed hands at $119.10, up 0.61% on the day and 3.88% over the past 20 trading sessions, near a 20-day high of $120.59, according to consolidated US exchange data cited by the Journal. The move comes against a backdrop of falling US Treasury yields, with the 10-year note at 4.98% as of 29 October, down from 5.05% a day earlier, according to FRED data from the Federal Reserve Bank of St Louis — a shift that lowers the relative cost of financing large infrastructure deals of the kind Blackstone is now leading.
Attention now turns to whether Blackstone discloses the transaction’s full terms in a future SEC filing, which would clarify how much of the $3.1bn figure represents cash paid to Mitsubishi versus capital earmarked for LNG Canada’s Phase 2 expansion.
This article is for information only and is not investment advice or a recommendation to buy or sell any asset. Markets move quickly; figures are correct as sourced at the time of writing. Always do your own research before making financial decisions.