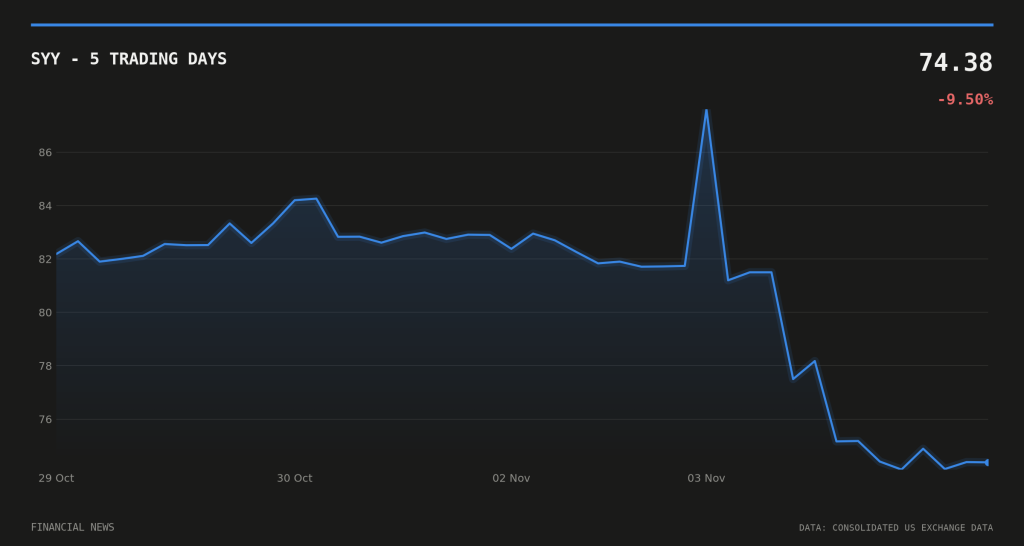
Sysco (NYSE: SYY) reported a Q1 earnings beat on an adjusted basis on 3 November 2026, but investors sold the stock anyway. Shares fell as much as 7.87% that day, according to Yahoo Finance, after sliding 7.61% in premarket trading to $75.52, Investing.com reported.
The food distributor’s revenue of $21.74bn missed the Zacks Consensus Estimate of $22.19bn for the quarter ended September 2026, according to Zacks Equity Research. Adjusted diluted earnings per share came in at $1.19, up 3.5% from $1.15 a year earlier, Sysco said in its earnings release. GAAP diluted EPS rose 10.1% to $1.09, with net earnings of $526m, up 10.5% on the year.
Why a Sysco Q1 earnings beat still spooked the market
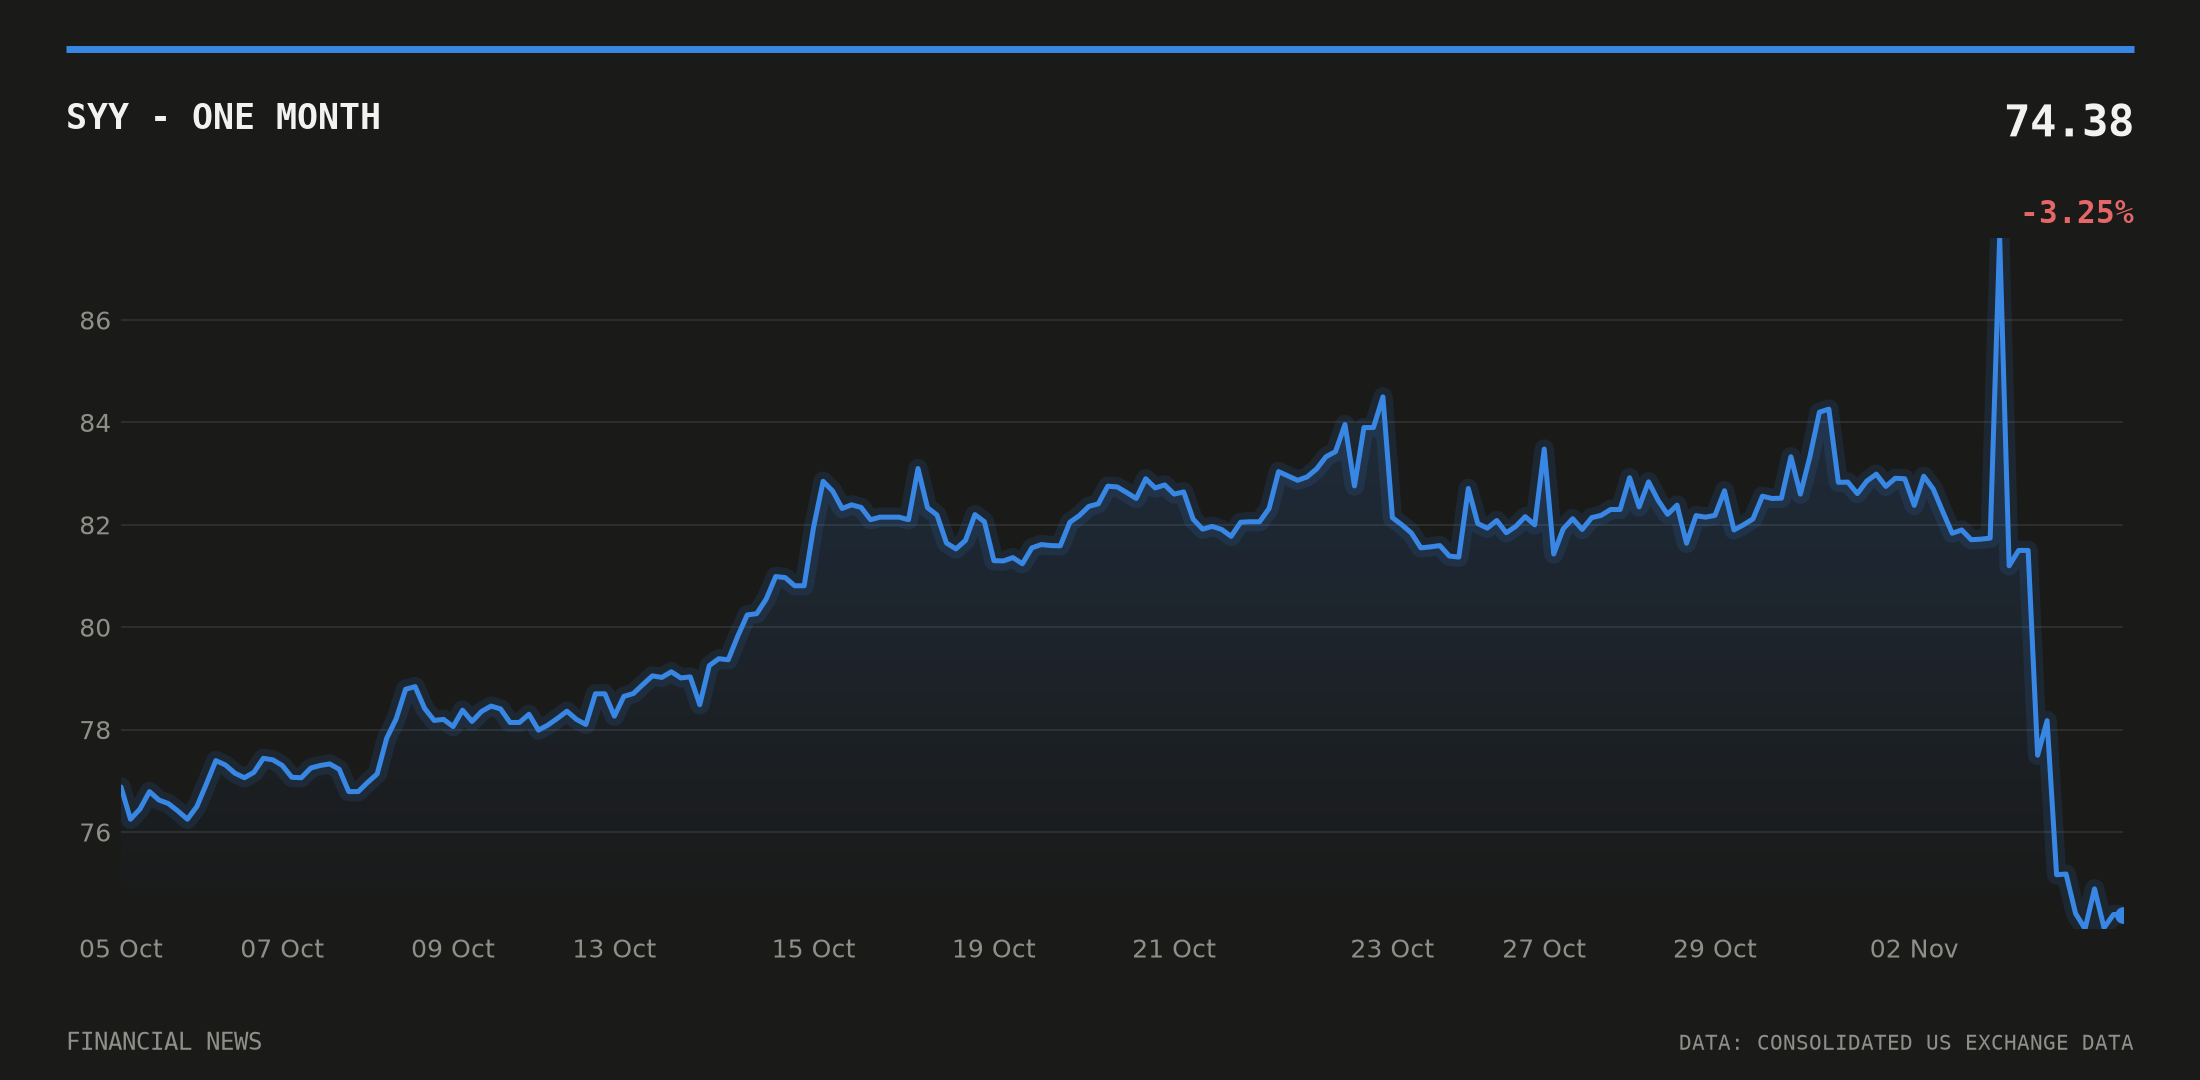
The headline figure – an adjusted-EPS beat – is narrow. It compares a single bottom-line metric against a Zacks-tracked estimate, while the top line missed by roughly $450m against consensus. For a distributor whose shares had already drifted lower over the prior month, that combination proved decisive.
Management’s own language undercut the “beat” framing. On the earnings call, executives described the $1.19 adjusted figure as “meeting our expectations” rather than exceeding them, according to a transcript carried by The Motley Fool. Chief financial officer Brandon Sewell told the call that full-year sales growth is now expected at the lower end of Sysco’s 6%-7% guidance range, citing a cooler industry inflation backdrop, the earnings release said.
The prior-year comparator holds up: Sysco’s diluted EPS for the quarter ended 27 September 2025 was $0.99, matching the “last year” figure cited in the new release, according to the company’s fiscal 2026 first-quarter 10-Q. The Associated Press separately confirmed the $526m profit, $1.09 per-share figure and $1.19 adjusted EPS in its earnings snapshot.
Heavy volume and a jump in short activity
Trading volume ran at roughly 3.2 times the 20-day average on the day of the release, consolidated exchange data show, with shares closing at $74.38 – near a 20-day low of $74.11 and well off the 20-day high of $87.61. FINRA daily short-sale data show SYY’s short ratio jumped to 0.444 on 3 November from 0.224 the previous session, consistent with the surge in turnover around the release, according to FINRA.
Two Sysco insiders, including Sewell, filed Form 4 disclosures with the SEC within hours of the earnings release. The filings for Sewell and a second reporting officer do not break out share counts or values, so no conclusion can be drawn on buying or selling intent, but the timing lines up precisely with the results.
Guidance caution meets acquisition risk
Several analyst notes on the quarter flagged “acquisition execution risk” as a factor weighing on sentiment, a reference to Sysco’s roughly $29bn pending purchase of Jetro Restaurant Depot, disclosed earlier in fiscal 2026. Chief executive Kevin Hourican addressed the deal in an interview filed with the SEC as part of the transaction’s Form 425 disclosure.
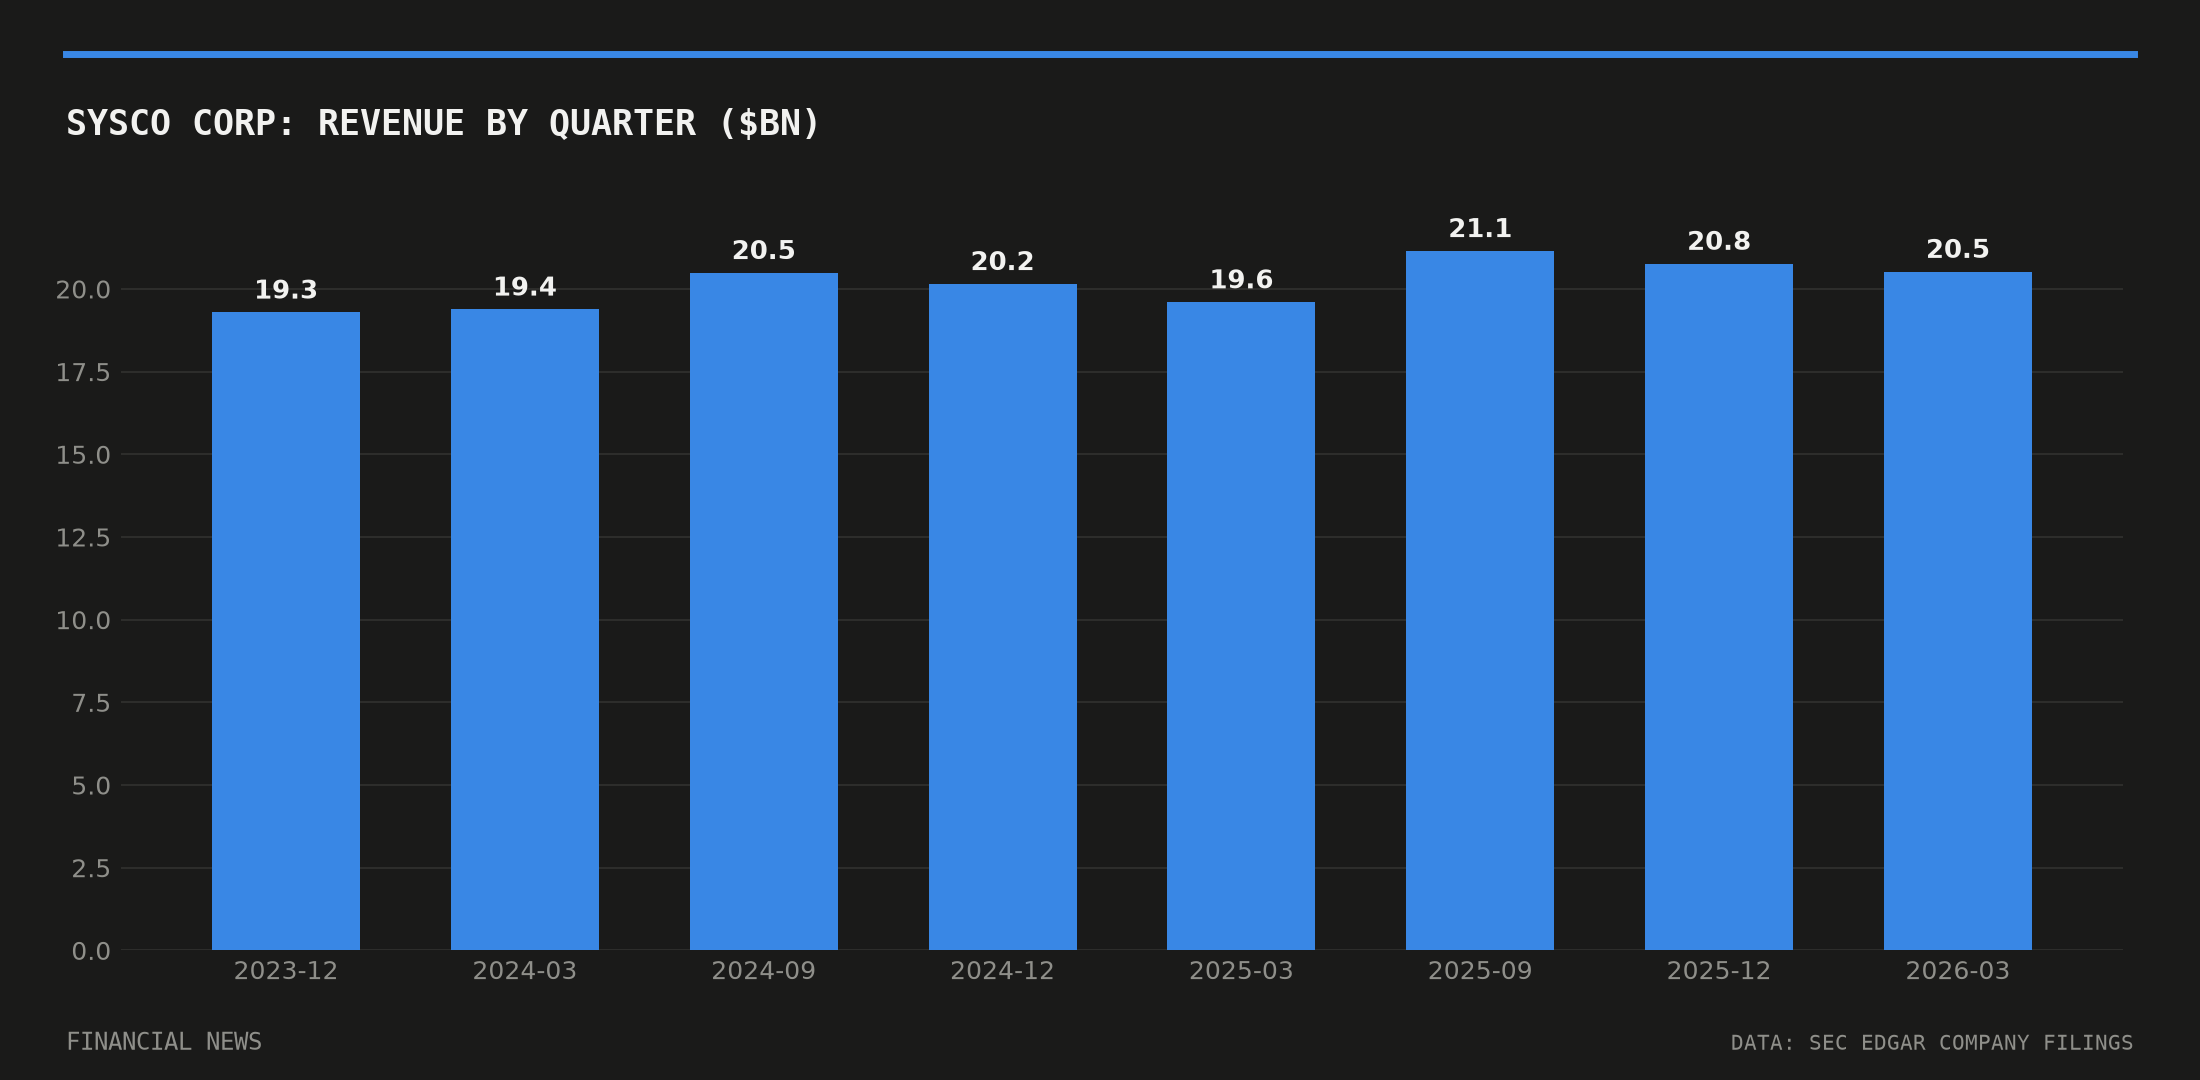
Sysco’s quarterly profit has been choppy over the past two years. Net income ran from $490m in fiscal 2025’s first quarter down to $340m by fiscal 2026’s third quarter, before recovering to $526m in the latest period – a pattern that leaves this quarter’s adjusted beat looking less like a turning point and more like one data point in a volatile run. The company’s next scheduled update, its fiscal second-quarter results, will show whether the lower end of that 6%-7% sales guidance holds.
This article is for information only and is not investment advice or a recommendation to buy or sell any asset. Markets move quickly; figures are correct as sourced at the time of writing. Always do your own research before making financial decisions.