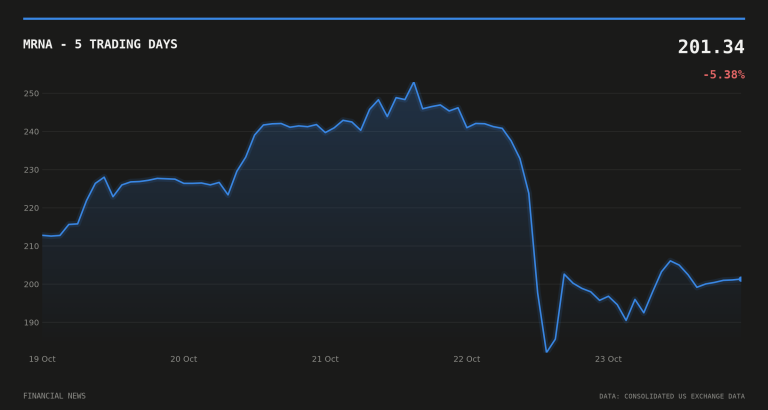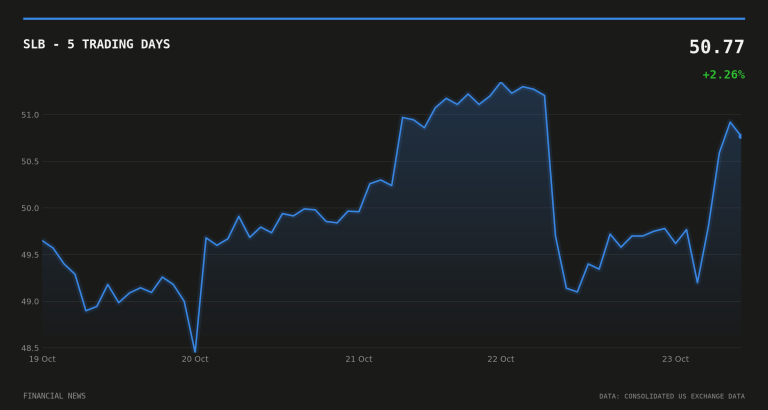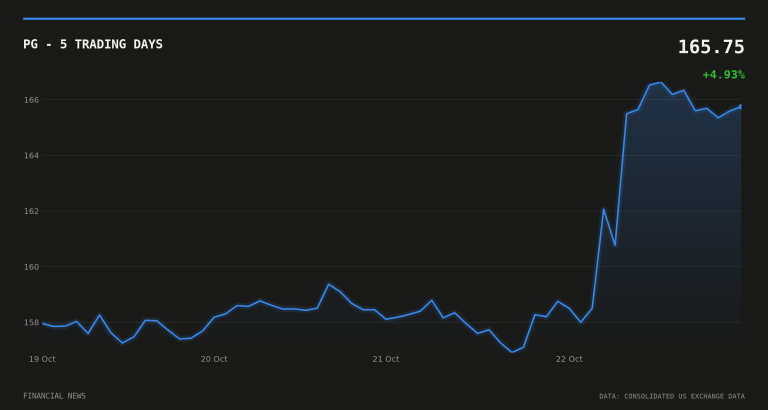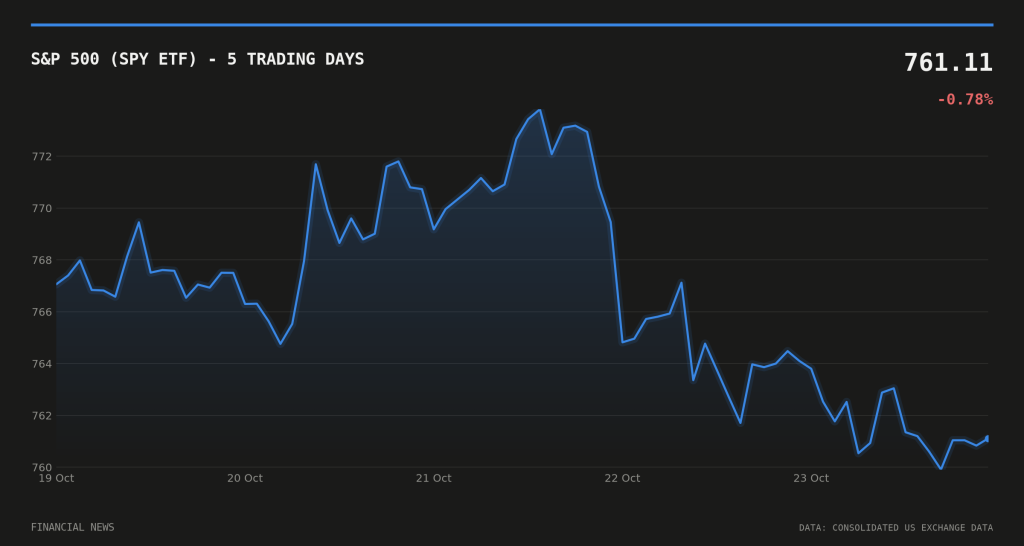
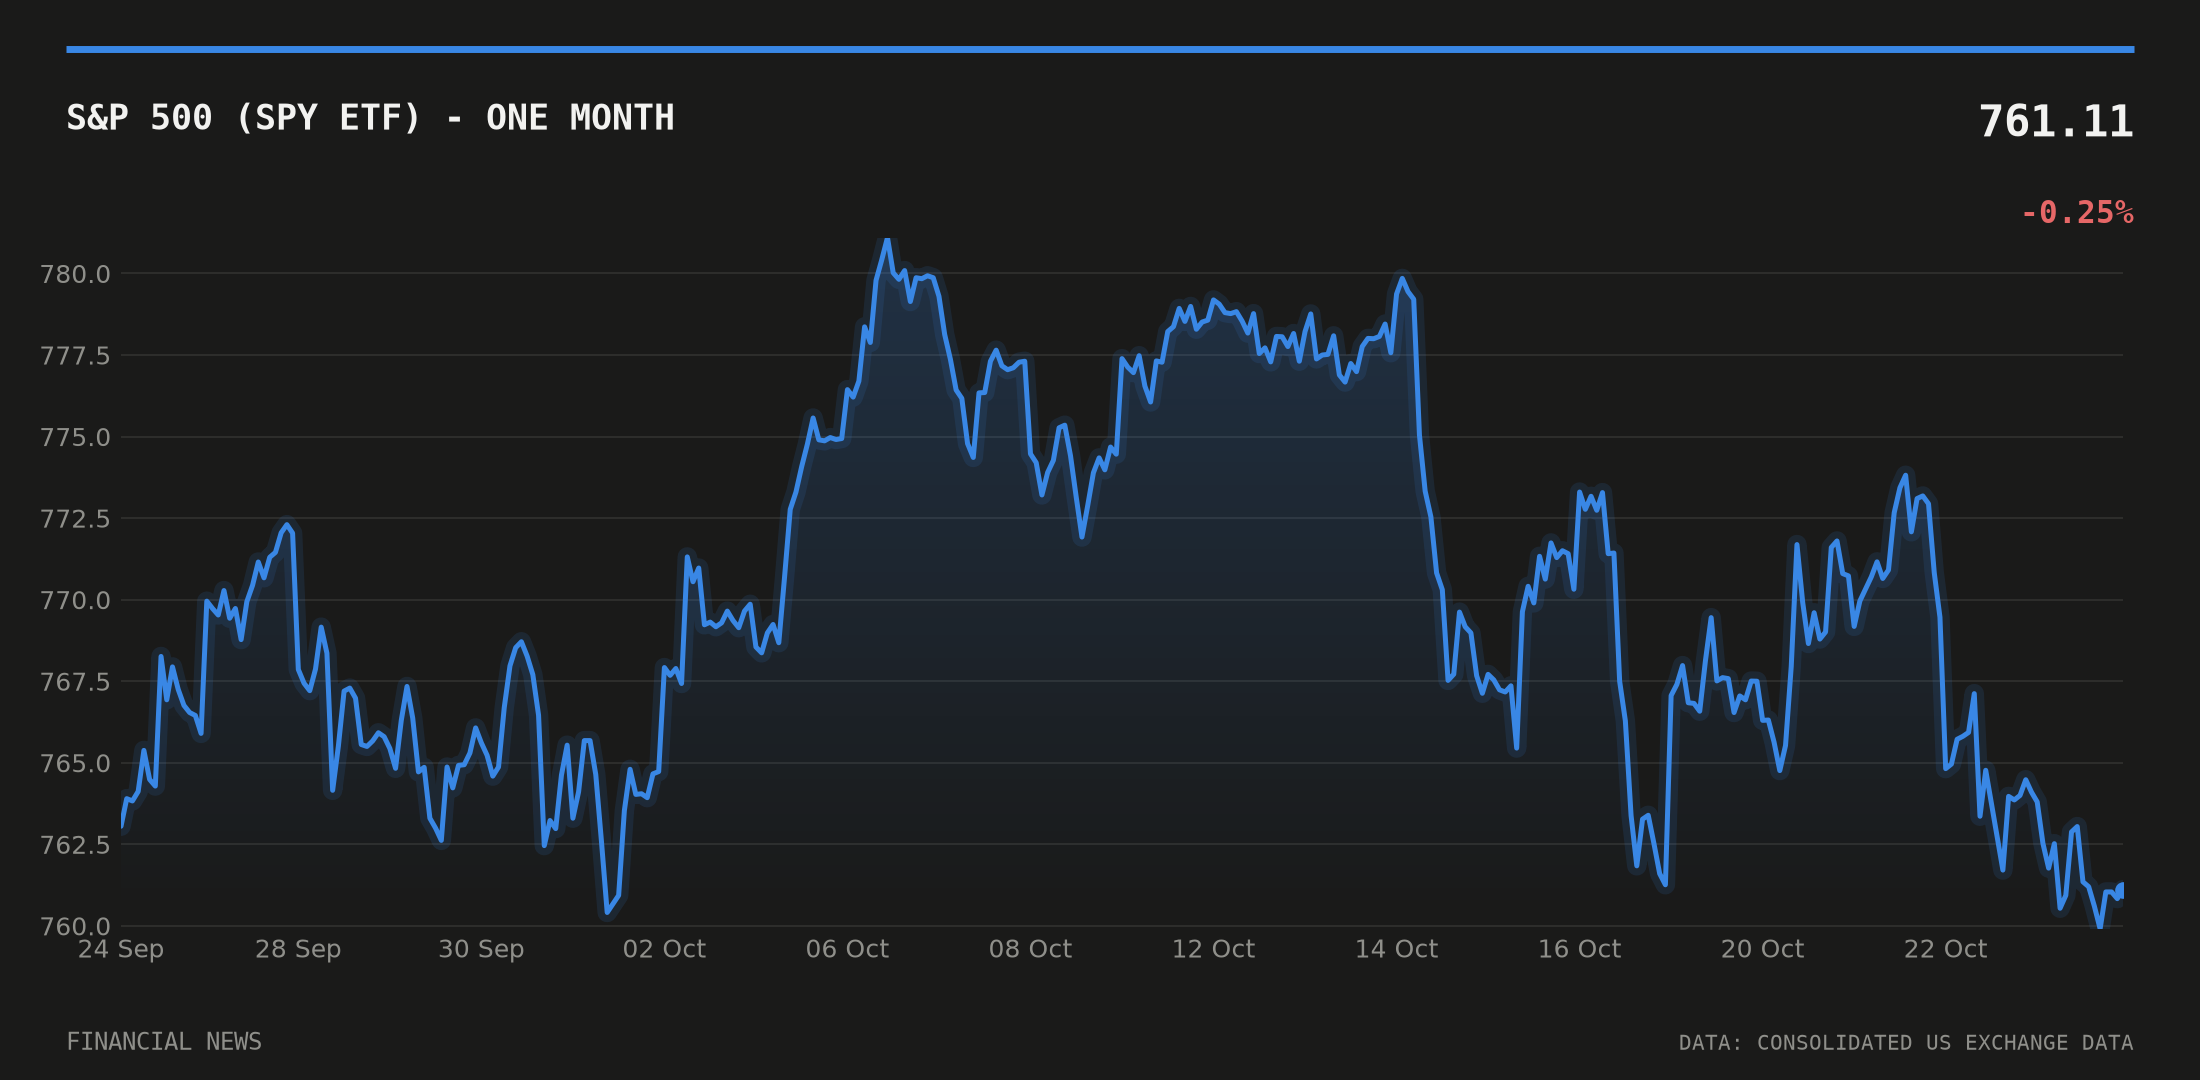
Wall Street’s weekly stock market recap tells a story of divergence rather than direction. The Nasdaq 100 (QQQ ETF) fell 1.72% in the week to 24 October 2026, while the Dow (DIA ETF) added 0.50%. The S&P 500 (SPY ETF) sat between the two, down 0.78% to close at 761.11.
The split marks the week’s defining theme: industrial and defensive names held up even as semiconductor and hardware stocks were marked down hard. It was a week in which the broad index move understated the churn underneath it.
The scoreboard: a stock market this week pulled in two directions
The Nasdaq 100’s 1.72% retreat to 704.88 outpaced the S&P 500’s 0.78% decline, consistent with a week in which chip and hardware names bore the brunt of selling. The Dow, by contrast, closed the week 0.50% higher at 522.05, a reminder that this is a stock market this week more fragmented than the headline indices suggest. With all three benchmarks moving within a percentage point or two of flat, the week registered more as rotation than retreat.
Winners and losers of the week
Five stocks posted double-digit gains. Hasbro (NASDAQ: HAS) led the board, up 19.15% to $117.60. Equifax (NYSE: EFX) climbed 15.89% to $182.52, and Allegion (NYSE: ALLE) rose 15.39% to $178.98. Charles River Laboratories (NYSE: CRL) gained 14.87% to $345.37, while Roper Technologies (NASDAQ: ROP) added 14.53% to close at $437.00.
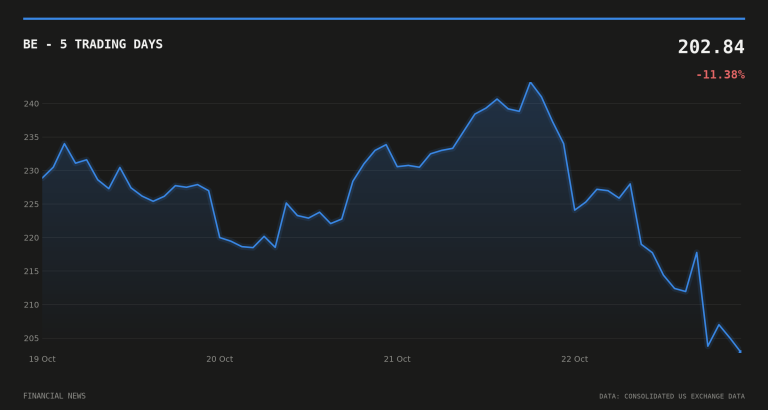
The losers’ list was steeper. Comfort Systems USA (NYSE: FIX) fell 21.41% to $1,160.00, the week’s sharpest move in either direction. Flex (NASDAQ: FLEX) dropped 17.94% to $76.30. Bloom Energy (NYSE: BE) slid 16.49% to $191.15, extending a stretch in which an earnings beat failed to halt the share slide. Lam Research (NASDAQ: LRCX) shed 16.12% to $229.37, part of a broader semiconductor retreat this site tracked in its chip-sector coverage this week. Howmet Aerospace (NYSE: HWM) rounded out the top five fallers, down 15.78% to $187.39.
The insider ledger
No disclosed insider sales of significant size crossed the tape this week among the names tracked for this report. That is itself notable set against a week of sharp single-stock moves: the steepest fallers, Comfort Systems and Flex among them, saw no reported executive selling alongside the declines, nor did the week’s biggest gainers show disclosed buying to accompany the rally. The ledger returns next week.
The macro shift
Treasury yields fell across the curve. The 10-year yield eased to 4.96% as of 22 October, down from 5.13% the prior reading, according to data from the Federal Reserve Bank of St. Louis. The 2-year yield dropped more sharply, to 4.65% from 4.81%, per FRED figures. The 10-year/2-year spread held flat at 0.31, based on the same St. Louis Fed series, meaning the curve’s shape was unchanged even as both ends moved lower together.
Crude oil also retreated. West Texas Intermediate spot fell to $107.89 from $110.01, according to Federal Reserve Bank of St. Louis data. Falling yields alongside falling oil point to a week in which rate expectations and growth expectations moved in the same direction, rather than pulling markets apart.
The number of the week
Comfort Systems’ 21.41% weekly drop to $1,160.00 stands as the sharpest single move of the week, eclipsing even the steepest index swing by a wide margin. Against a backdrop of a Nasdaq down 1.72%, a Dow up 0.50%, and Treasury yields sliding in tandem, single stocks did the heavy lifting this week — the indices themselves barely moved at all.
This article is for information only and is not investment advice or a recommendation to buy or sell any asset. Markets move quickly; figures are correct as sourced at the time of writing. Always do your own research before making financial decisions.