Greenlight Capital Re (NASDAQ: GLRE) reported third-quarter net income of $3.2m on 2 November 2026, as its underwriting margin narrowed from a year earlier.
The Cayman Islands-based reinsurer posted a 90.5% combined ratio for the quarter, up from 86.6% in the same period last year, according to its results filed with the SEC.
Buybacks continue despite margin slip
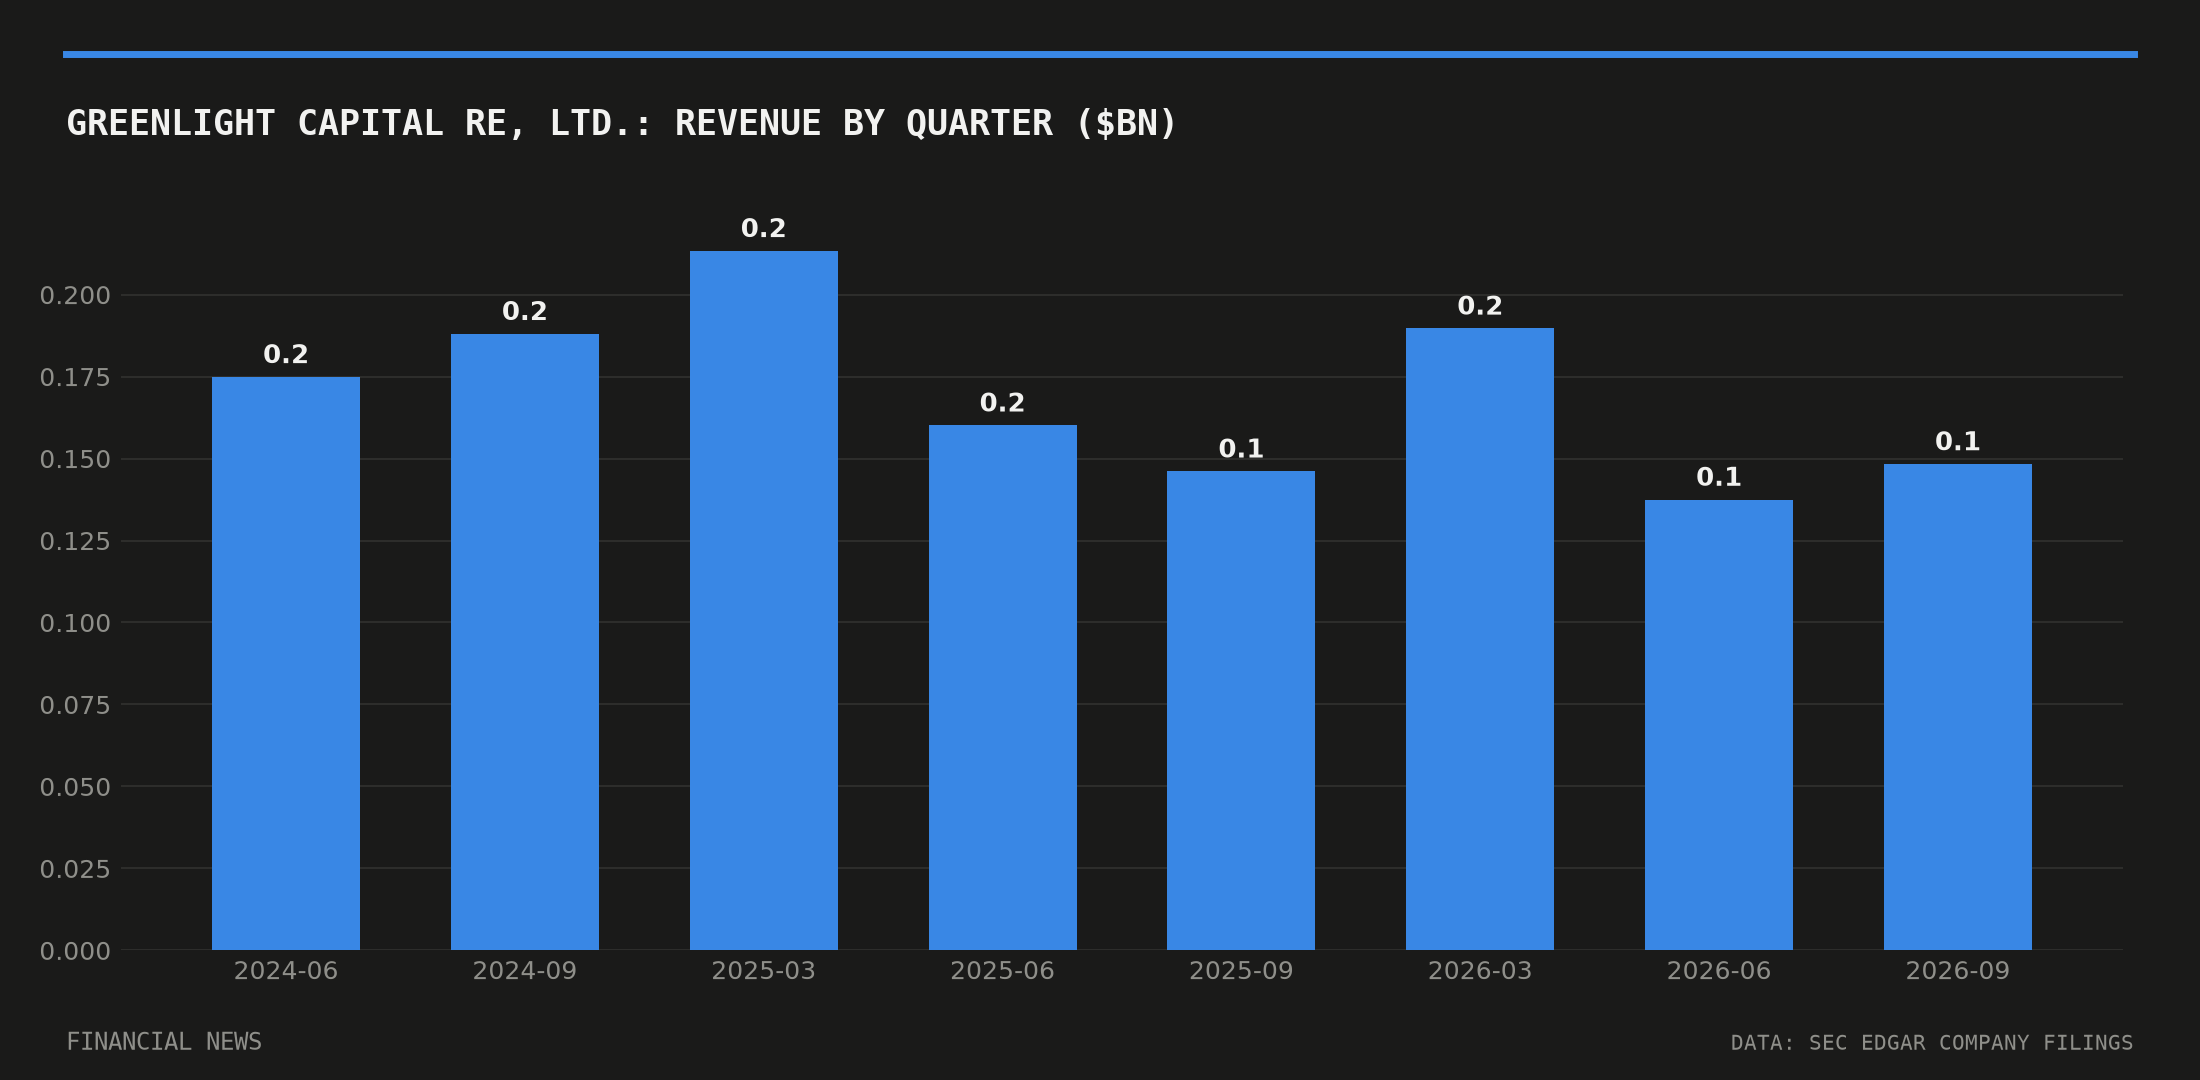
Diluted earnings per share came to $0.10, against a loss of $0.13 a year earlier, the filing shows. Revenues for the quarter were $148.3m, roughly flat on the $146.1m booked in the third quarter of 2025.
Gross premiums written fell 1% to $181.9m, while net premiums earned dropped 7% to $153.4m, the company said in its earnings release.
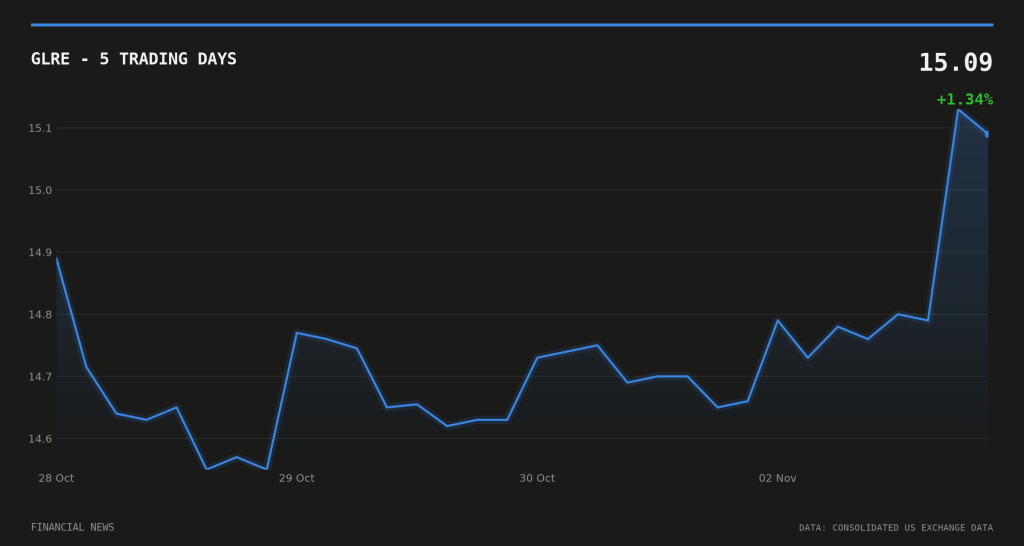
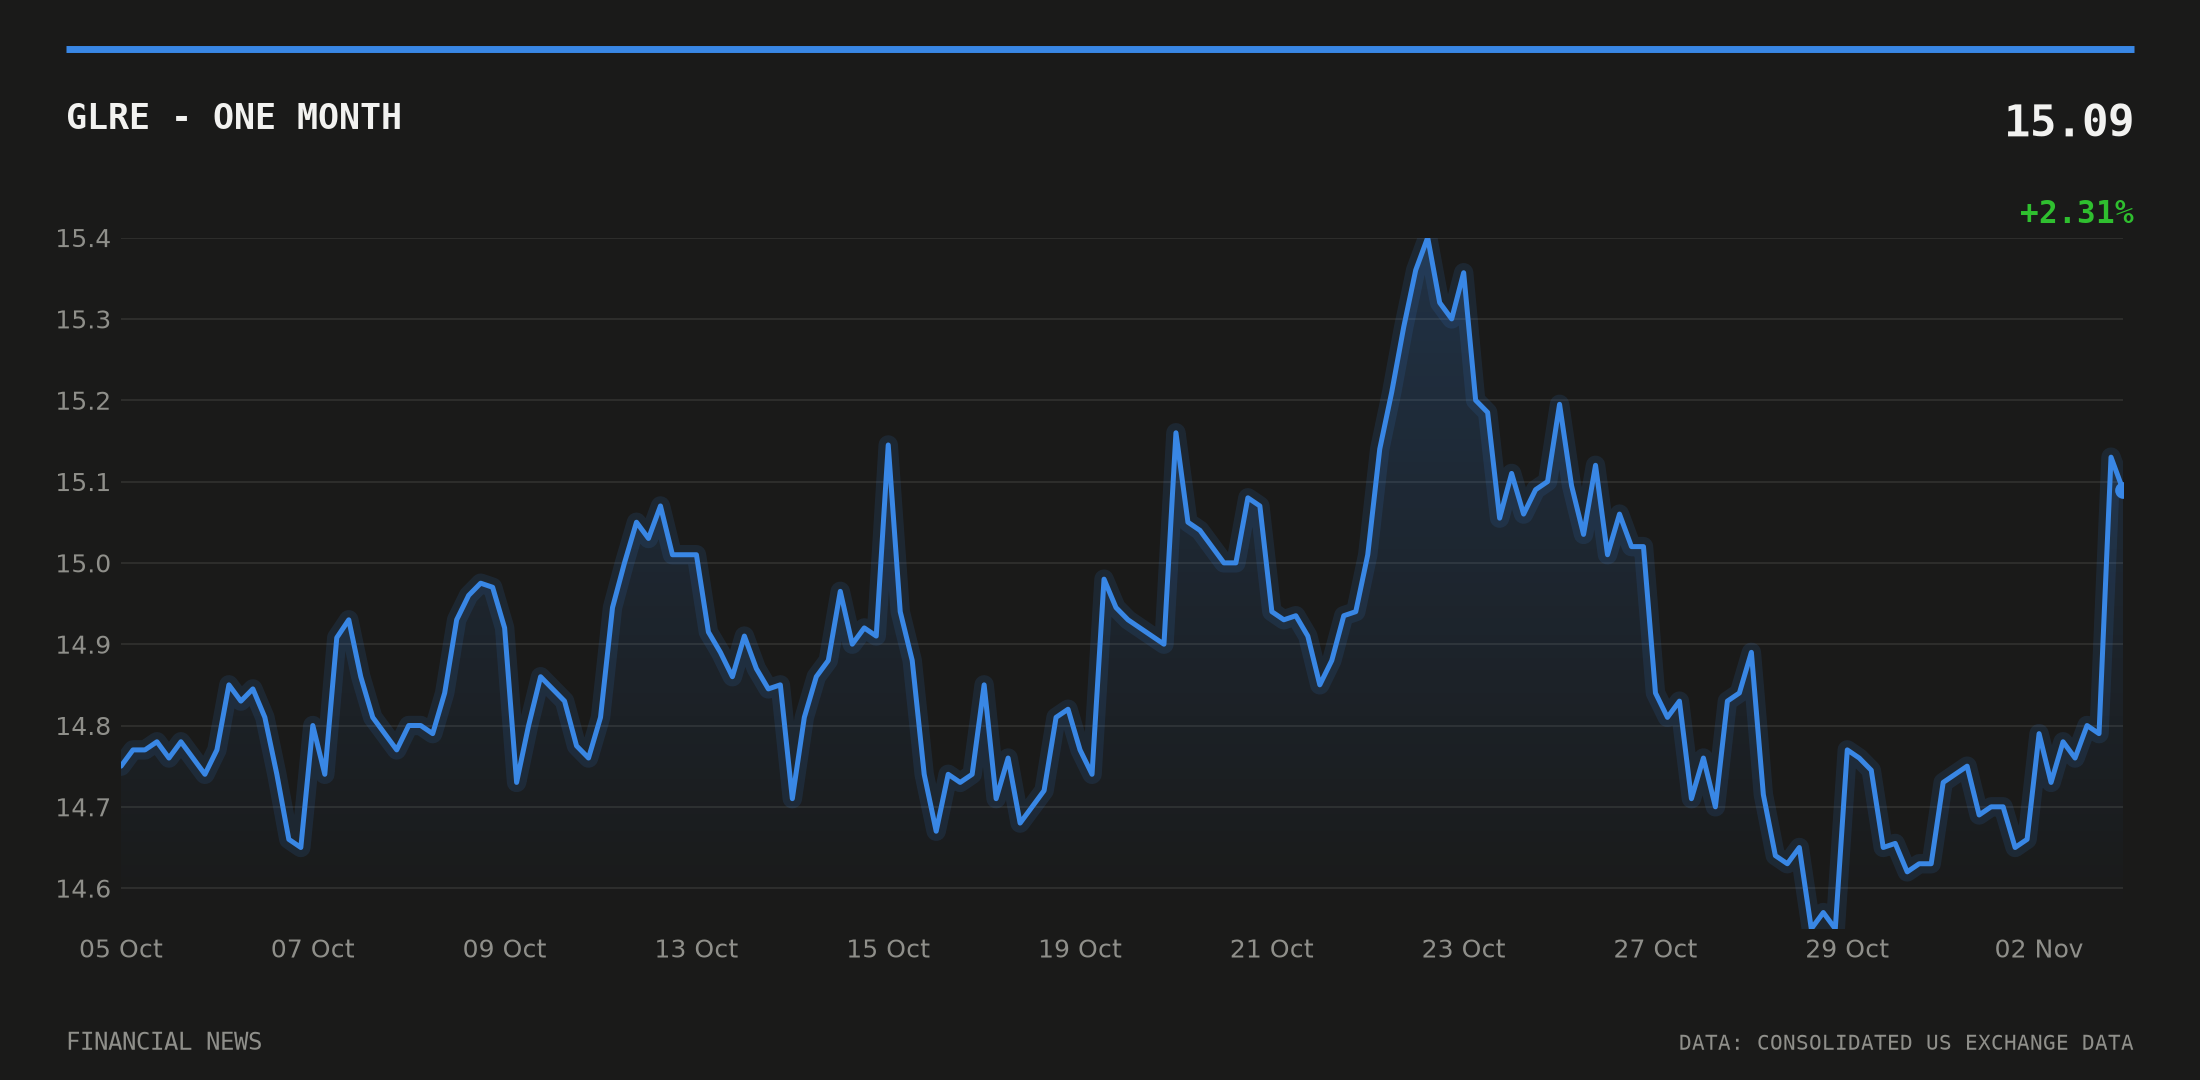
Greenlight Re repurchased $8.0m of ordinary shares during the quarter at an average price of $15.77 each, the filing shows. Shares last traded at $15.09, up 2.03% on the day of the release, putting the average buyback price above the market’s valuation of the stock.
Book value still climbing
Fully diluted book value per share rose 0.8% to $20.78 at quarter-end, from $20.61 at 30 June 2026, the company disclosed. That gap between book value and share price underpins management’s rationale for buying back stock even as the underwriting result softened.
The nine-month combined ratio for 2026 stood at 95.6%, marginally worse than the 95.4% recorded over the same period in 2025, according to the company’s investor presentation. That figure tempers the cleaner single-quarter comparison: on a year-to-date view, underwriting performance has barely moved.
Quarterly results at Greenlight Re have swung sharply over the past two years. Net income reached $35.2m in the third quarter of 2024 before falling to a loss of $4.4m a year later, filings show. The first quarter of 2026 produced net income of $35.75m on revenues of $189.7m, only for the second quarter to swing to a loss of $29.6m. Revenues in that quarter fell to $137.5m, the lowest of the eight periods on record in the company’s recent filings, before recovering to $148.3m in the third quarter. The pattern underlines how volatile the reinsurer’s underwriting and investment results have been even as book value per share has continued to grind higher.
A separate Form 4 filed by the company on the same day as its earnings release did not disclose the underlying share or owner detail on its index page, according to SEC EDGAR.
Positioning and macro backdrop
Short-sale activity in GLRE stayed subdued through the run-up to results. FINRA’s daily short-sale volume ratio for the stock ranged between 0.235 and 0.633 over the ten sessions to 2 November, with no spike around the earnings date, according to FINRA data. That suggests limited bearish positioning ahead of the release.
The results landed against a backdrop of gently easing US Treasury yields, with the 10-year note at 4.94% on 30 October, down from 4.98% the prior reading, and the 2-year at 4.56%, according to data from the Federal Reserve Bank of St. Louis. The 10-year/2-year spread narrowed to 0.32 percentage points by 2 November from 0.38 previously, a flattening that can weigh on reinsurers’ investment income from fixed-income portfolios.
Independent write-ups of the results, including from GuruFocus, corroborated the $3.2m net income and $153.4m revenue figures the same day the filing went live.
Investors will next look to Greenlight Re’s fourth-quarter catastrophe loss experience and any further buyback activity disclosed in subsequent Form 4 filings, which would show whether management kept purchasing shares below book value into the final months of 2026.
This article is for information only and is not investment advice or a recommendation to buy or sell any asset. Markets move quickly; figures are correct as sourced at the time of writing. Always do your own research before making financial decisions.