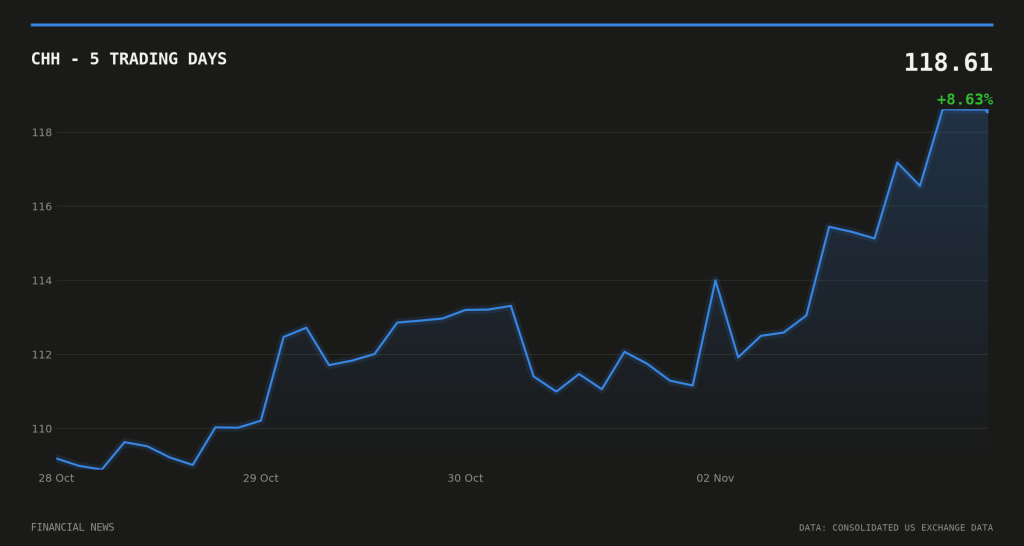
Choice Hotels International (NYSE: CHH) raised its full-year 2026 RevPAR outlook on 2 November, even as third-quarter net income fell 68% year-on-year.
Net income for the quarter ended 30 September came to $58m, or $1.28 a diluted share, down from $180m and $3.86 a share a year earlier, according to the company’s quarterly filing with the SEC.
RevPAR outlook up, profit guidance down
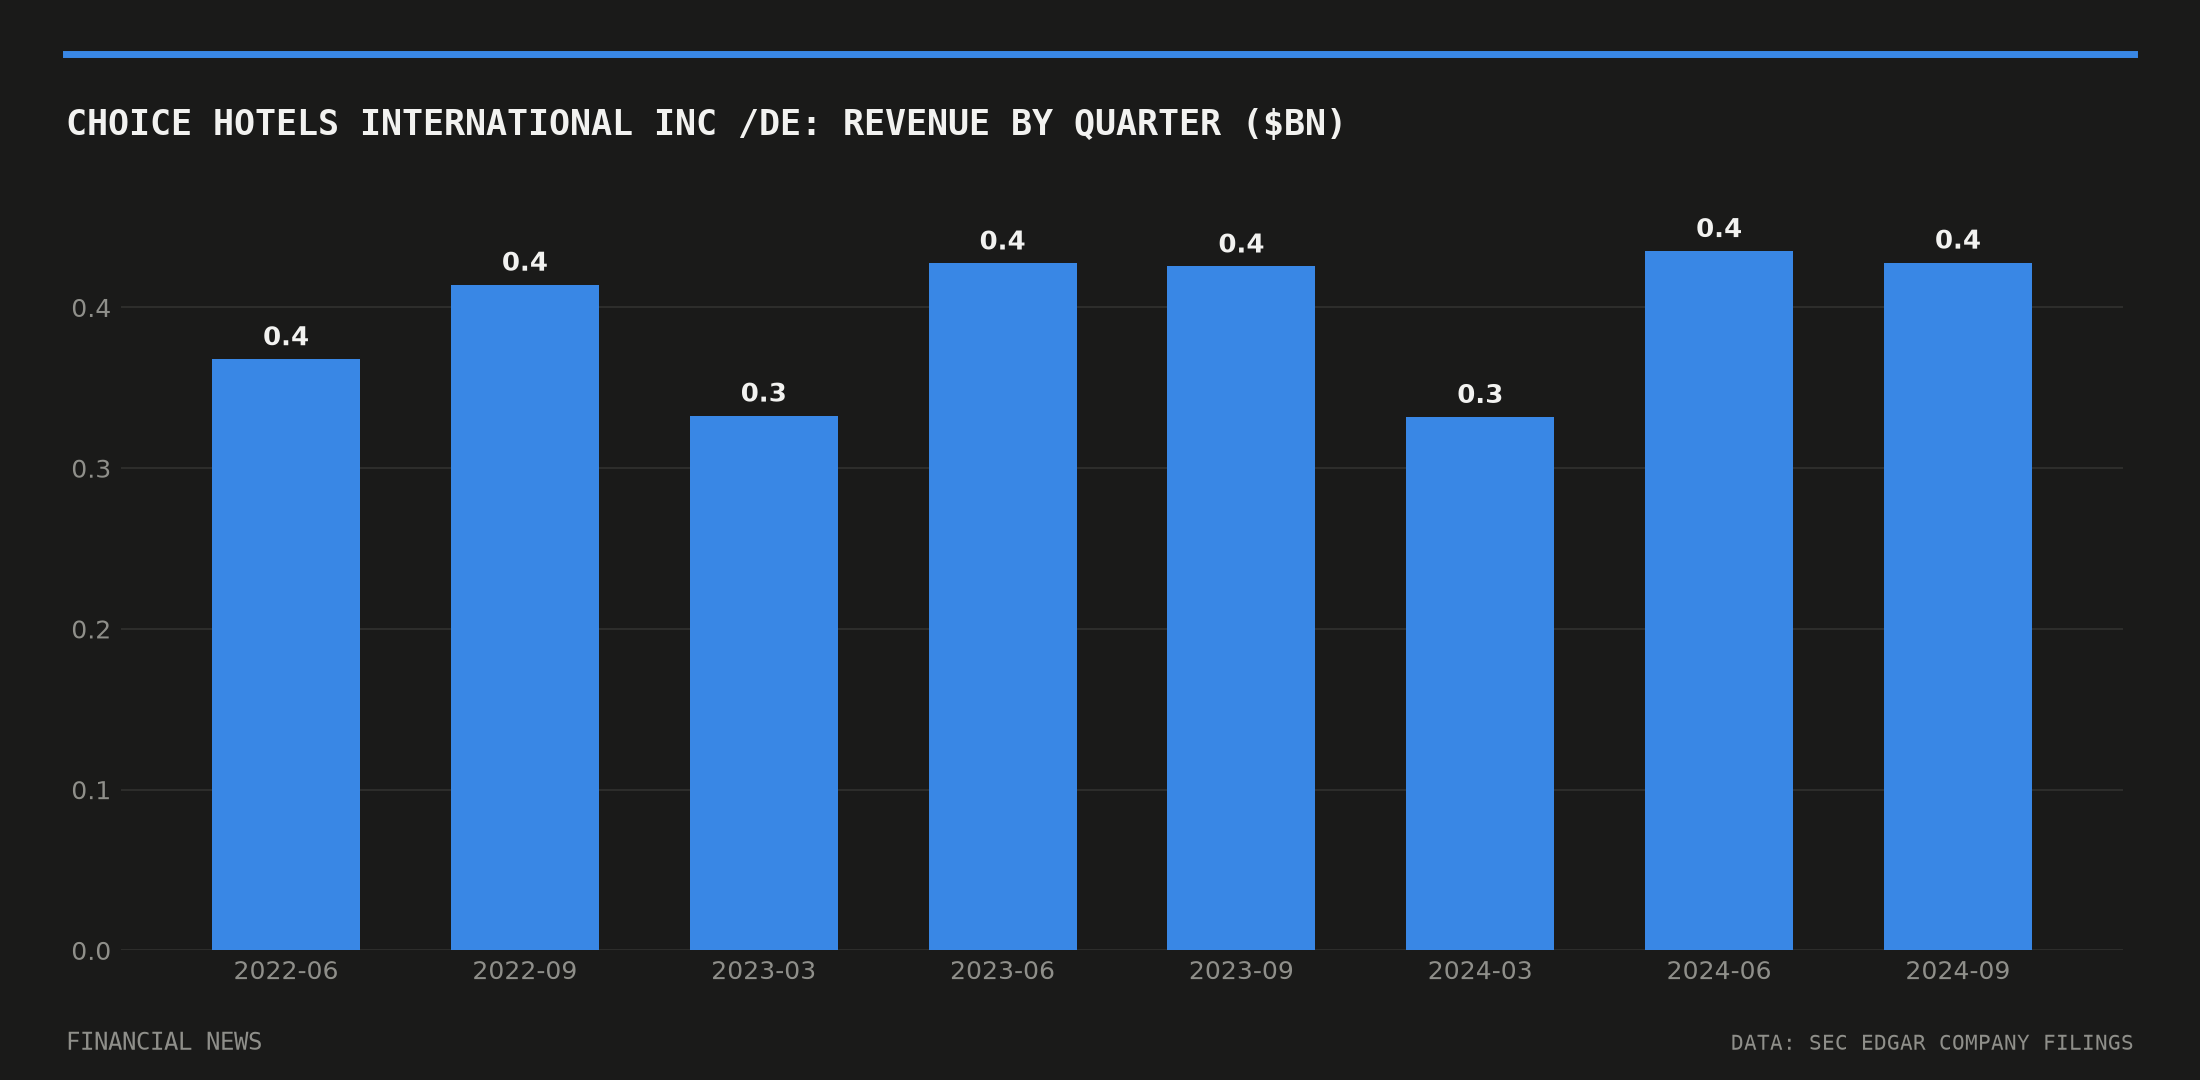
Choice told investors its third-quarter results showed US RevPAR up 3.8% versus the same period last year, driven by a 1.0% rate increase and a 160 basis-point gain in occupancy, according to LODGING Magazine. Adjusted EBITDA rose 1% to $193m, and adjusted diluted earnings per share of $2.33 beat the consensus estimate of $2.28, Investing.com reported.
On the back of that, Choice raised its full-year 2026 RevPAR and adjusted EBITDA guidance, as TradingView News first reported. The same guidance update, though, lowered the company’s full-year net income forecast.
The gap between the two moves is the one-time items sitting in this year’s and last year’s numbers. Q3 2025’s $180m net income figure was inflated by a $100m gain tied to a joint-venture acquisition; this year’s quarter carried a $24m contract-termination charge and a $6m impairment. Strip those out and the underlying earnings picture looks far closer than the headline 68% decline suggests, though the company’s own guidance cut on net income signals the drag is not purely a one-off comparison effect.
Rooms growth and asset-light sales
Choice’s press release leaned on two other data points: a third consecutive quarter of improving US net rooms growth, and owned-hotel sales that it says reinforce its asset-light strategy. Both check out. US room exits fell 23% in the quarter versus a year earlier, a figure disclosed in the company’s SEC exhibit, which helped keep the domestic rooms count roughly flat year-on-year. Subsequent to quarter-end, Choice completed the sale of two owned hotels for roughly $34m in net cash proceeds while retaining the franchise agreements on both properties, a deal reported by franchising.com that fits the pattern of recycling owned real estate into franchise fee income.
Net capital outlays for hotel development and lending activities fell 56% to $36.3m for the nine months to 30 September, down from $82.0m a year earlier, underlining the shift away from direct property ownership.
Shares extend a sharp run
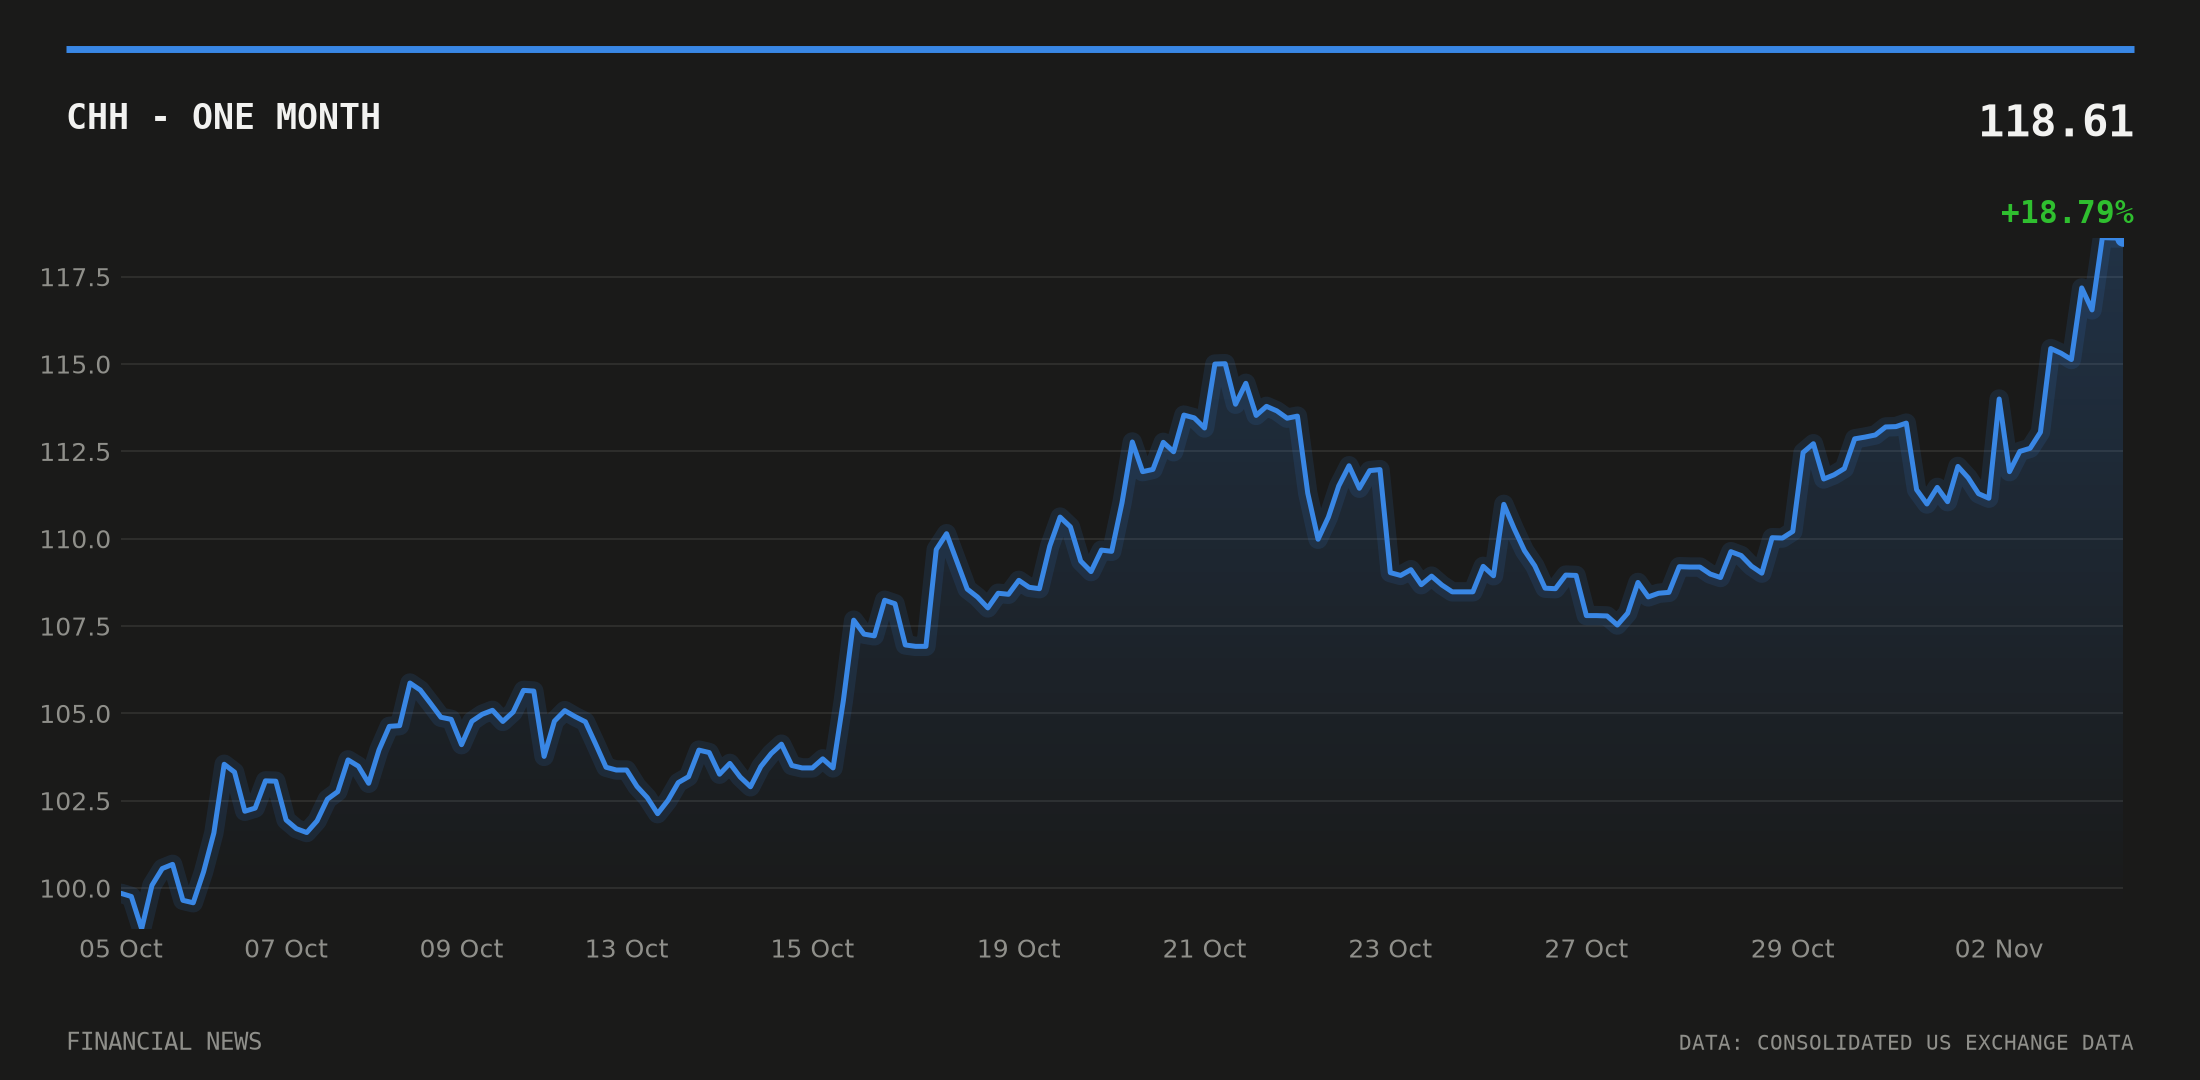
CHH shares closed at $118.61, up 2.74% on the day and 14.73% over the prior 20 trading sessions, with volume running at 2.34 times the 20-day average. The stock had jumped as much as 4.5% in premarket trading on the results before settling into the day’s close. FINRA’s daily short-sale data showed the stock’s short-sale ratio ranging between 0.378 and 0.598 across the fortnight around the results, well short of levels typically associated with a short squeeze, suggesting the move reflected buying rather than short-covering.
Choice also highlighted its extended-stay brands, which notched their 600th hotel opening during the quarter as part of what the company says is 13 consecutive quarters of double-digit net rooms growth in that segment. Management is leaning on that figure as a growth narrative heading into 2026.
Capital returns continue
The company returned $211m to shareholders through dividends and buybacks in the first nine months of 2026 and guided to roughly $200m of share repurchases for the full year, according to a transcript of the earnings call. That pace of capital return sits alongside the softer earnings guidance, a combination that leaves investors weighing improving top-line metrics against a profit outlook that has moved in the opposite direction.
The backdrop for lodging stocks remains mixed: the 10-year Treasury yield eased to 4.94% on 30 October from 4.98% previously, while the unemployment rate ticked up to 4.2% in September, according to Federal Reserve data. Softer rates can support travel demand, but a rising jobless rate is typically a headwind for discretionary spending, a tension that will feature in how the market reads Choice’s next earnings update.
This article is for information only and is not investment advice or a recommendation to buy or sell any asset. Markets move quickly; figures are correct as sourced at the time of writing. Always do your own research before making financial decisions.