Windward Bio Group AG (Nasdaq: WWB) said on 16 November 2026 that it has closed its initial public offering and a concurrent private placement, raising gross proceeds of approximately $251.2 million.
The Basel-based company sold 11,838,234 common shares at $17.00 apiece, a total that includes full exercise of the underwriters’ option to buy 1,544,117 additional shares, according to the company’s release.
Sanofi takes a direct stake
The headline figure folds together two separate transactions. The public offering alone raised roughly $201.25m. The remainder came from a concurrent private placement to Sanofi Foreign Participations B.V., which bought $50.0m of securities comprising 1,532,691 common shares and pre-funded warrants for a further 1,408,485 shares, Investing.com reported.
That structure matters. A pharmaceutical partner writing a $50m cheque alongside a biotech IPO signals direct conviction in the underlying science, distinct from ordinary institutional demand for the stock.
Windward’s shares began trading on the Nasdaq Global Select Market under “WWB” on 13 November 2026, according to the company’s investor relations site. Windward develops ultra-long-acting antibody medicines for respiratory and dermatologic disease, with proceeds earmarked for trials of its lead candidates WIN378 and WIN027, according to the company’s 424B4 prospectus filed with the SEC.
Pricing tracked the marketed range
The deal priced at the midpoint of its original $16-$18 range. Windward had initially marketed 10,294,117 shares at $17.00, targeting roughly $174.93m before the underwriters exercised their option in full, according to IPOScoop.com. The additional 1,544,117 shares lifted IPO proceeds alone to approximately $201.25m, before the Sanofi placement is added.
Windward’s pre-closing F-1/A registration statement filed with the SEC had estimated net proceeds of $203.8m, rising to $228.0m with the option exercised in full, assuming the $17.00 price. Those figures are net of underwriting discounts, so they sit below the final $251.2m gross headline, but the structure matches what was marketed to investors ahead of pricing. Jefferies, TD Cowen, Piper Sandler and UBS Investment Bank served as joint book-running managers on the offering, Investing.com reported.
Form 4s and short interest show no red flags
A cluster of Form 4 filings landed with the SEC on 16 November, including disclosures from officers Claudia D’Augusta, Luca Santarelli, Kevin Andrew Harris and Mufti Iqbal Rasool, alongside multiple issuer filings. These are consistent with standard post-IPO equity reporting rather than insider selling that would undercut the raise, based on the filings lodged with EDGAR.
Short interest in the stock has stayed modest since the debut. FINRA data put WWB’s daily short-sale volume ratio at 0.61 on 13 November, the day trading opened, easing to 0.591 by 16 November when the closing was announced, according to FINRA’s daily short sale volume data. Neither reading points to the kind of spike that typically accompanies aggressive bearish positioning around a newly listed stock.
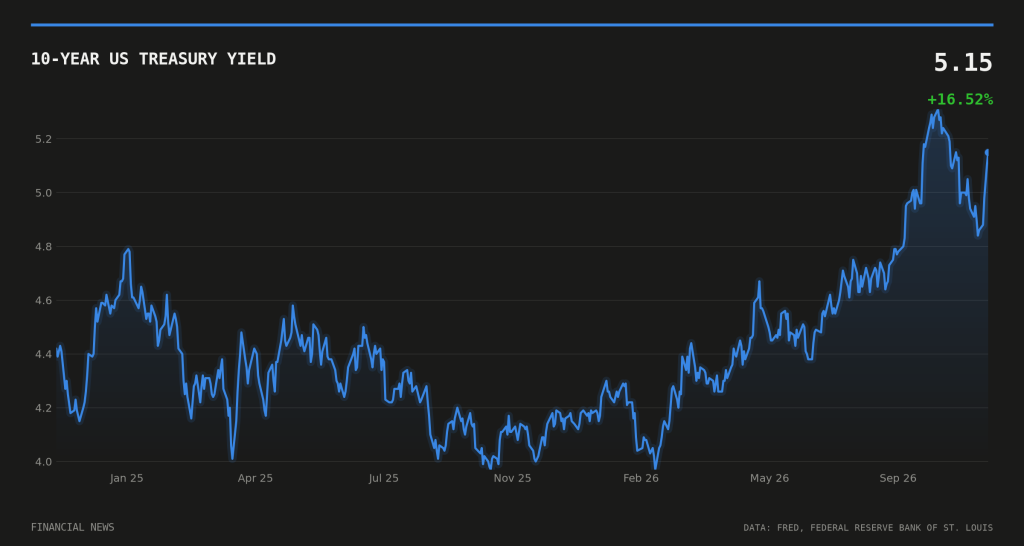
The listing also arrived into a higher-rate backdrop than biotech issuers have faced for much of the past decade. The 10-year US Treasury yield stood at 5.15% on 13 November, up from 5.10% the prior session, while the 2-year yield held at 4.88%, according to FRED data from the Federal Reserve Bank of St. Louis. The 10y-2y spread widened slightly to 0.29 percentage points from 0.27, separate FRED series show, a modestly steepening curve that has coincided with a string of clinical-stage biotech listings testing investor appetite despite elevated borrowing costs. US unemployment eased to 4.1% in October from 4.2% the month before, while headline CPI ticked up to 337.476 from 336.298 on the same FRED measure, a backdrop analysts watching the IPO window have described as neither clearly supportive nor hostile to risk appetite for early-stage drug developers.
Windward’s offering becomes a reference point for other clinical-stage biotechs weighing Nasdaq listings into a similar rate environment, particularly where a strategic pharma partner is prepared to anchor part of the round. Investors will watch subsequent Form 4 filings and quarterly disclosures for how Windward deploys the proceeds across its WIN378 and WIN027 programmes.
This article is for information only and is not investment advice or a recommendation to buy or sell any asset. Markets move quickly; figures are correct as sourced at the time of writing. Always do your own research before making financial decisions.