Dole plc (NYSE: DOLE) cut its full-year profit outlook on 9 November 2026, after third-quarter earnings fell well short of analyst estimates.
The fruit and produce group now targets full-year adjusted EBITDA of $380m-$390m, a midpoint of $385m, down from roughly $400m previously, according to its third-quarter earnings release.
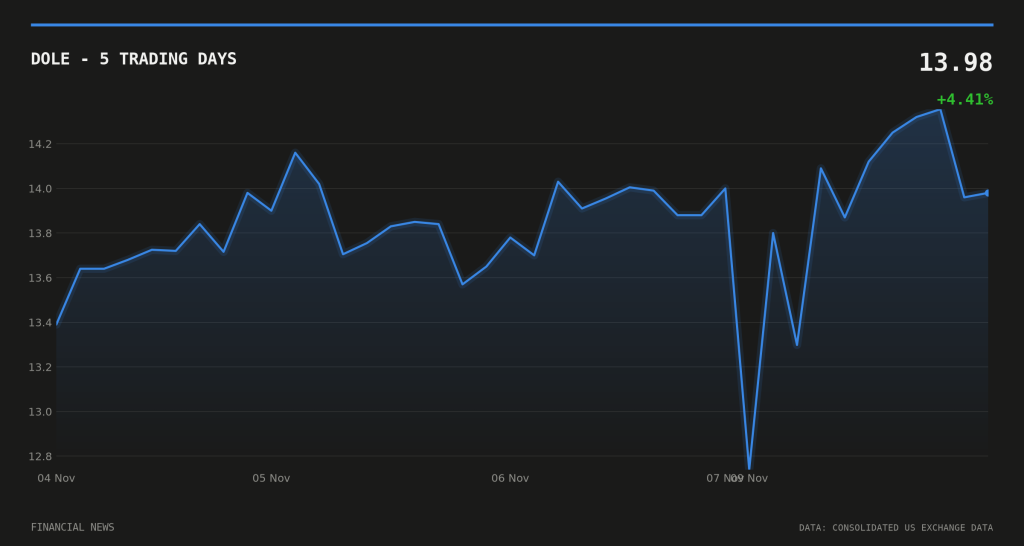
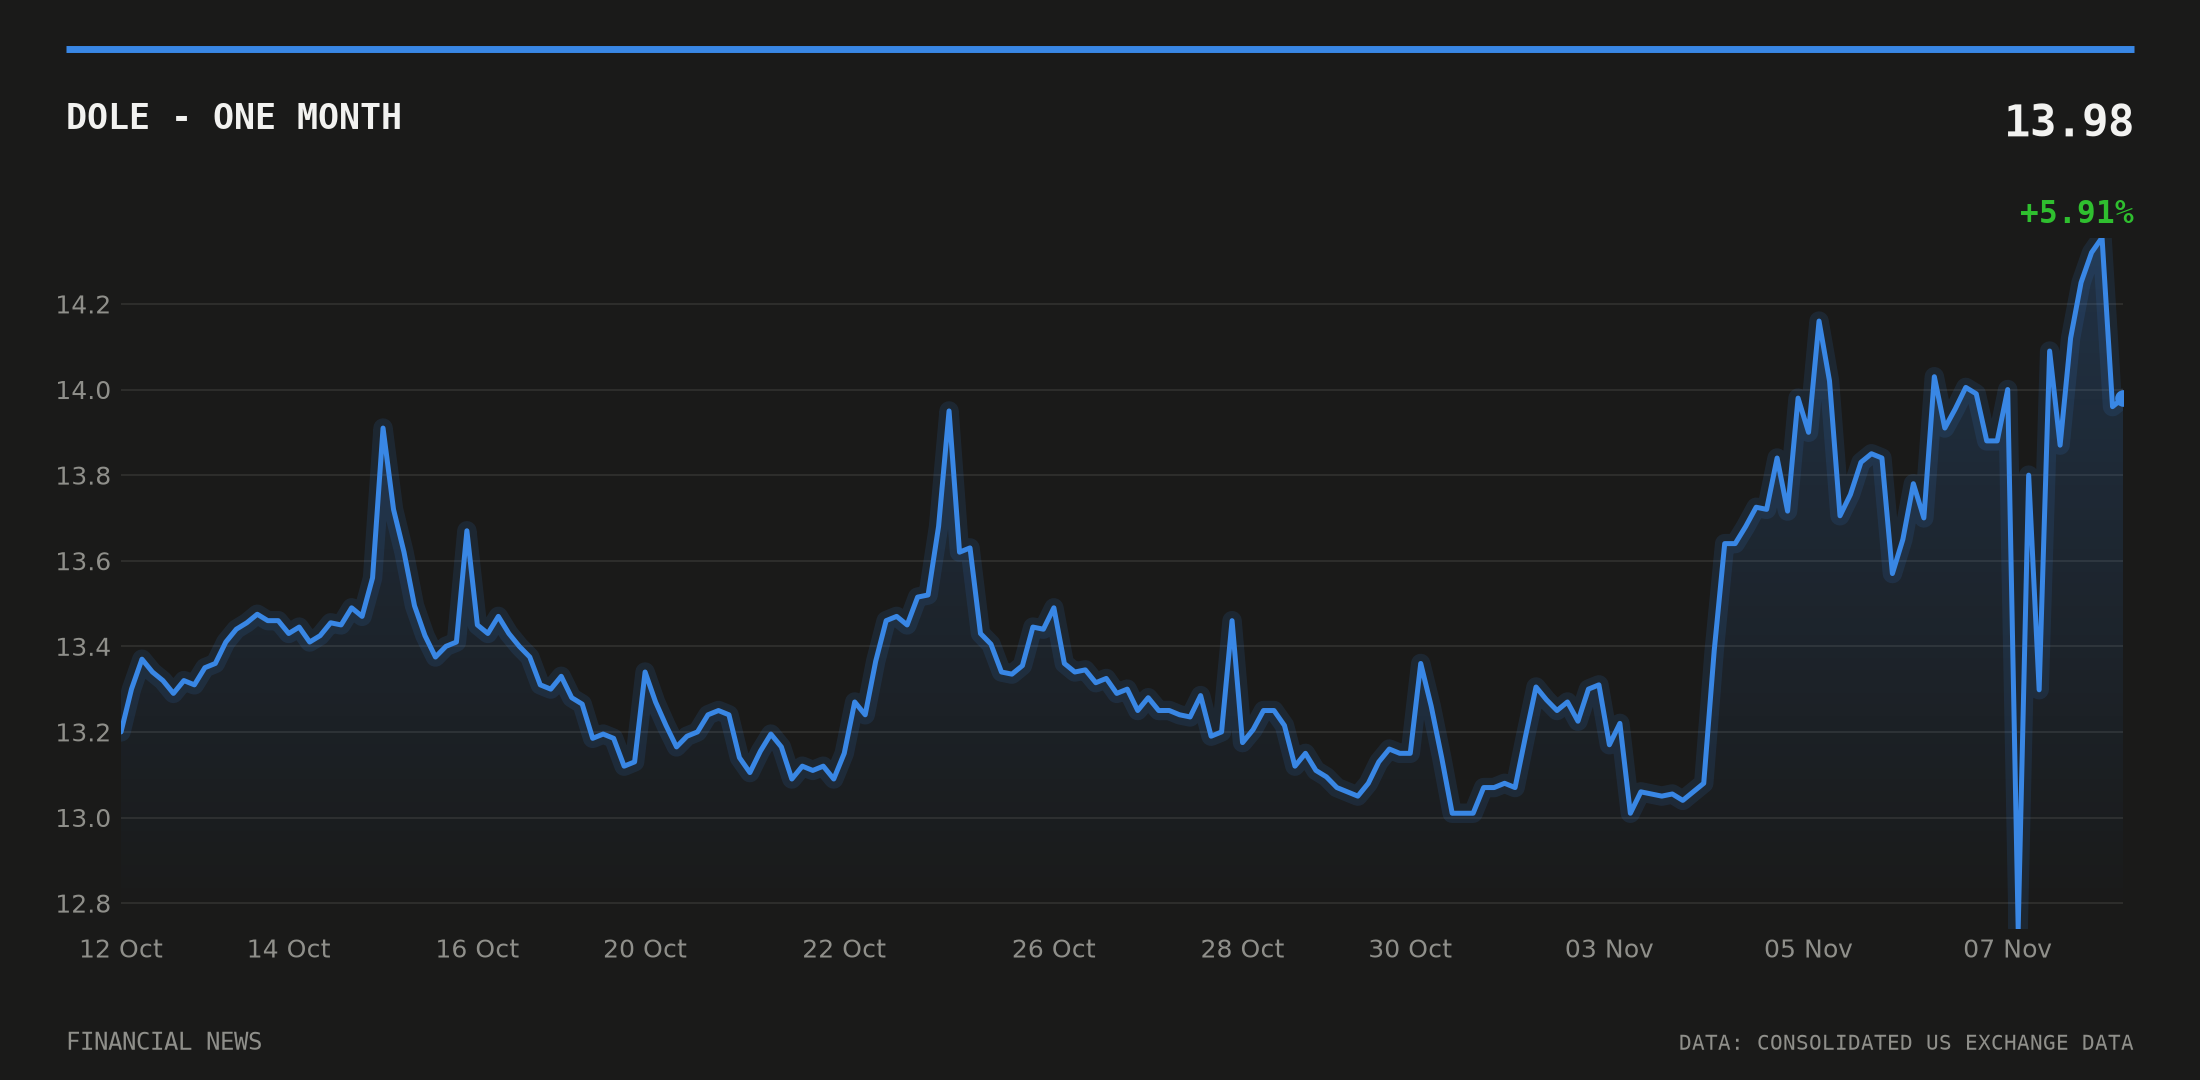
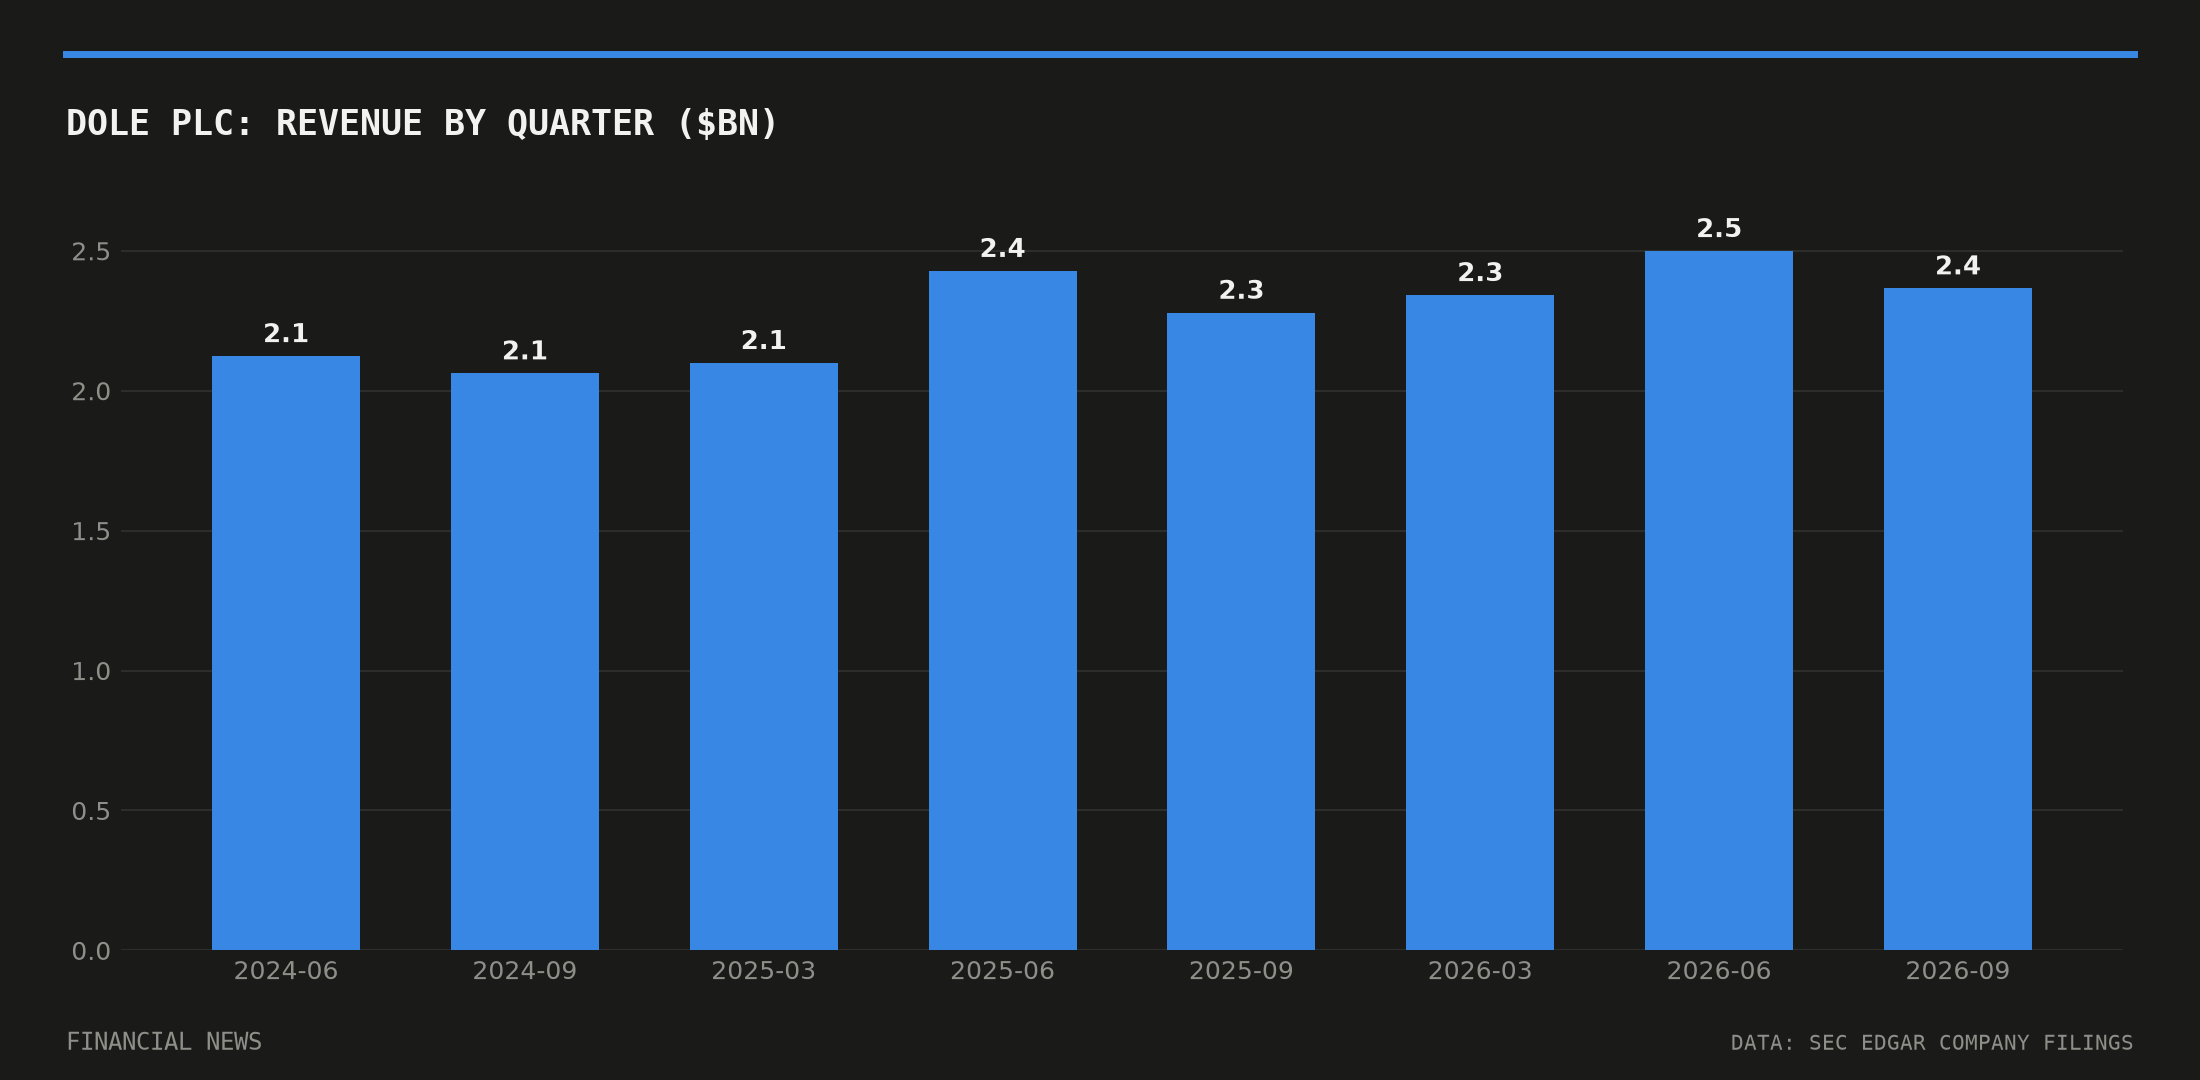
Adjusted diluted earnings per share came in at 16 cents, missing the average analyst estimate of 34 cents, Zacks reported. Quarterly revenue of $2.37bn was roughly in line with forecasts. Shares closed at $13.98, down 0.78% on the day, though still 4.8% higher over the past 20 sessions.
A one-off gain flattered the headline profit figure
Dole reported consolidated net income of $48.3m for the quarter, up $34.5m year on year. Most of that increase came from a single item: a $48.6m net pre-tax gain on the disposal of its Ecuador port operations, disclosed in the company’s third-quarter 10-Q filing.
Strip that out and the underlying picture looks weaker. Net income attributable to Dole plc shareholders – the figure used to calculate per-share results – was $38.5m, giving GAAP diluted earnings per share of 41 cents, per SEC EDGAR filings. On an adjusted basis, stripping out the port gain and other one-offs, diluted EPS was just 16 cents.
The port sale did deliver a balance-sheet benefit: net leverage fell to 1.3x once the deal completed, the company said in its earnings release.
Fresh Fruit volumes under pressure
Revenue in the Fresh Fruit division fell 8.0%, or $71.7m, to $818.7m. Dole attributed the decline to lower banana volumes in North America and lower pineapple volumes in Europe, where adverse weather hit fruit availability, according to the 10-Q.
Diversified fresh produce segments moved in the opposite direction, but not for the same reason everywhere. EMEA revenue rose 9.3% to roughly $1.1bn, helped by the Greenfood Fresh Produce acquisition in Scandinavia, Dole executives said on the earnings call. Americas & ROW revenue climbed 14.1% to $479.2m, but that growth came from higher volumes of kiwi, avocados, grapes and tomatoes rather than from dealmaking, management told analysts on the same call, as transcribed by Seeking Alpha.
Fuel costs, not demand, drove the guidance cut
Management pointed to a specific, quantifiable culprit for the lowered outlook: unhedged European fuel costs, expected to create a $16m full-year headwind, according to a transcript of the call carried by Nasdaq. Elevated shipping expenses and weather-related losses to fruit availability added to the pressure.
That framing matters for how investors read the quarter. Dole’s guidance cut traces to a specific cost line rather than a broad pullback in demand – the Americas & ROW volume growth suggests underlying consumption held up even as fuel and freight ate into margins.
Shares swung sharply around the release
Shares fell as much as 8% in pre-market trading after the results, touching their 20-day low of $12.74, before recovering through the session, Benzinga reported. Trading volume ran at 1.79 times the 20-day average, consistent with a stock reacting to news rather than drifting.
Positioning data from the days before the report hints at some investors pre-positioning for a weak print. FINRA short-sale volume data shows the short ratio for Dole spiking to 0.851 on 3 November and 0.748 on 6 November, then easing to 0.553 on the day results were published – a pattern consistent with short-covering, or profit-taking, once the numbers were out.
Dole’s next scheduled update is the fourth-quarter report, when the market will find out whether the $385m EBITDA midpoint holds or needs revisiting again.
This article is for information only and is not investment advice or a recommendation to buy or sell any asset. Markets move quickly; figures are correct as sourced at the time of writing. Always do your own research before making financial decisions.