KKR & Co Inc (NYSE: KKR) filed its third quarter results on 9 November 2026, posting record fee-related earnings for the second straight quarter. The private equity and credit group’s co-chief executives, Joseph Bae and Scott Nuttall, said the firm had kept monetising investments at pace.
Fee Related Earnings reached $1.3bn in the quarter, up 27% year-on-year, according to KKR’s earnings release filed with the SEC. Adjusted Net Income climbed to roughly $1.65bn from $1.27bn a year earlier, a rise of about 29%, lifting adjusted earnings per share to a record $1.78.
KKR third quarter results beat on fee earnings
The $1.78 adjusted figure came in above Wall Street forecasts clustered around $1.58 to $1.59 a share, as first reported by Qz.com. On a GAAP basis, diluted earnings per share attributable to common stockholders rose to $1.19, from $0.90 in the same quarter last year, the filing showed.
Assets under management grew to $804bn, up 11% year-on-year, according to GuruFocus. That scale underpins the fee base that now drives the bulk of KKR’s recurring earnings, a shift the firm has pushed for several years as it leans away from performance fees tied to deal timing.
‘We continue to monetize investments and return capital to our clients at record levels,’ Bae and Nuttall said in comments carried by Qz.com.
Record capital returns planned for 2026
KKR said it expects to return more than $40bn to clients across 2026, which would exceed its previous annual record by more than 50%, the filing said. The figure reflects a run of exits and realisations across the firm’s private equity, infrastructure and credit funds.
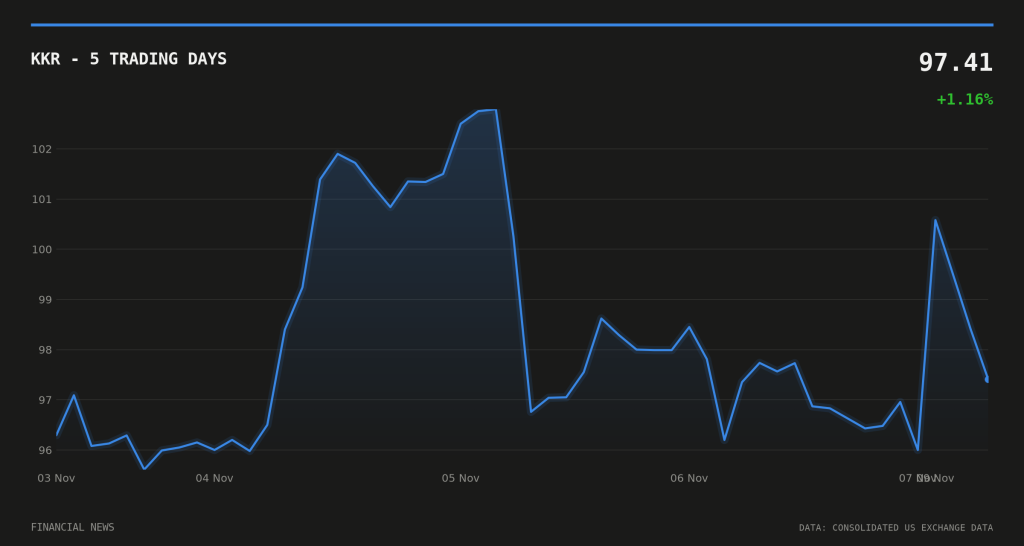
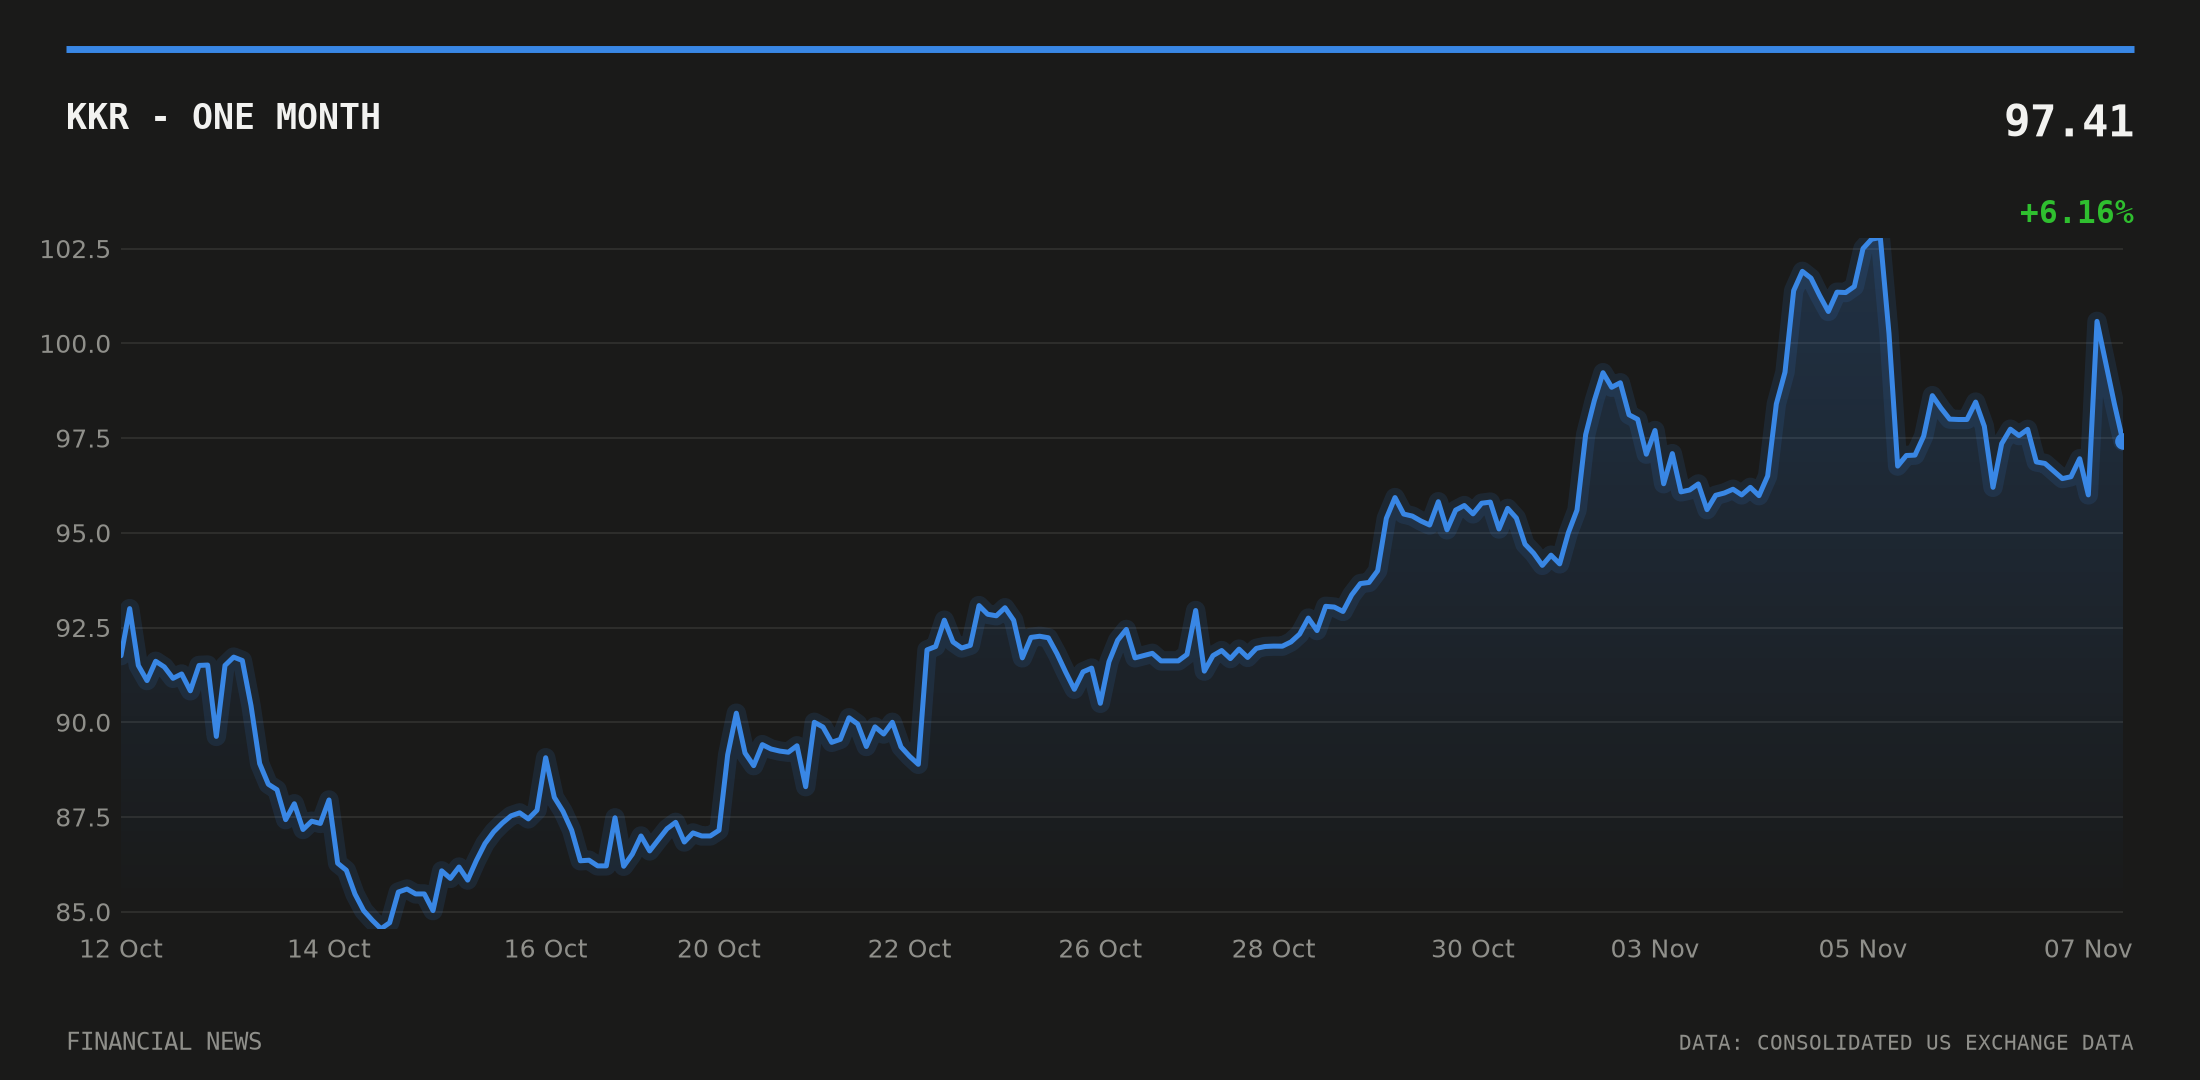
The company has also been buying back its own stock. Between 30 June and 4 November, KKR spent $567m repurchasing 6.2 million shares at an average price of $92, according to the earnings release. That compares with a last traded price of $98.38 as of 9 November, after the shares rose 2.02% on the day and are up 13.21% over the preceding 20 trading days.
Revenue picture splits across data providers
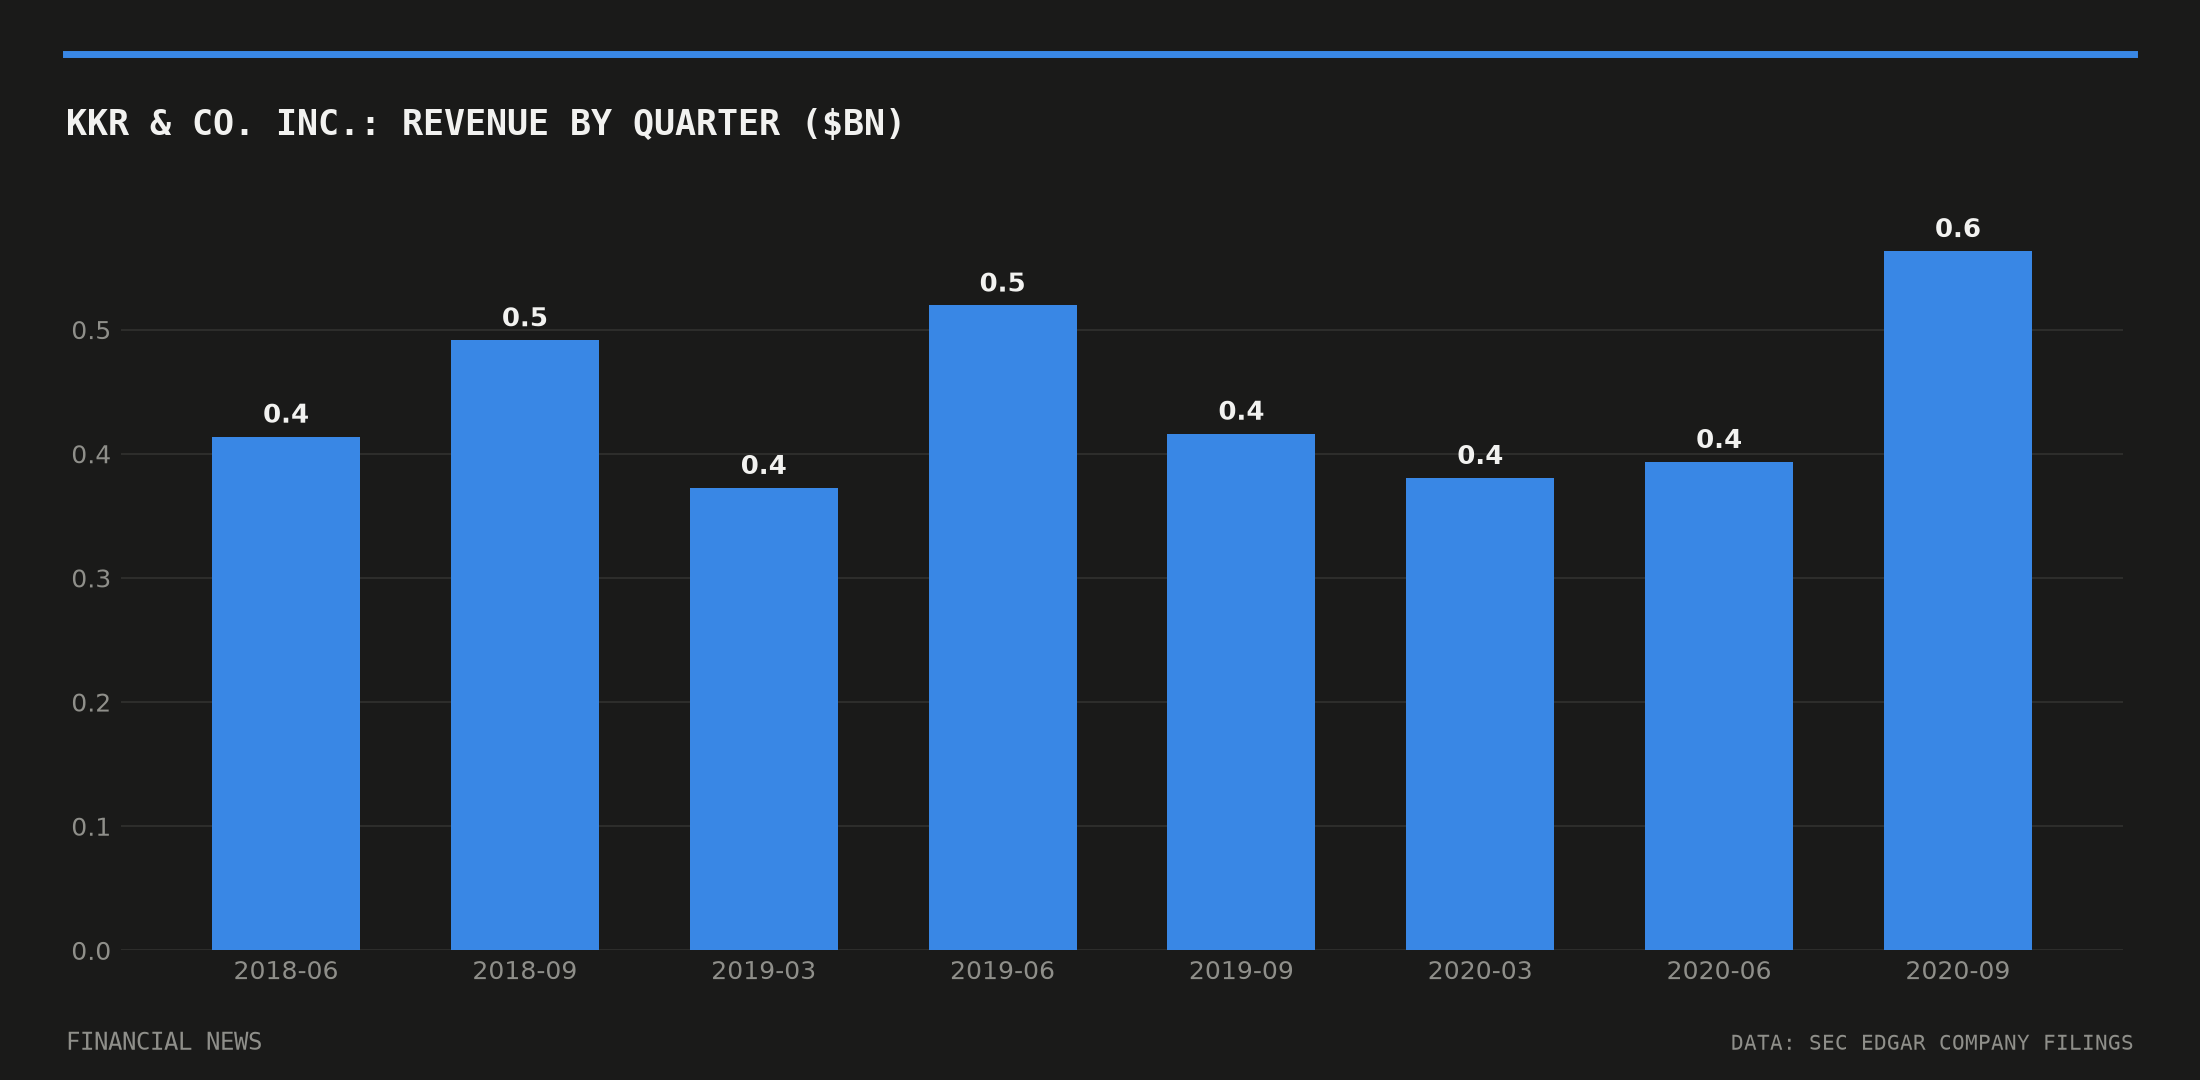
The quarter’s headline revenue number has proved harder to pin down. GuruFocus reported GAAP revenue of $4.56bn that beat expectations, while ChartMill described a revenue miss against consensus of roughly 29%. The discrepancy illustrates a familiar problem with alternative-asset managers’ accounts: headline “revenue” can include or exclude realised performance income, carried interest and consolidated fund-level items depending on which line a data provider selects, making quarter-on-quarter comparisons unreliable without the underlying detail.
What is consistent across providers is the earnings beat and the direction of the stock. ChartMill noted KKR shares were indicated roughly 1.4% higher in premarket trading on results day, even with the contested revenue read, pointing to investors weighting the fee-earnings and capital-return numbers over the top-line figure.
Positioning and the macro backdrop
Short interest in KKR had been easing into the print. FINRA daily short-sale data show the short-sale ratio falling from 0.513 on 26 October to 0.402 on 6 November, pointing to lighter bearish positioning heading into results, according to FINRA figures.
The broader backdrop has turned modestly supportive for fee-driven managers. The 10-year US Treasury yield eased to 4.84% by 5 November from 4.9% a fortnight earlier, while the unemployment rate ticked down to 4.1% in October, according to data from the Federal Reserve Bank of St. Louis. Lower long-end yields tend to ease financing costs across KKR’s credit and infrastructure portfolios, while a steady labour market supports the consumer and corporate activity that feeds deal flow.
KKR’s net income has been volatile across recent quarters, swinging from a loss of $185.9m in the first quarter of 2025 to profits exceeding $900m by that year’s third quarter, filings with the SEC show. The latest fee-earnings growth suggests the firm is trying to smooth that volatility by leaning more heavily on recurring management fees rather than performance-linked income, a trend investors are likely to track again when KKR next reports.
This article is for information only and is not investment advice or a recommendation to buy or sell any asset. Markets move quickly; figures are correct as sourced at the time of writing. Always do your own research before making financial decisions.