Coca-Cola Europacific Partners (CCEP) posted its CCEP Q3 2026 results on 3 November 2026, beating revenue forecasts even as its shares slid on the day.
Revenue came in at €5.764bn, up 6.5% on the same quarter last year, according to the company’s trading update. Volumes rose roughly 3.5% to 1.048bn unit cases, the company said.
A beat that still sent shares lower
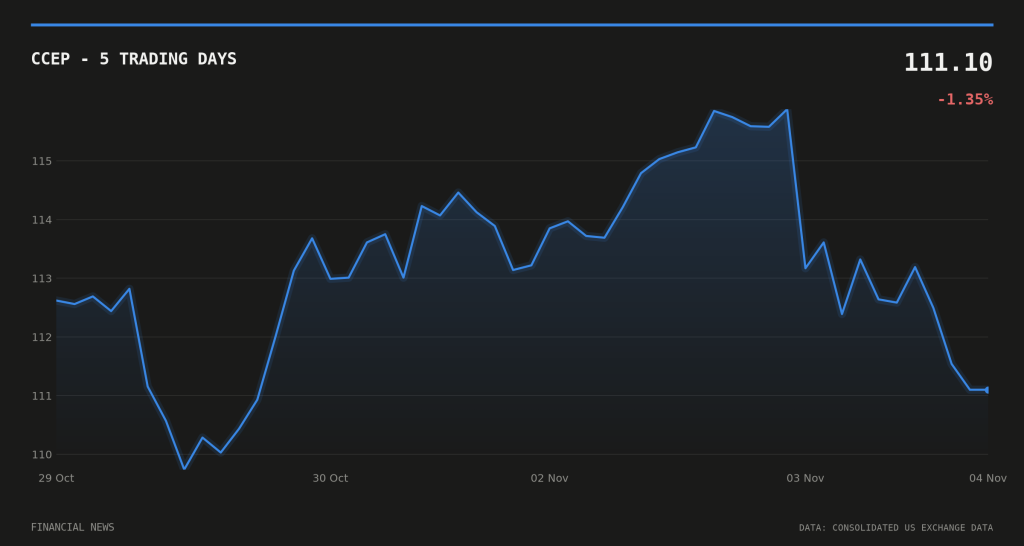
CCEP shares closed at $111.10 on 3 November, down 1.15% on the day, according to consolidated US exchange data, even after the company topped revenue estimates and reaffirmed its full-year outlook.
The move fits a pattern traders call ‘selling the news’: shares fall on an in-line or better print because the market had priced in more. Commentary cited by Investing.com attributed the drop to Jefferies’ view that investors had hoped for an upgrade to guidance rather than a simple reaffirmation. GuruFocus separately clocked a steeper 3.5% fall to $111.56 in its own tracking, against a 52-week range of $84.66 to $116.01 — a reminder that reaction estimates vary by venue and timestamp even when the underlying results are not in dispute.
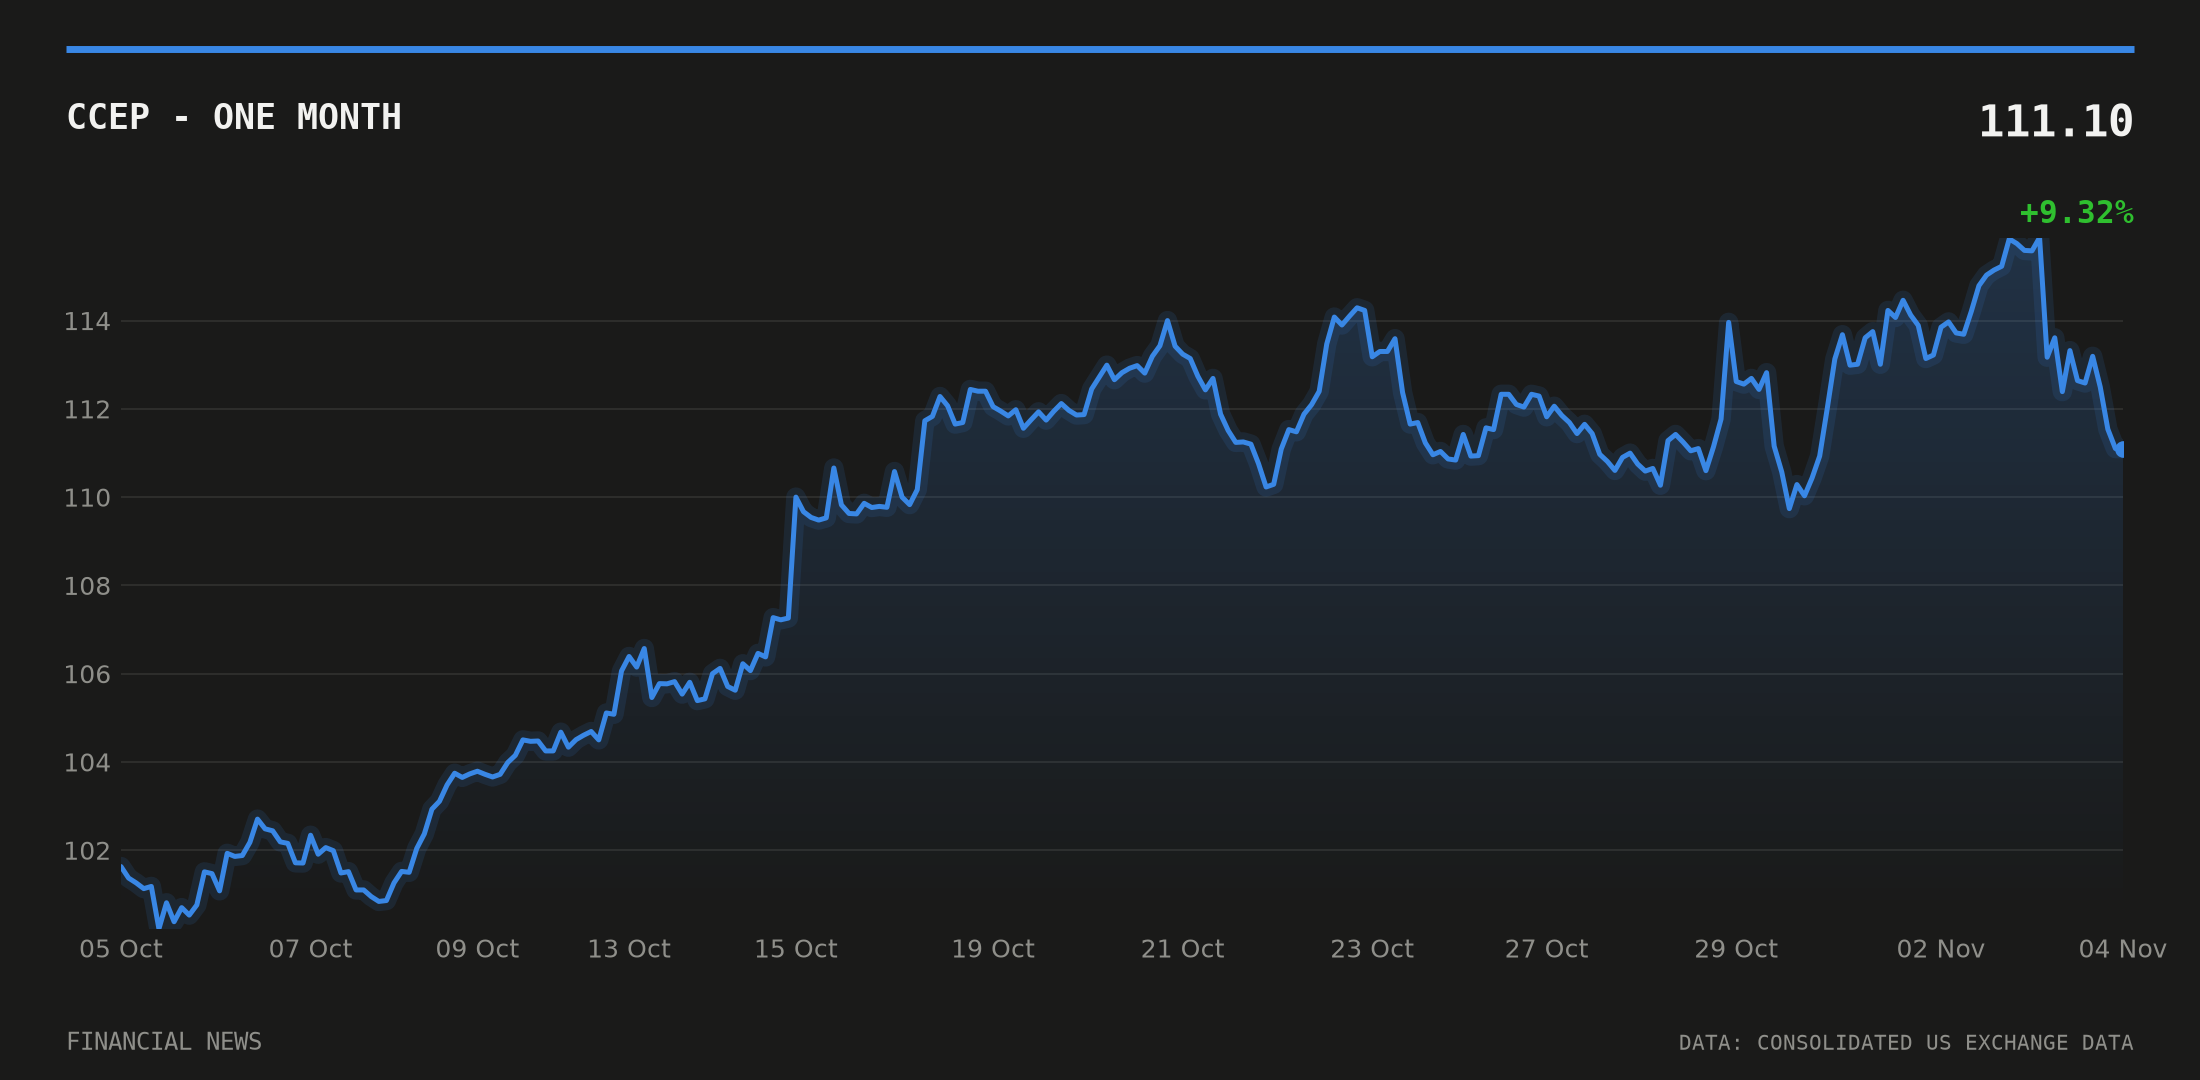
Shares were still up 4.81% over the prior 20 trading days heading into the print, having traded as high as $115.88 in that window, before the post-results pullback. Volume on the day ran 1.87 times the 20-day average, consolidated exchange data show.
Guidance unchanged, dividend confirmed
CCEP left its full-year 2026 guidance untouched: revenue growth of 3-4%, operating profit growth of roughly 7%, comparable free cash flow of at least €1.7bn, and capital expenditure near 5% of revenue, per the company’s RNS filing. Year-to-date revenue stands at €16.488bn, up 5.1% reported.
The board declared a second-half interim dividend of €1.42 per share, payable 3 December 2026 to shareholders on the register as of 20 November 2026. Combined with the first-half payment, the full-year 2026 dividend totals €2.24 a share, maintaining an annualised payout ratio of around 50%, according to StockTitan‘s summary of the filing.
CCEP also disclosed progress on its buyback programme: of a planned €1bn for the year, roughly €880m had been completed as at 30 October 2026, the trading update showed. The combination of dividend and buyback underscores the scale of cash the bottler is returning to shareholders even as top-line growth moderates from the pace seen earlier in 2026.
Analysts split on where shares go next
Sell-side reaction to the print was mixed rather than uniformly negative. UBS kept a ‘neutral’ rating but trimmed its target to $107 from $109, while Bernstein rates the stock ‘market perform’ at $106, according to MarketBeat‘s tally of broker notes. Wells Fargo stayed ‘overweight’ but also cut its target, to $115 from $120.
Short-sale activity in CCEP shares had been climbing into the print: FINRA’s daily short-volume ratio touched 0.858 on 23 October before easing to 0.565 on 2 November and ticking back up to 0.718 on 3 November, the day of the results, according to FINRA data. The swings suggest positioning ahead of the update was unsettled, even if the ratio alone does not explain the scale of the share-price reaction.
For a company whose growth story increasingly rests on volume gains alongside price and mix, the next test comes with full-year results, when investors will look for whether reaffirmed guidance converts into an actual beat — or whether 2026’s pattern of in-line prints meeting an unimpressed market continues.
This article is for information only and is not investment advice or a recommendation to buy or sell any asset. Markets move quickly; figures are correct as sourced at the time of writing. Always do your own research before making financial decisions.