MediWound Ltd (NASDAQ: MDWD) reported third-quarter 2026 revenue of $3.6m on 12 November, down from $5.4m a year earlier, according to the company’s Form 6-K filing. The figure that matters more than the top line: MediWound’s full-year guidance has vanished from the release entirely.
In both the first and second quarters of 2026, MediWound reaffirmed a $24m-$26m revenue target for the year. The Q3 statement drops that range, tying the outlook instead to ongoing talks with the US government over its BARDA-backed NexoBrid supply contract, according to the company’s investor relations release.
Revenue down, margins up, guidance gone
Gross profit rose to $1.0m, or 28.5% of revenue, from $0.9m and 16.5% a year earlier, according to BioSpace’s report on the release. Margin improved even as sales shrank, a combination that points to cost discipline rather than growth.
The MediWound full-year guidance that disappeared this quarter had been a fixture of 2026 reporting. Q1 revenue came in at $1.5m with the $24m-$26m range reaffirmed; Q2 revenue reached $3.1m, with the same guidance repeated alongside news of a Master Services Agreement with Vericel under the BARDA contract for NexoBrid, MediWound’s EDGAR filings show. Nine months into the year, cumulative quarterly revenue sits well short of the pace needed to hit that range, and management has chosen to stop restating it.
Instead, the company points to unresolved negotiations with the US government. BARDA funding and the Vericel distribution arrangement have underpinned MediWound’s NexoBrid sales strategy through 2026; the Q3 release frames further government discussions as the swing factor for what full-year revenue ultimately looks like.
Balance sheet shored up with fresh equity
MediWound raised $17.25m in gross proceeds from an underwritten public offering completed after the quarter closed, according to the company’s investor relations statement. The raise follows a year-end 2025 cash position of $54m against $17m of full-year 2025 revenue, the base the current slowdown is being measured against.
Three insiders filed Form 4s with the SEC within minutes of each other on the same day as the earnings release: chief executive Ofer Gonen at 12:38 UTC, Nachum Shamir at 12:34 UTC, and David Morton Fox at 12:31 UTC, EDGAR records show. The filings do not disclose share counts or transaction values in the public record checked for this report, so the size of any disposals or acquisitions cannot be confirmed.
Market barely moved
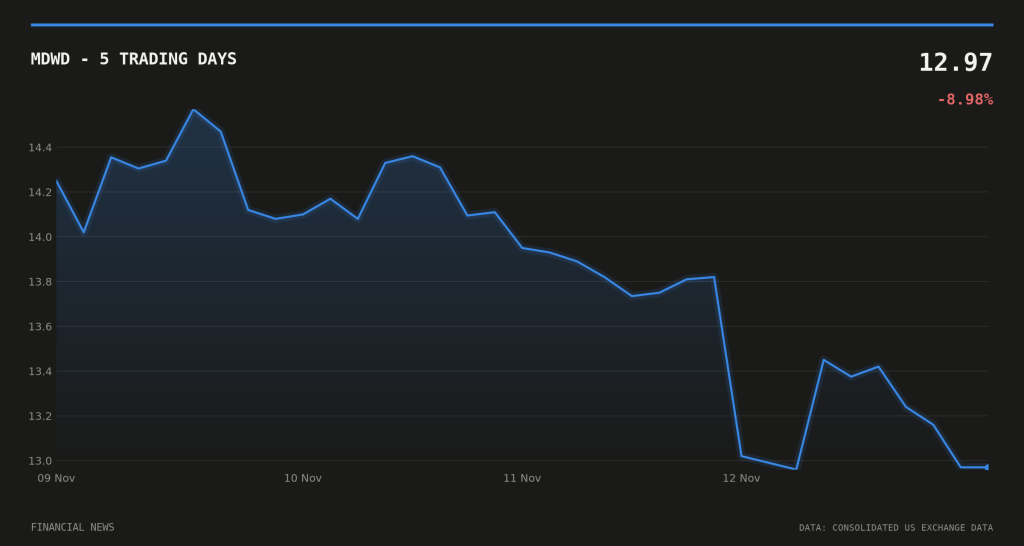
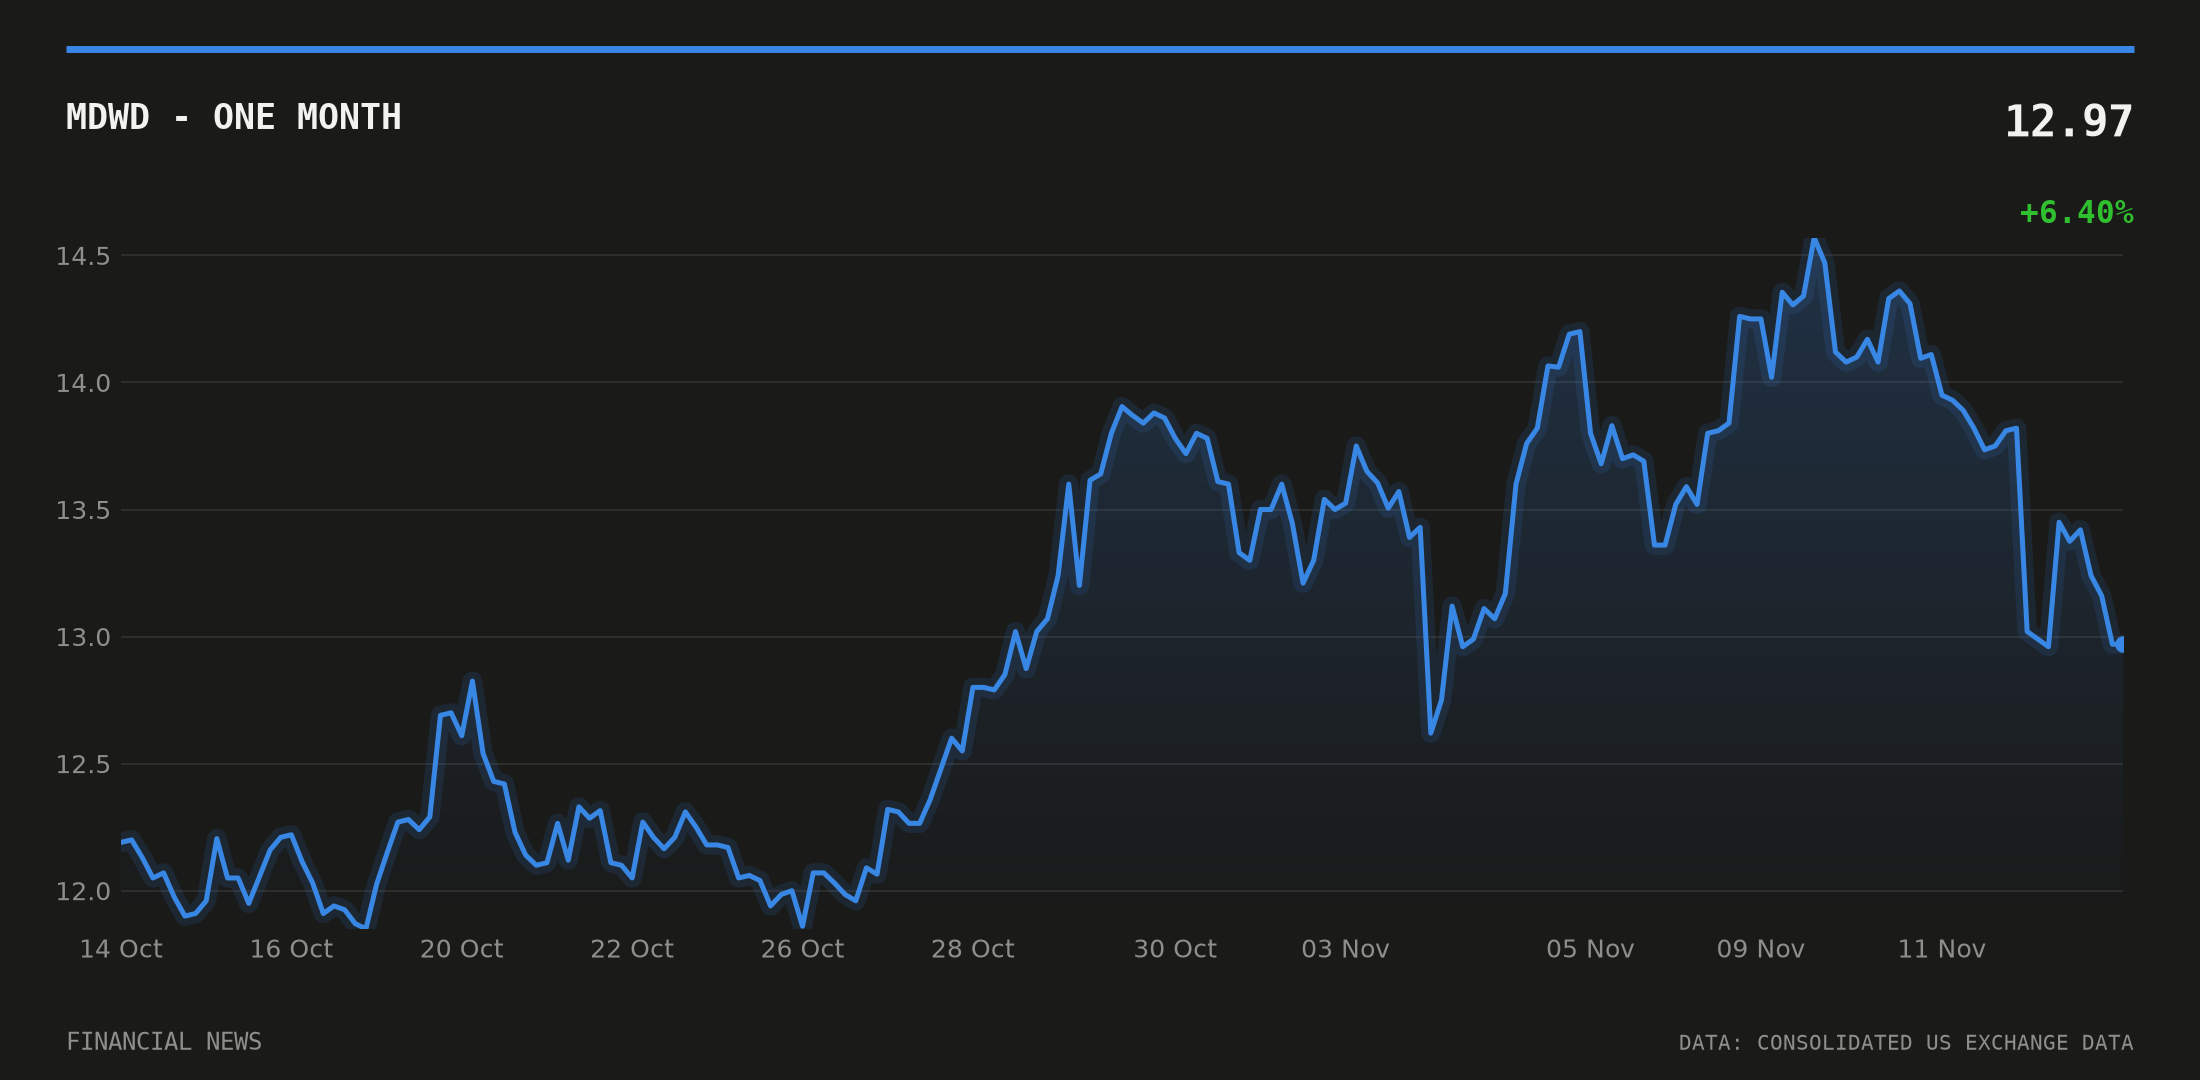
MDWD shares closed near $12.97 as of 21:00 UTC on 12 November, up just 0.08% on the day despite the guidance shift, according to Nasdaq market data. The stock had already climbed 6.49% over the prior 20 trading days, with volume on earnings day running 2.36 times the 20-day average.
Short-sale activity was elevated but not unusual for the stock. FINRA data put the short-volume ratio at 51.7% of trades on 12 November, within a range of 29.3% to 76.4% over the prior ten sessions. Neither figure signals a dramatic shift in positioning around the announcement.
The muted share reaction came against a backdrop of rising US borrowing costs, with the 10-year Treasury yield climbing to 4.98% on 10 November from 4.88% previously, according to Federal Reserve data. Higher yields have weighed broadly on smaller biotech names reliant on external financing, a dynamic that may have shaped how investors read MediWound’s own capital raise.
What comes next
MediWound’s EscharEx Phase III VALUE trial in venous leg ulcers remains the pipeline catalyst the company has flagged across its 2026 releases, with enrolment and interim-assessment timelines shifting as the year has progressed. For now, investors have one clear marker to watch: whether the BARDA and Vericel discussions MediWound cited in place of its guidance produce a resolution before the next quarterly update.
This article is for information only and is not investment advice or a recommendation to buy or sell any asset. Markets move quickly; figures are correct as sourced at the time of writing. Always do your own research before making financial decisions.