EZCORP (NASDAQ: EZPW) held its fiscal fourth-quarter earnings call on 12 November 2026, a day after filing results for the quarter and year ended 30 September.
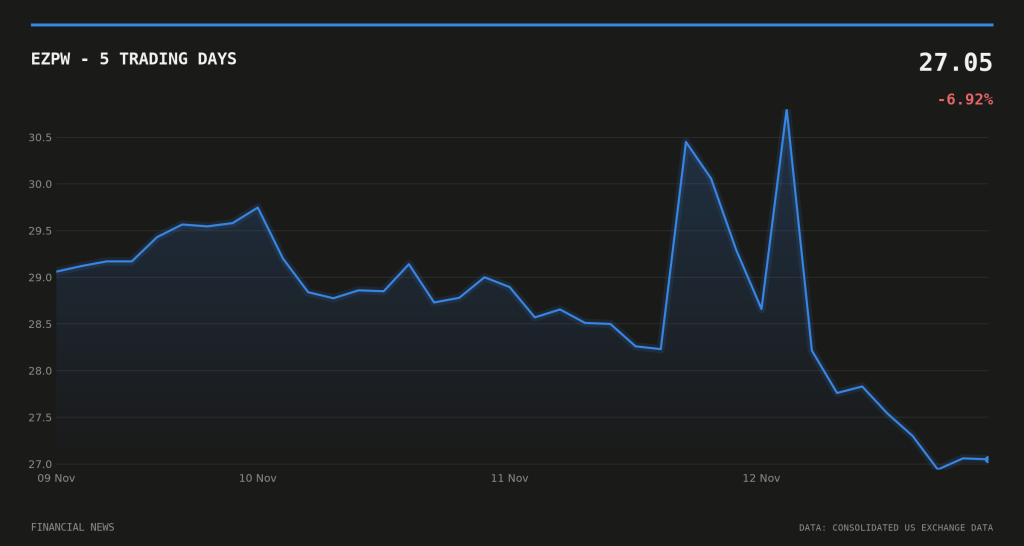
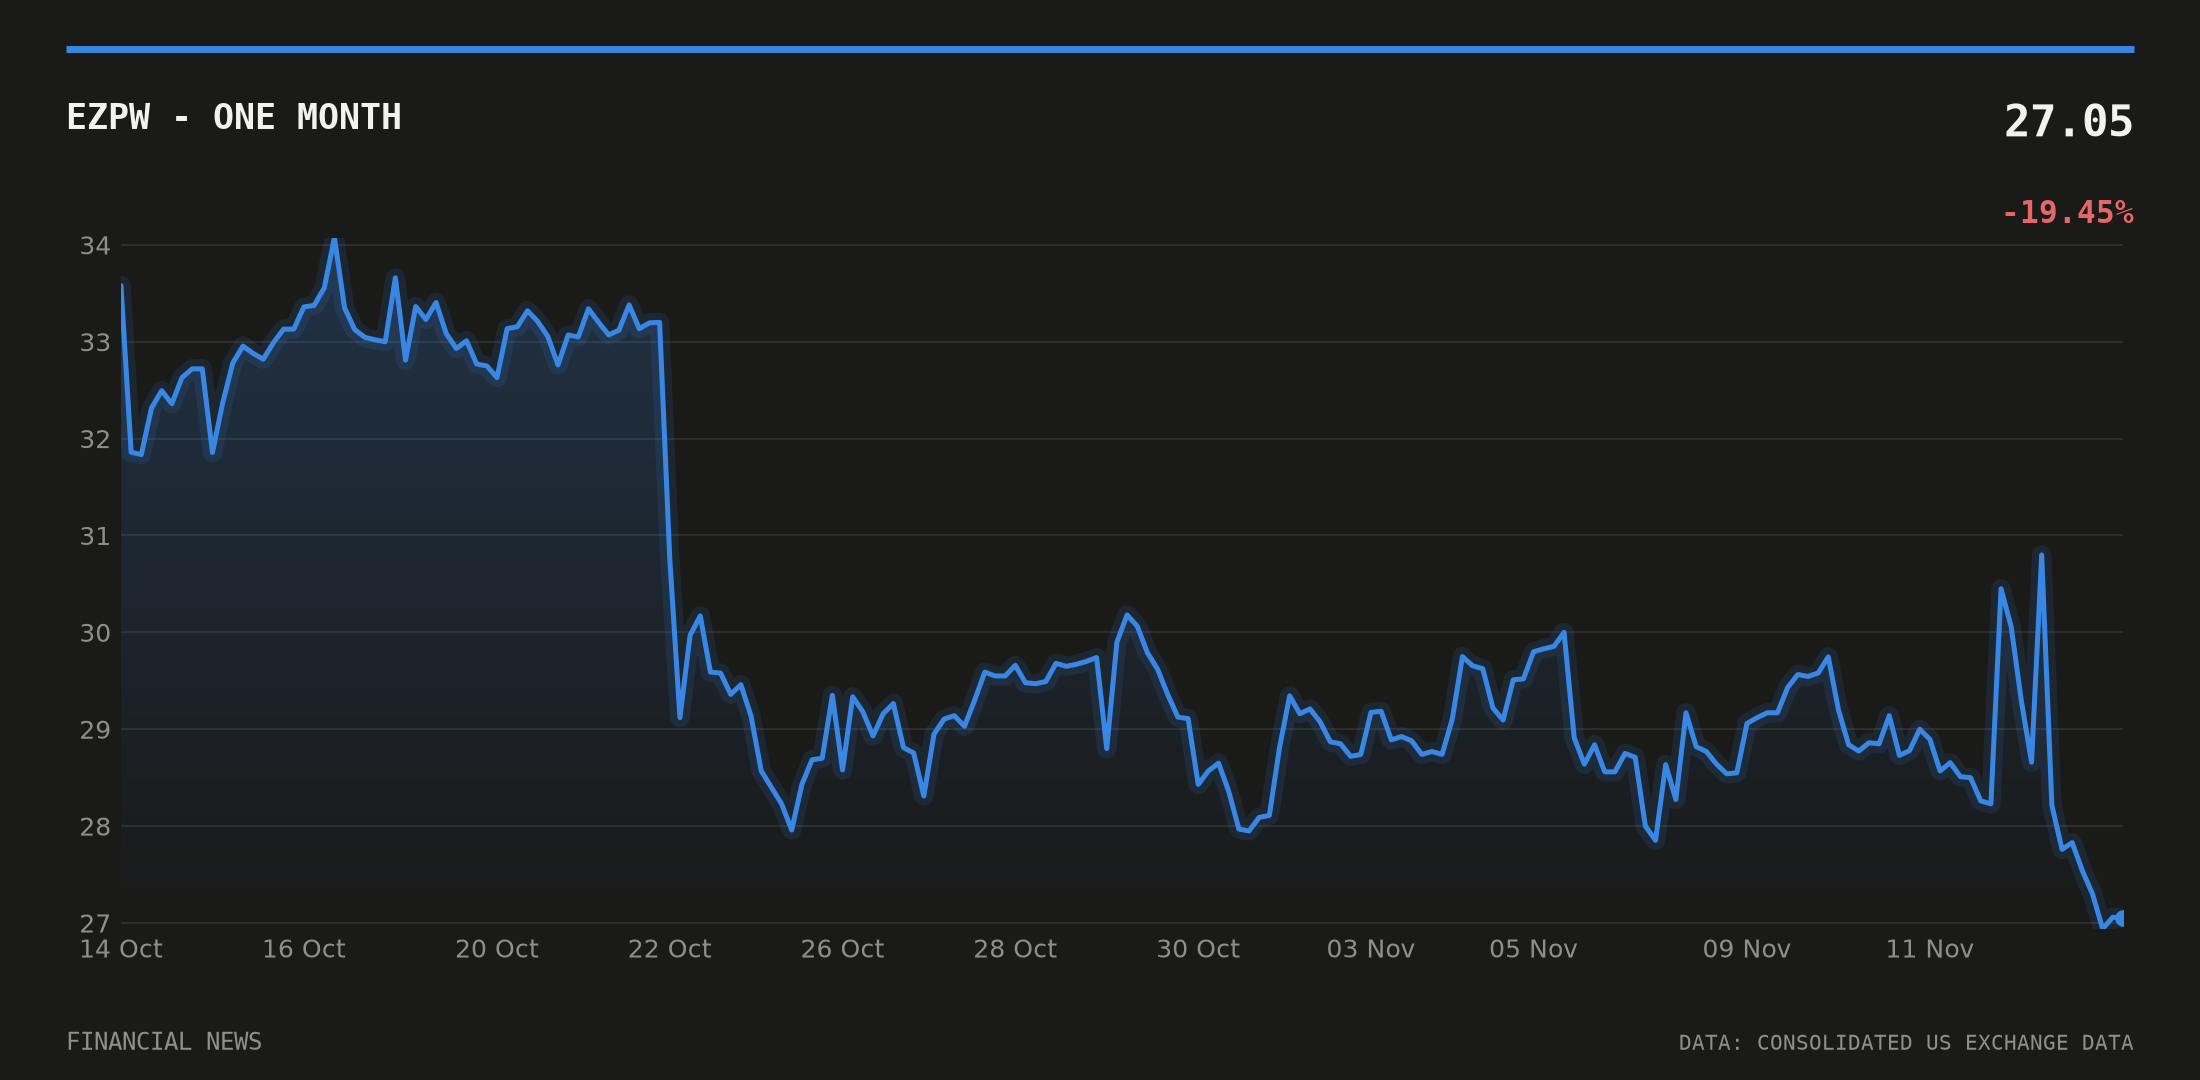
Shares fell 4.13% on the day to close at $27.05, even as the pawn lender reported revenue up roughly a third year-on-year and full-year adjusted EBITDA growth of 47%, according to the company’s filing.
Record quarter, falling stock
The numbers themselves told a strong story. Fourth-quarter revenue came in at roughly $447m, beating consensus estimates near $427m-$428m, according to GuruFocus. Adjusted earnings per share reached $0.43, a cent ahead of the $0.42 consensus, as reported by Investing.com.
Net income rose 28% year-on-year to $34.3m. For the full year, revenue climbed 30% to $1.7bn and adjusted EBITDA grew 47% to $277m, figures reported by Benzinga.
Shares initially jumped 10.6% in after-hours trading on 11 November, touching $31.30 immediately after the release, according to GuruFocus. That move reversed sharply over the following session. By 12 November the stock had given back the gain and more, trading down 7.16% over 20 days and on volume 2.81 times the 20-day average. The stock’s 20-day high of $30.80 sat just below the after-hours spike level, underscoring how quickly sentiment turned.
What soured the mood on the call
The sell-off, despite the beat, points to concerns raised during the call itself rather than the headline figures. A transcript teaser from The Motley Fool flagged Latin American labour costs and store-integration timing as specific watch points management addressed, a detail that may explain why investors focused on costs rather than the top-line beat.
Not every outlet read the quarter the same way. One GuruFocus headline described the revenue print as a miss against a $465.04m estimate, a figure that contradicts both the primary release and every other outlet’s reporting of a beat. That number appears to be an outlier rather than a genuine read on consensus.
Insiders file, yields climb
Nine EZCORP executives and directors, including chief executive Lachlan Given and chief financial officer Timothy Jugmans, filed Form 4 disclosures with the SEC on 12 November, the same day as the call. The filings do not detail the size or direction of the transactions.
The results landed against a tightening US rate backdrop. The 10-year Treasury yield rose to 4.98% by 10 November, up from 4.88%, while the 2-year yield climbed to 4.73% from 4.56% over the same period, according to data from the Federal Reserve Bank of St Louis. The 10-year/2-year spread remained only mildly positive at 0.24 percentage points.
Short-sale activity in EZPW also shifted sharply around the print. FINRA data show the short-volume ratio climbing from 0.333 on 30 October to a peak of 0.728 on 10 November, just ahead of the release, before easing to 0.52 by 12 November — a pattern consistent with traders positioning ahead of results and then partially unwinding those bets once the numbers landed.
The quarter in context
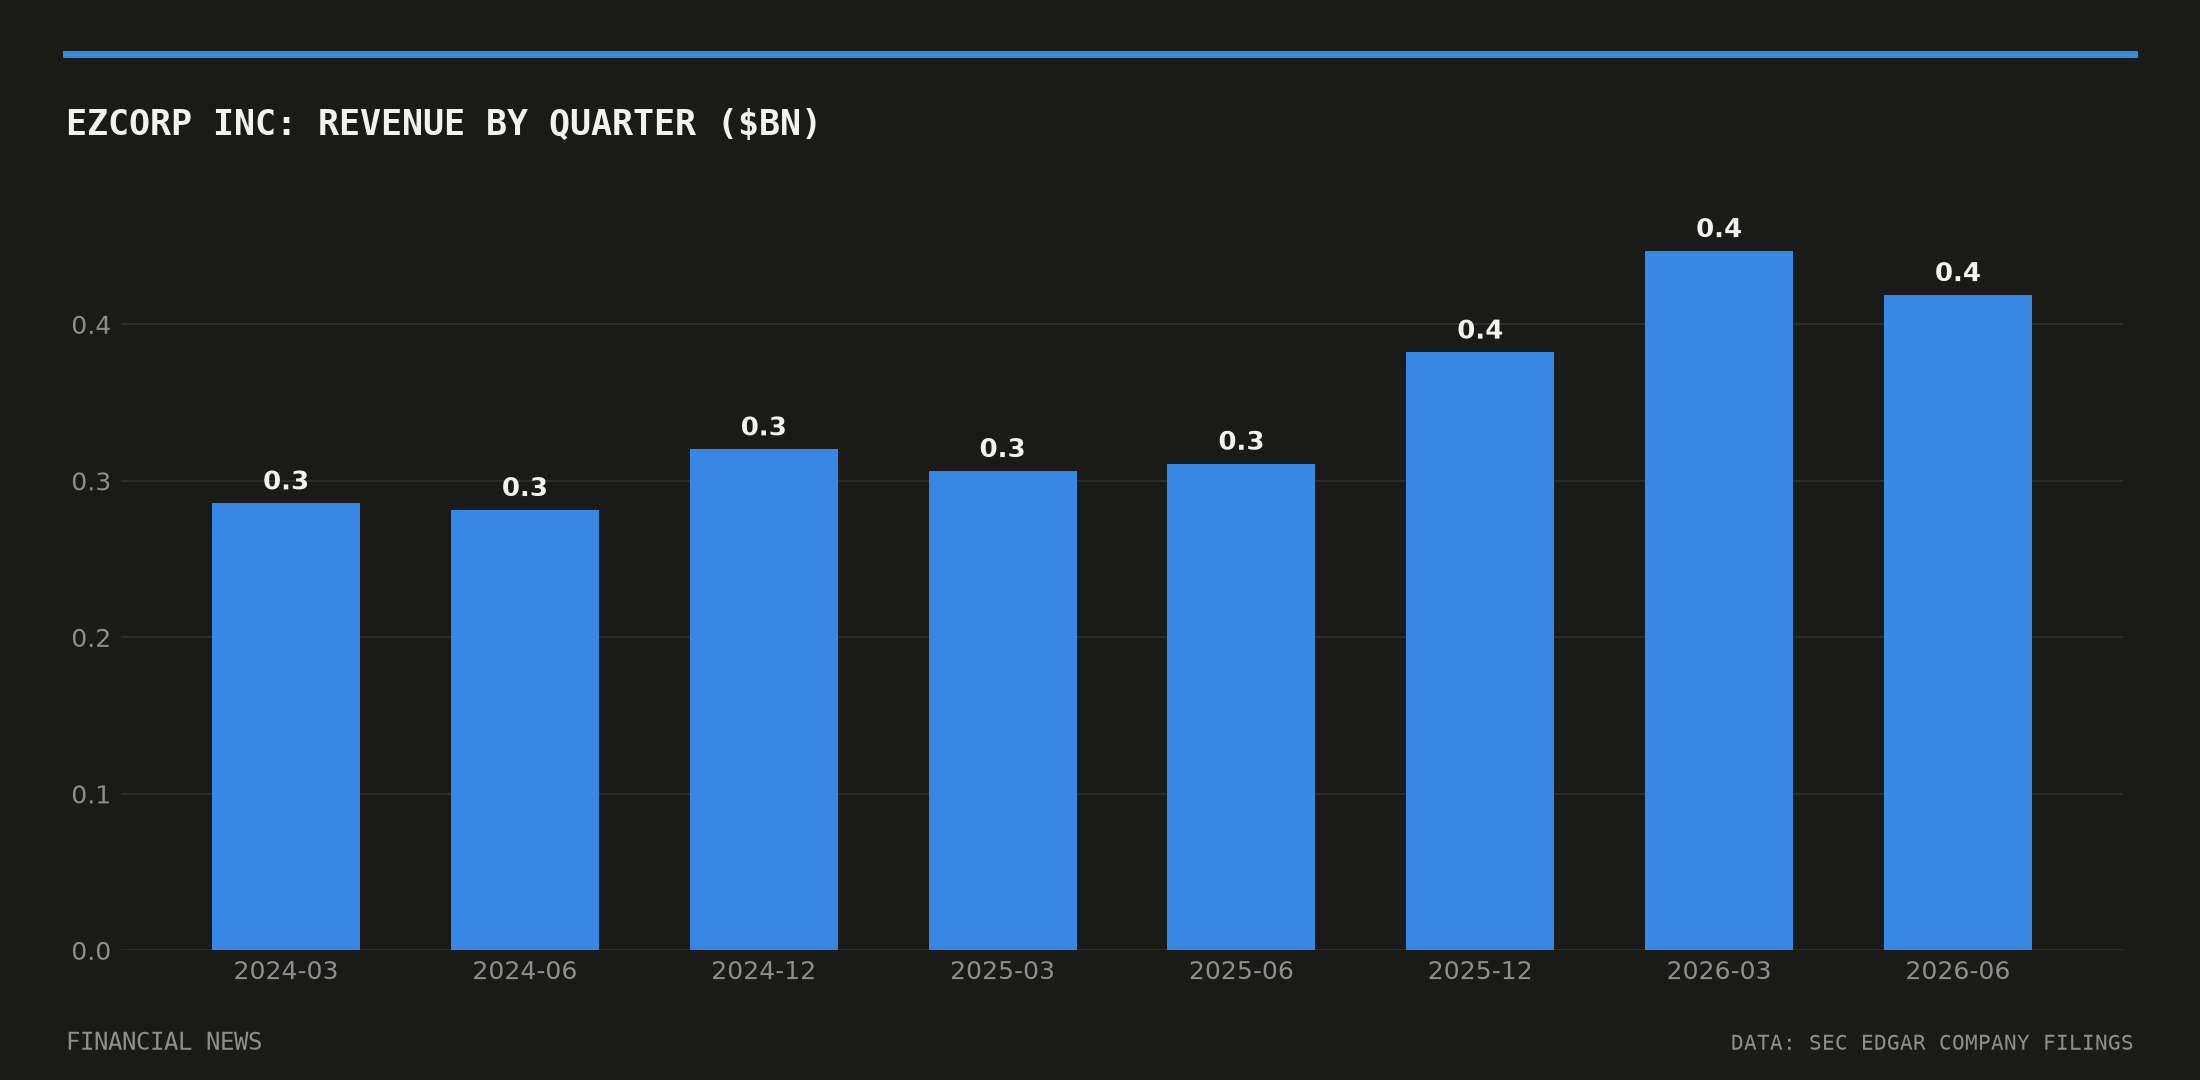
EZCORP’s fourth-quarter net income of $34.3m continues a run of sequential growth across recent quarters. The company posted $44.3m in net income for its fiscal first quarter of 2026 and $49.1m in the second quarter, according to EZCORP’s own 10-Q filings with the SEC, before easing to $38.2m in the third quarter. Revenue over the same stretch rose from $382m in the first quarter to $446.9m in the second, dipping slightly to $418.7m in the third quarter ahead of the fourth-quarter print.
Diluted earnings per share followed a similar arc, from $0.55 in the first fiscal quarter to $0.61 in the second and $0.48 in the third, underlining a business that has delivered consistent, if uneven, growth through the year.
Whether the post-call sell-off marks a lasting repricing or a short-term reaction to cost commentary will likely become clearer as EZCORP reports its fiscal first-quarter 2027 results, when investors can judge whether the Latin American labour and integration pressures flagged on the call persist or ease.
This article is for information only and is not investment advice or a recommendation to buy or sell any asset. Markets move quickly; figures are correct as sourced at the time of writing. Always do your own research before making financial decisions.