Edgewell Personal Care Co (EPC) reported fourth-quarter fiscal 2026 results on 12 November 2026, with net sales of $484.1m, up 3.0% on the same period a year earlier.
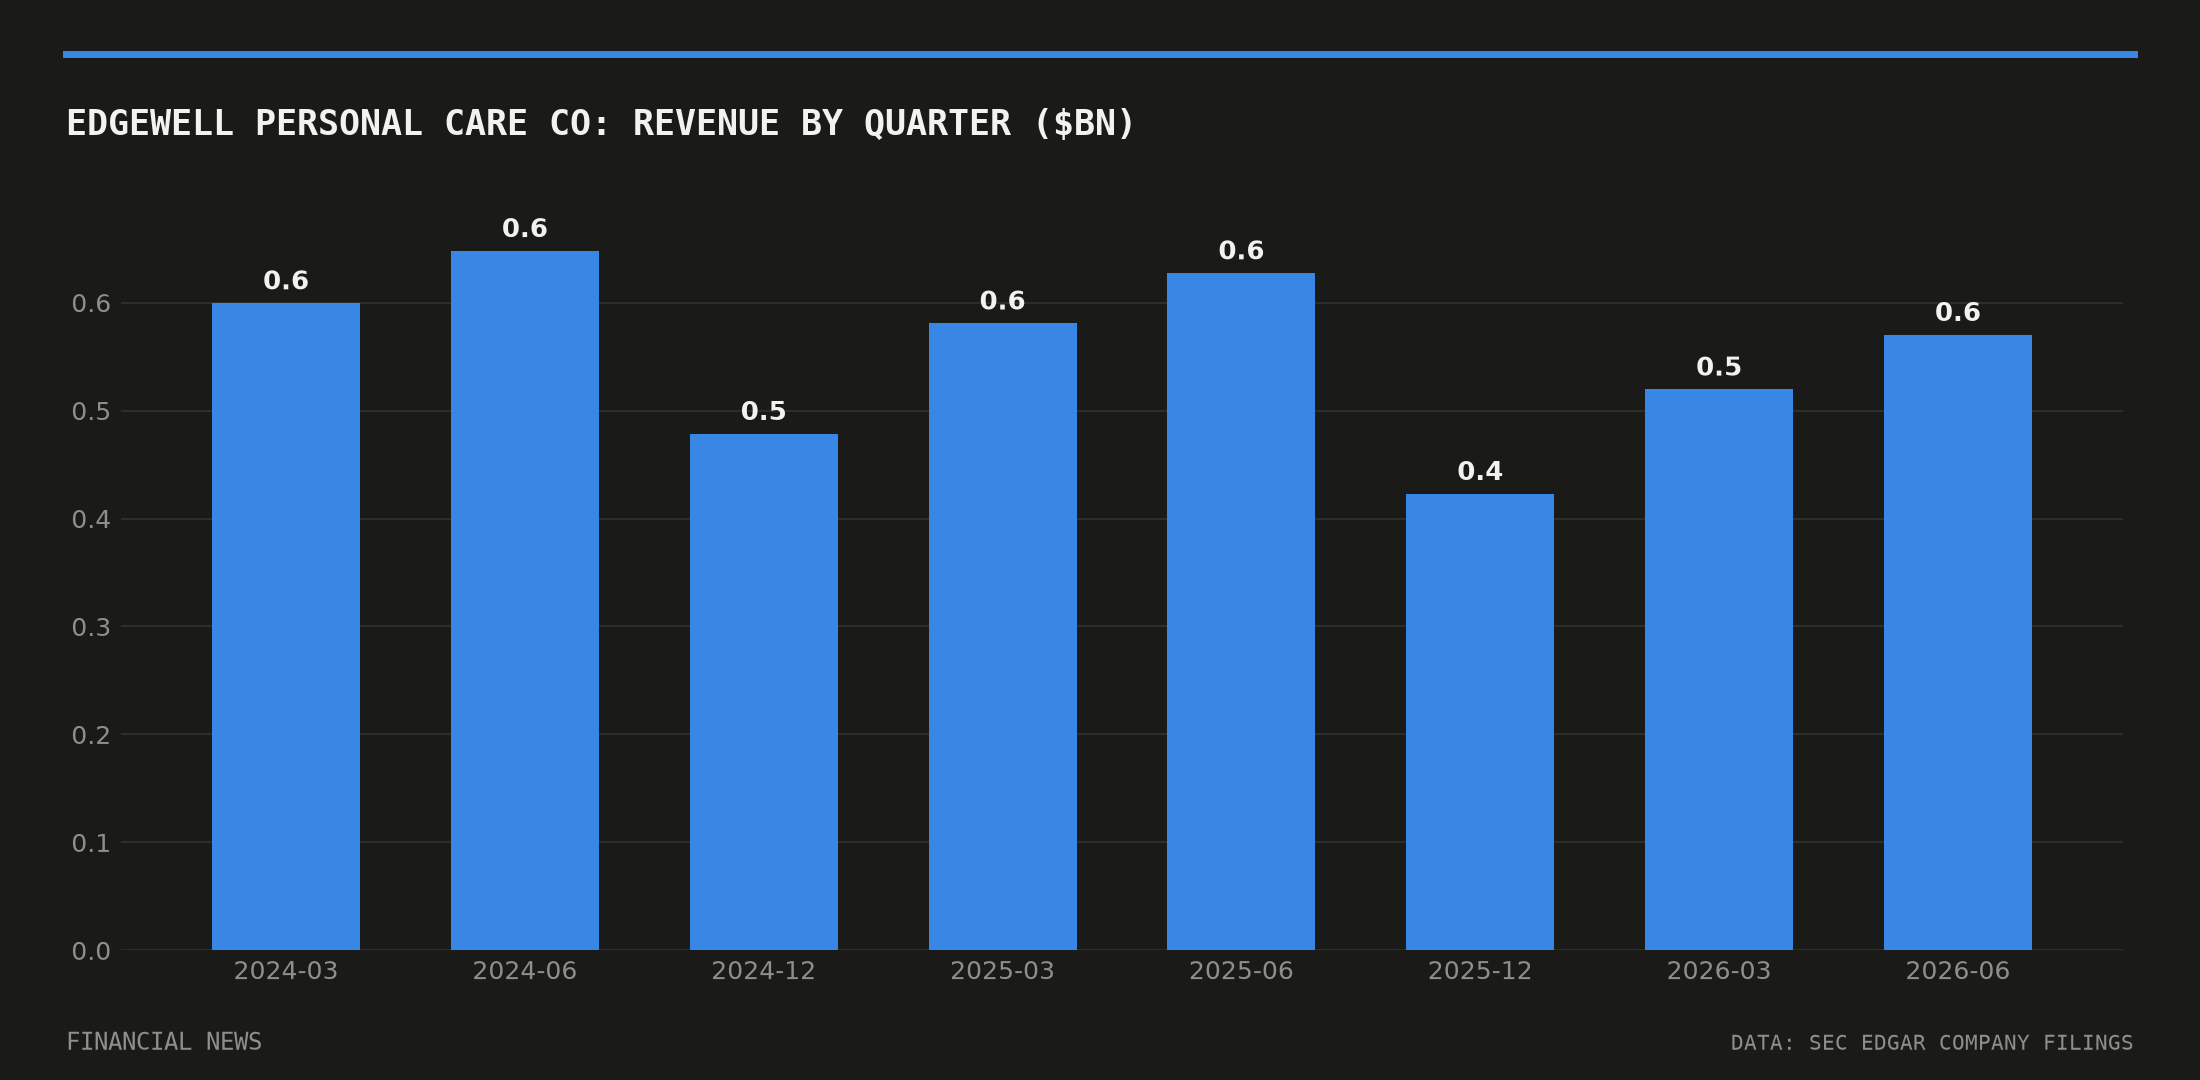
Full-year net sales reached $1,996.5m, up 1.8%, the company said. The figure lines up with Edgewell’s own quarterly filings: revenue of $422.8m, $519.5m and $570.1m for the first three quarters sums to $1,512.4m, which with the newly reported fourth-quarter number adds up exactly.
Organic growth slows to a crawl
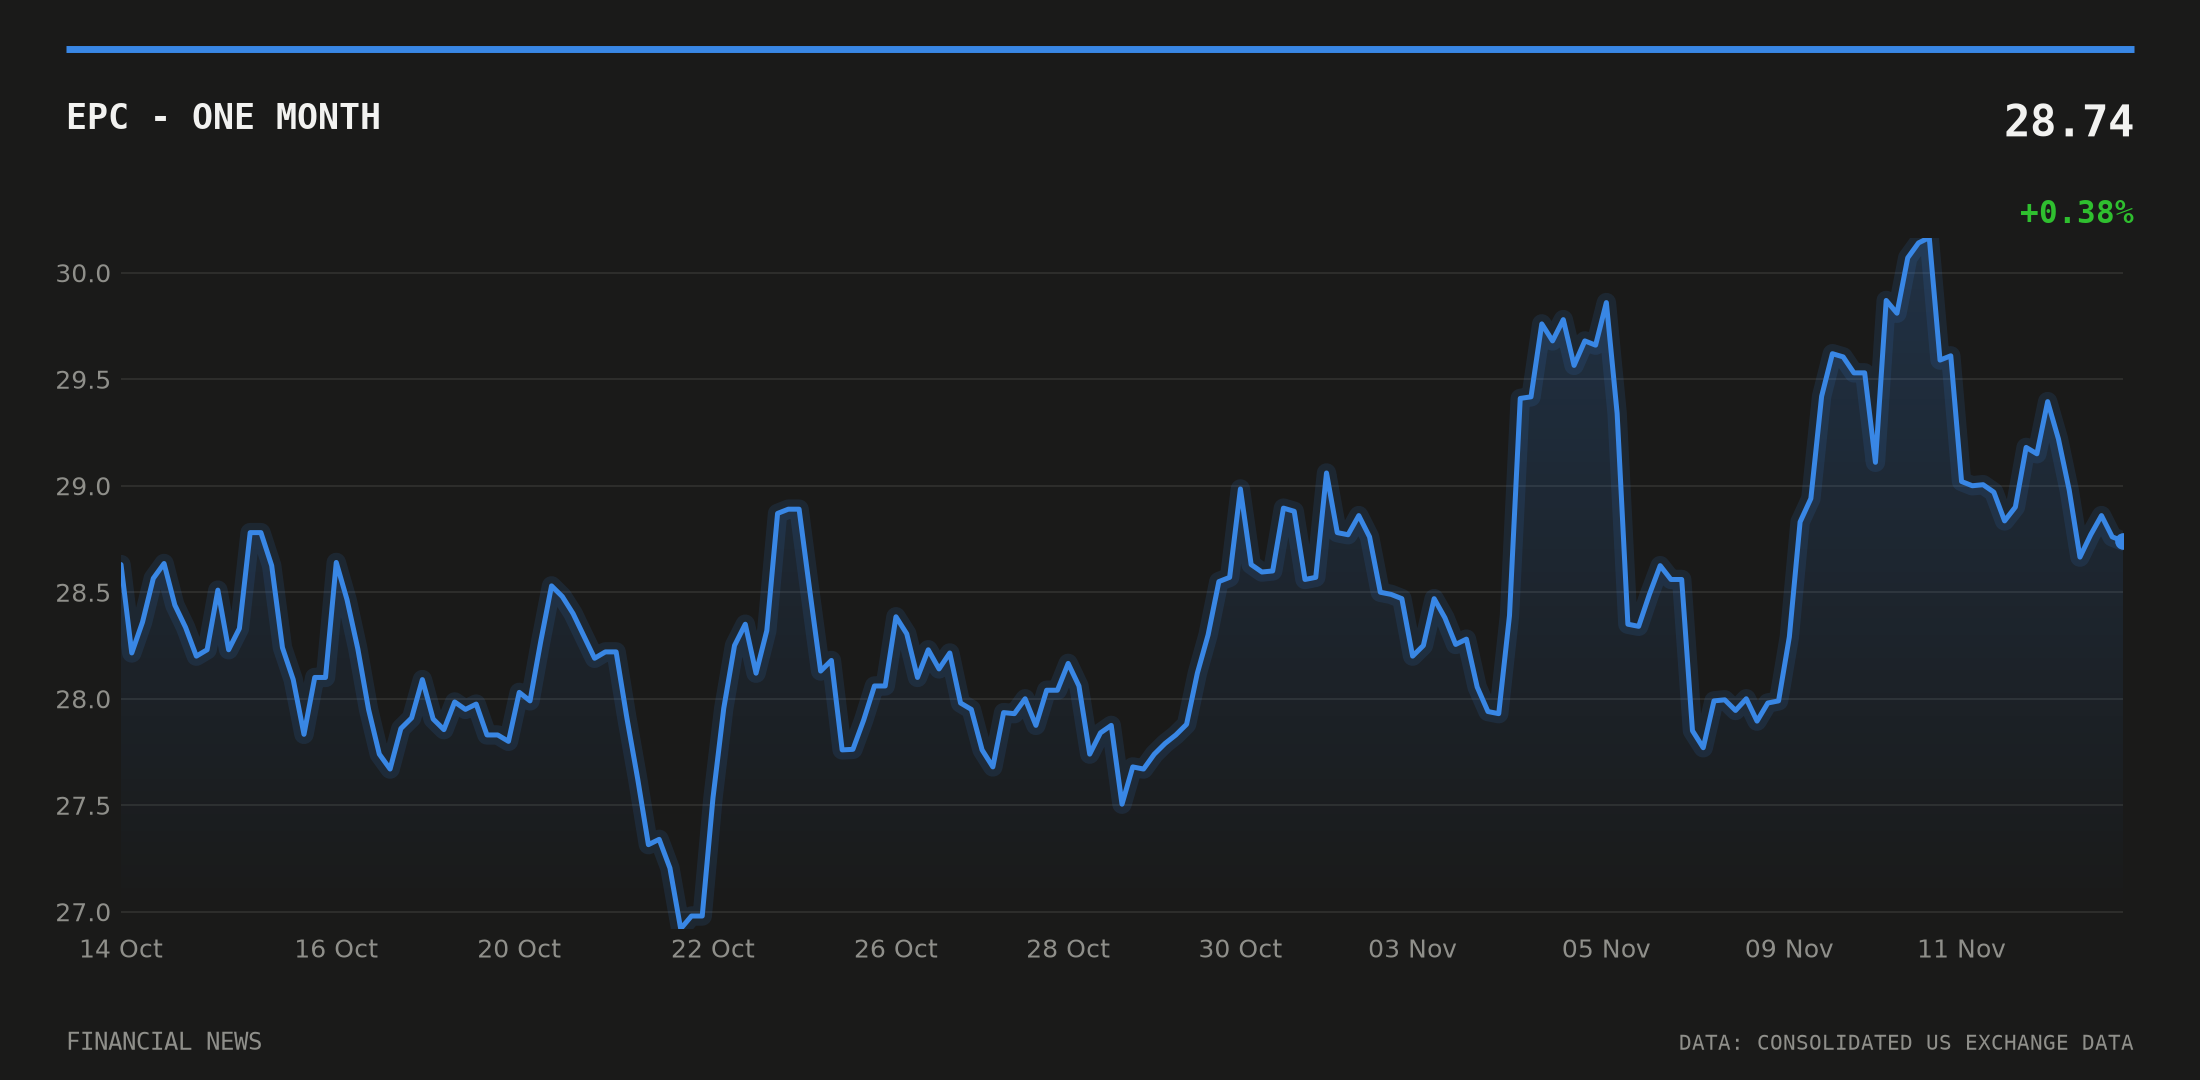
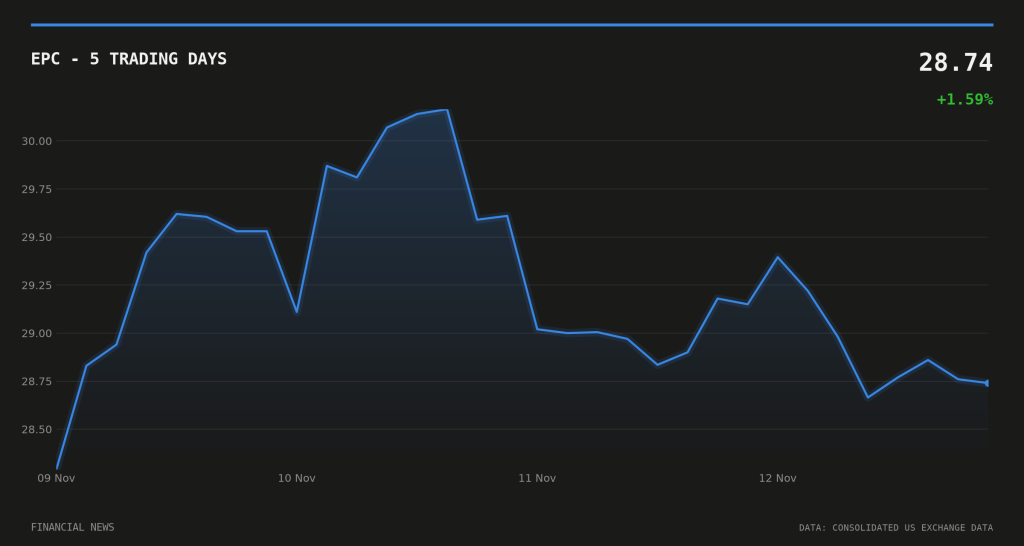
Edgewell said organic net sales grew 3.1% in the fourth quarter but just 0.3% across the full year, a gap that points to a weak first nine months offset by a stronger finish. The shaving-to-suncare group’s shares closed down 2.23% at $28.74 on the day of the release, with trading volume running at 1.77 times the 20-day average, according to consolidated exchange data. The stock had traded between $27.505 and $30.165 over the preceding 20 sessions.
The quarter’s swing from loss to profit is not new for Edgewell. The company’s own 10-Q filings show diluted earnings per share bouncing between a $1.41 loss in the December 2025 quarter, tied to a $65.7m net loss, and a 29-cent profit by the June 2026 quarter. That volatility has run through much of the past two years, with EPS ranging from a four-cent loss to 98 cents across the eight quarters on record.
Another restructuring round
Edgewell also announced what it called global transformation actions, including further consolidation of its Wet Shave operations to simplify the organisation and improve supply-chain efficiency. The company expects to book around $55m in pre-tax charges during fiscal 2027 tied to the restructuring and repositioning work.
That follows a run of losses that has already weighed on the group’s reported earnings, including the $65.7m shortfall booked in the first quarter of fiscal 2026. Layering fresh charges onto a business still working through prior rounds of cost-cutting raises the question of how much more “simplification” the Wet Shave unit still needs before margins stabilise.
Guidance for the year ahead
For fiscal 2027, Edgewell guided adjusted earnings per share to a range of $1.85 to $2.15. The company did not attach a net-sales growth target to that guidance in the materials reviewed.
Four Edgewell executives, including chief executive Rod R Little, filed Form 4 disclosures with the SEC on the same day as the earnings release, according to EDGAR records. Filings from Jessica Spence, LaTanya Langley and John M Dunham were lodged within minutes of one another on 12 November, though the specific share and value fields were not disclosed in the index filings.
Trading backdrop steady
Short-selling activity in EPC showed no unusual spike around the results. FINRA’s daily short-sale volume ratio for the stock stood at 0.478 on the day of the release, within the 0.42-to-0.674 range recorded over the prior ten sessions, suggesting the earnings print did not trigger a shift in positioning from short sellers.
The wider macro backdrop remained largely unchanged into the release. The 10-year Treasury yield stood at 4.98% on 10 November, up from 4.88% a session earlier, while the unemployment rate ticked down to 4.1% in October from 4.2% the prior month, according to Federal Reserve data. Neither shift appears to have been a material driver of the stock’s move on the day.
Investors will next watch Edgewell’s first-quarter fiscal 2027 filing for early signs of whether the latest Wet Shave consolidation narrows the gap between quarterly organic growth and the thinner full-year trend, and whether the $55m in planned charges stays within that guided range.
This article is for information only and is not investment advice or a recommendation to buy or sell any asset. Markets move quickly; figures are correct as sourced at the time of writing. Always do your own research before making financial decisions.