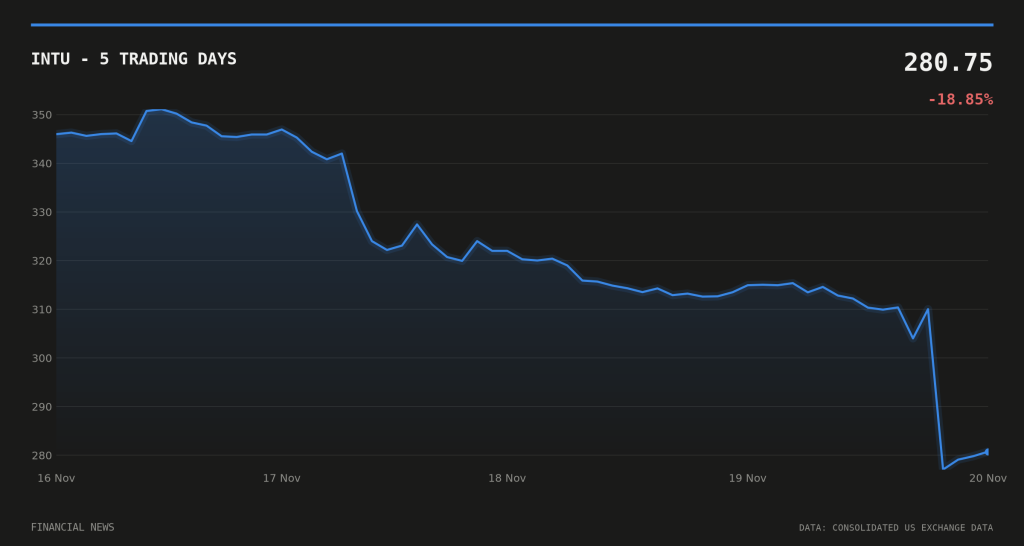
Intuit (NASDAQ: INTU) has agreed to sell Mailchimp to Bending Spoons for $3.68bn, the company said on 19 November 2026, alongside first-quarter results that beat forecasts but failed to stop shares falling.
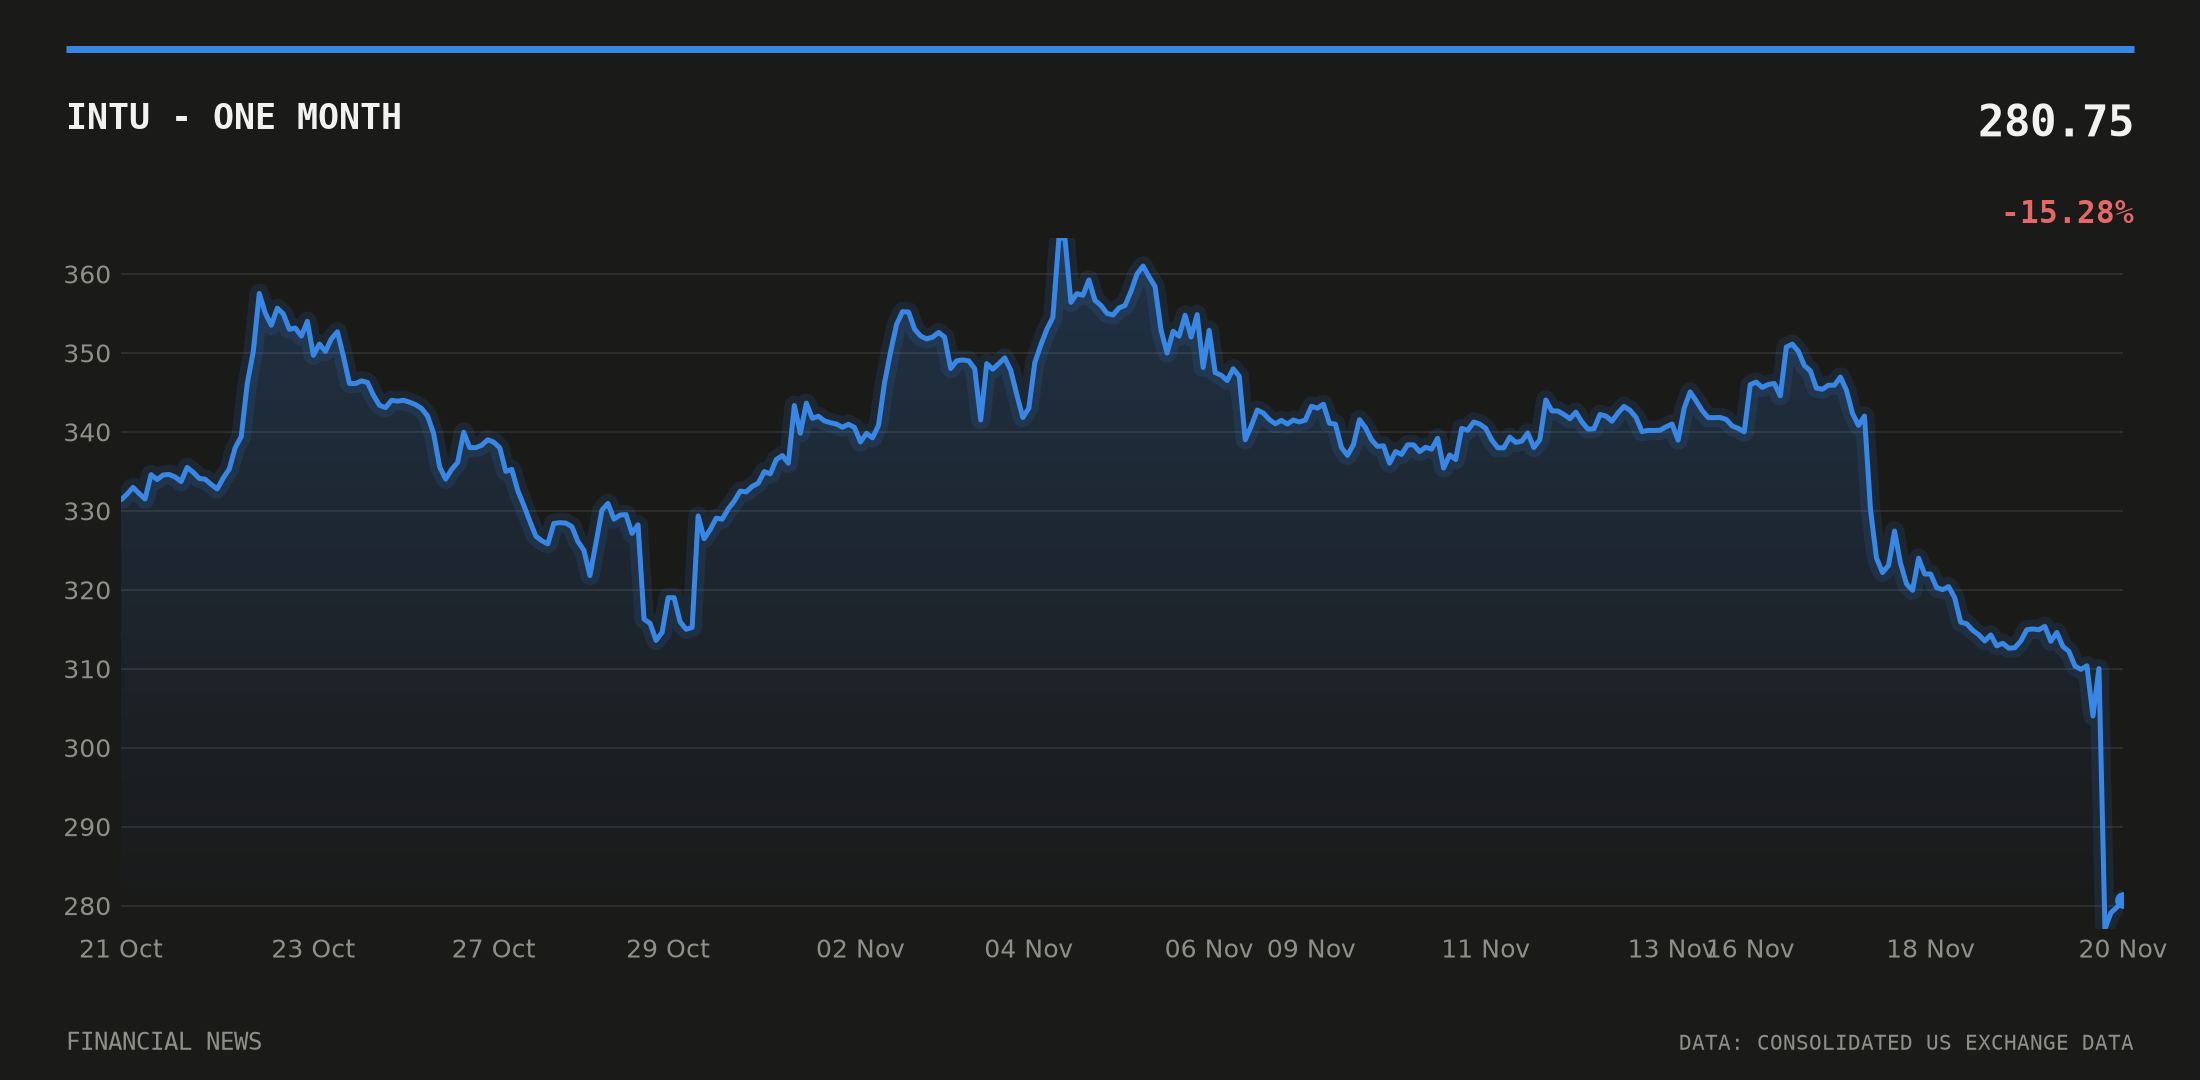
Intuit shares dropped 9.75% to $279.70, according to consolidated US exchange data, taking the 20-day decline to 16.5% on volume 2.3 times the recent average.
Intuit Mailchimp sale terms
The Intuit Mailchimp sale comprises $3.31bn in cash and $368m in Bending Spoons stock, Intuit disclosed in its first-quarter earnings release. The deal covers The Rocket Science Group LLC, the legal entity behind Mailchimp, as first reported by SiliconANGLE.
Intuit bought Mailchimp roughly five years ago for about $12bn, meaning the sale price is less than a third of the original outlay, as first reported by Reuters.
Bending Spoons, the Italian acquirer, already owns Vimeo, AOL, Eventbrite and WeTransfer, continuing a run of deals for established consumer internet brands, according to PPC Land.
Earnings beat, guidance cut
Intuit’s fiscal first-quarter revenue rose 12% year-on-year to $4.354bn from $3.885bn, according to its 10-Q filing. Net income climbed to $695m from $446m, with diluted earnings per share up to $2.59 from $1.59.
Non-GAAP earnings came in at $2.91 a share on $4.35bn of revenue, beating Wall Street estimates, as first reported by Investing.com.
Shares fell anyway. Intuit cut its full-year revenue guidance to $23.08bn-$23.37bn, driven chiefly by a weaker outlook for Credit Karma, where it now expects growth of 3%-7%, down from 11%-13%, as first reported by Seeking Alpha.
A pattern across recent quarters
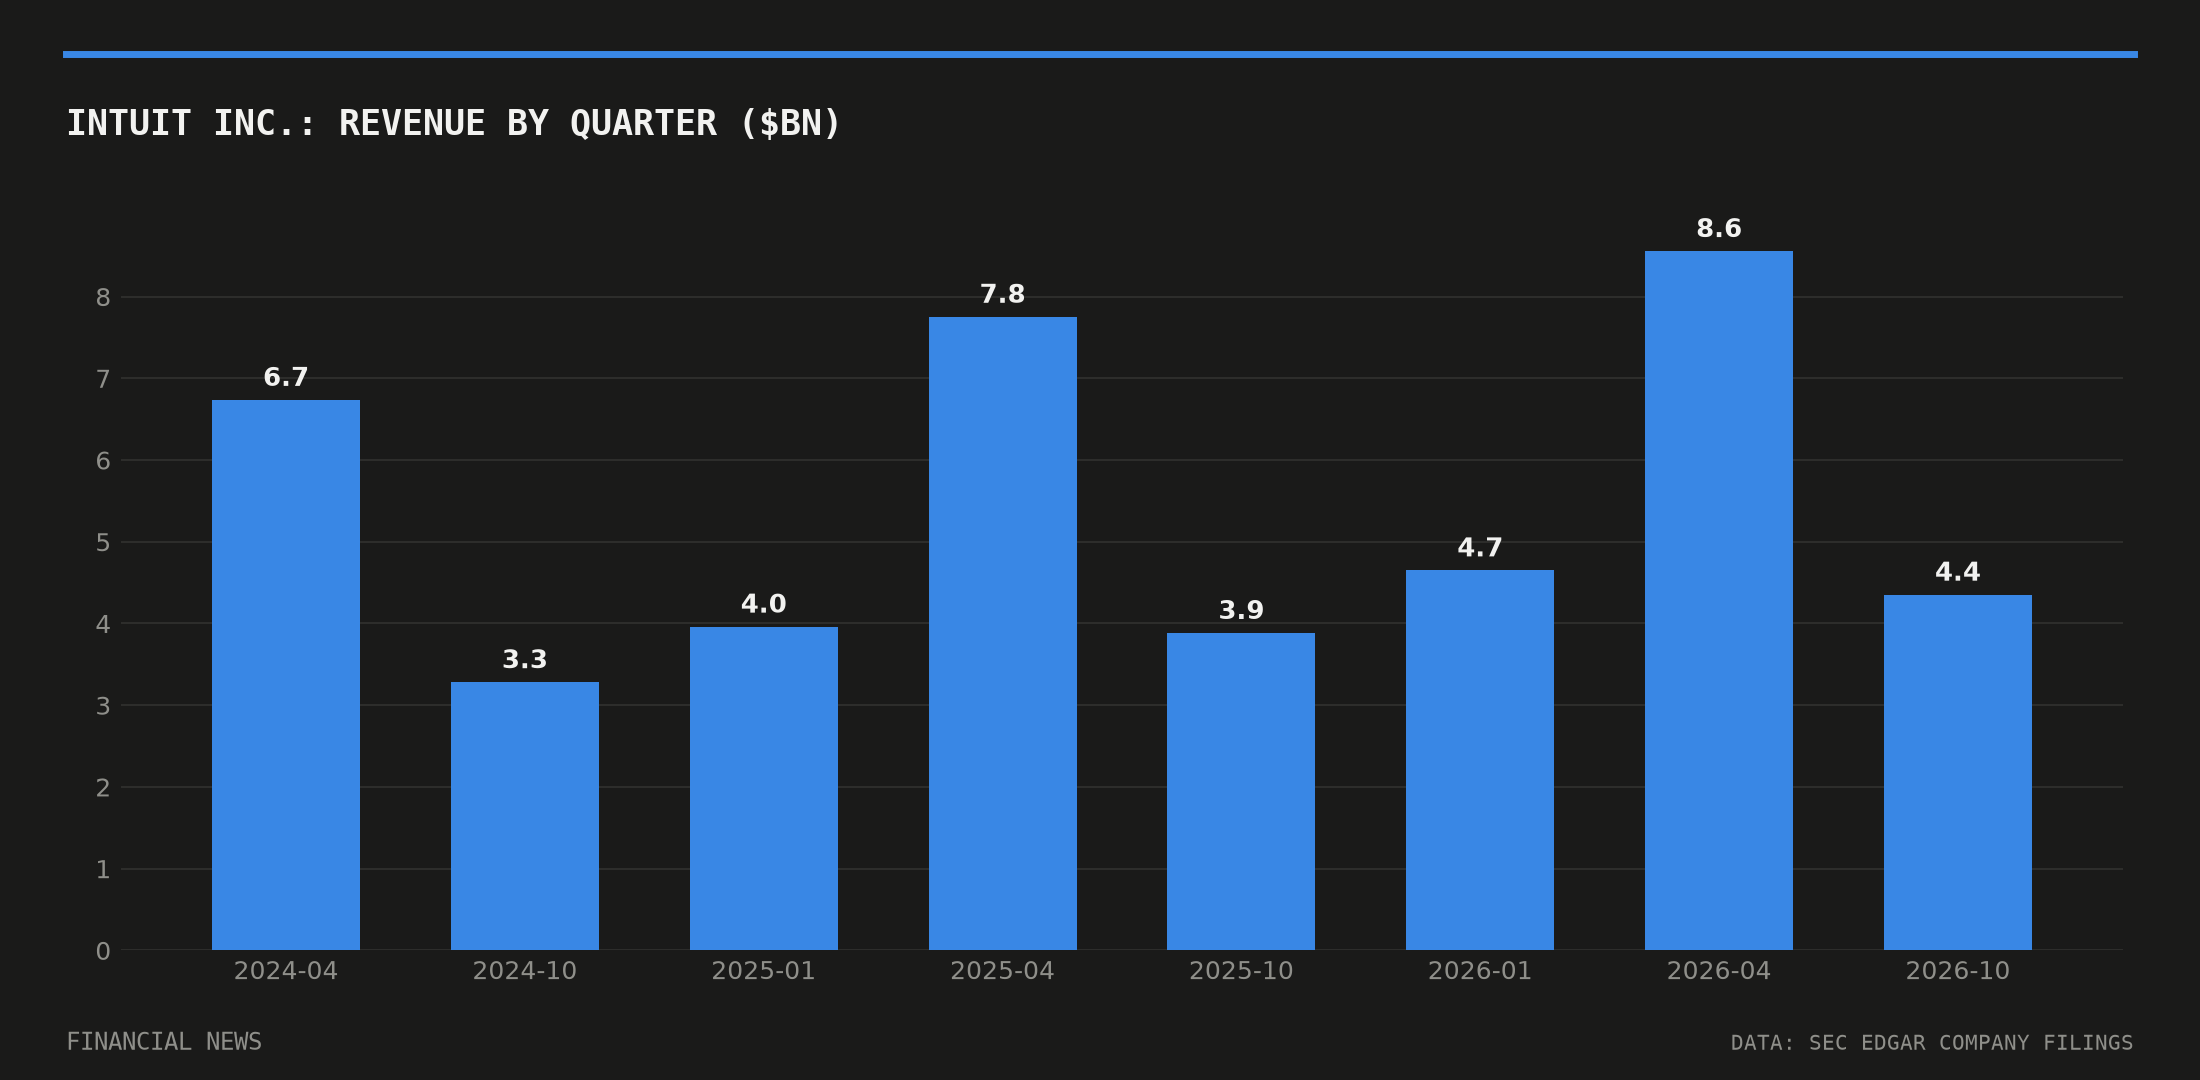
The first-quarter beat extends a run of double-digit revenue growth that has held for well over a year. Intuit’s second fiscal quarter of 2026 brought revenue of $4.651bn and net income of $693m, up from $3.963bn and $471m a year earlier, filings show. The preceding third quarter, which captures the bulk of the US tax season, produced revenue of $8.558bn and net income of $3.064bn, against $7.754bn and $2.82bn in the same period a year before, according to Intuit’s 10-Q filing for that quarter.
That seasonal pattern – modest first and second quarters, a large third quarter weighted to tax filing, in the United States – means the latest 12% revenue gain sits broadly in line with the growth rates Intuit has posted since early 2024. The guidance cut on Credit Karma, rather than the quarterly print itself, is what moved the share price.
Market backdrop
The announcement landed with the 10-year US Treasury yield at 5.07% and the two-year at 4.8%, according to FRED data from the Federal Reserve Bank of St Louis, a rate environment that keeps financing costs elevated for large cash-and-stock transactions such as the Bending Spoons deal. The unemployment rate stood at 4.1% in October, down from 4.2% the previous month, per the same Federal Reserve data series.
FINRA daily short-sale figures show INTU’s short-volume ratio ranged between roughly 0.30 and 0.49 across the fortnight before the announcement, with no clear build-up ahead of the news, according to FINRA data.
The Mailchimp divestiture is expected to close in early 2027, Intuit said, leaving the company to focus on TurboTax, QuickBooks, Credit Karma and its newer Intuit Enterprise Suite and Intuit Accountant Suite products. Investors now have two numbers to weigh against each other: a quarter that beat on both revenue and earnings, and a full-year outlook trimmed because one of Intuit’s marquee acquisitions, Credit Karma, is growing more slowly than the company itself forecast three months ago.
This article is for information only and is not investment advice or a recommendation to buy or sell any asset. Markets move quickly; figures are correct as sourced at the time of writing. Always do your own research before making financial decisions.