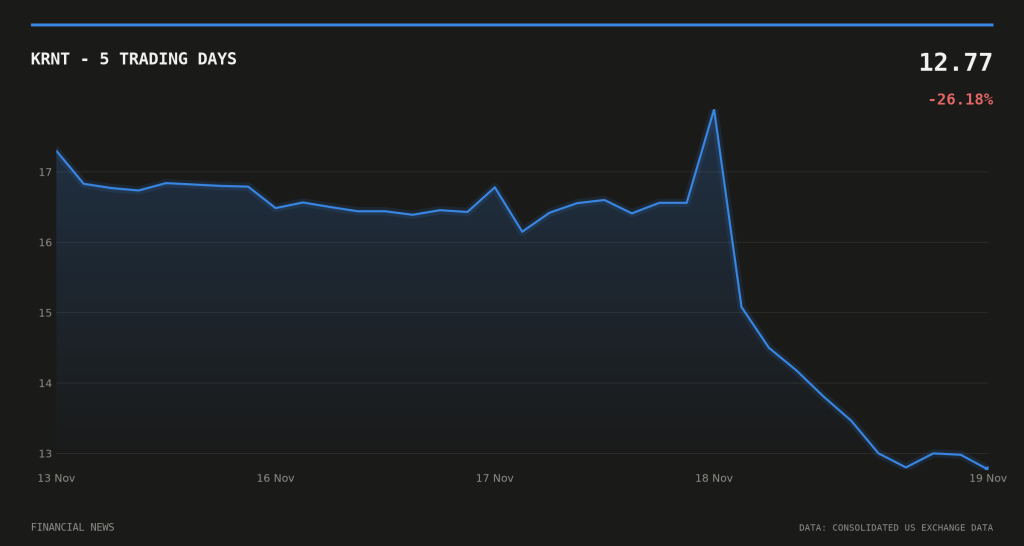
Kornit Digital (NASDAQ: KRNT) reported third-quarter 2026 results on 18 November that beat Wall Street estimates on both revenue and earnings. The shares fell anyway.
Revenue came in at $58.3 million, up around 10% from $53.1 million a year earlier and ahead of the $55.21 million analyst consensus, according to Investing.com. Adjusted earnings per share of $0.11 cleared the $0.05 estimate by a wide margin.
Kornit Digital earnings beat masks a guidance problem
The headline numbers were solid. Non-GAAP net income rose to $5.3 million, or $0.11 a share, from $4.2 million, or $0.09 a share, a year earlier, per the company’s press release. The GAAP net loss narrowed to $0.4 million, or $0.01 a share, from $2.6 million, or $0.06 a share, in the same period last year.
Annual recurring revenue reached approximately $39.4 million, up 83% year on year from $21.5 million, Kornit’s investor relations filing showed – a figure that points to a durable subscription-style business underneath the printed-apparel hardware line.
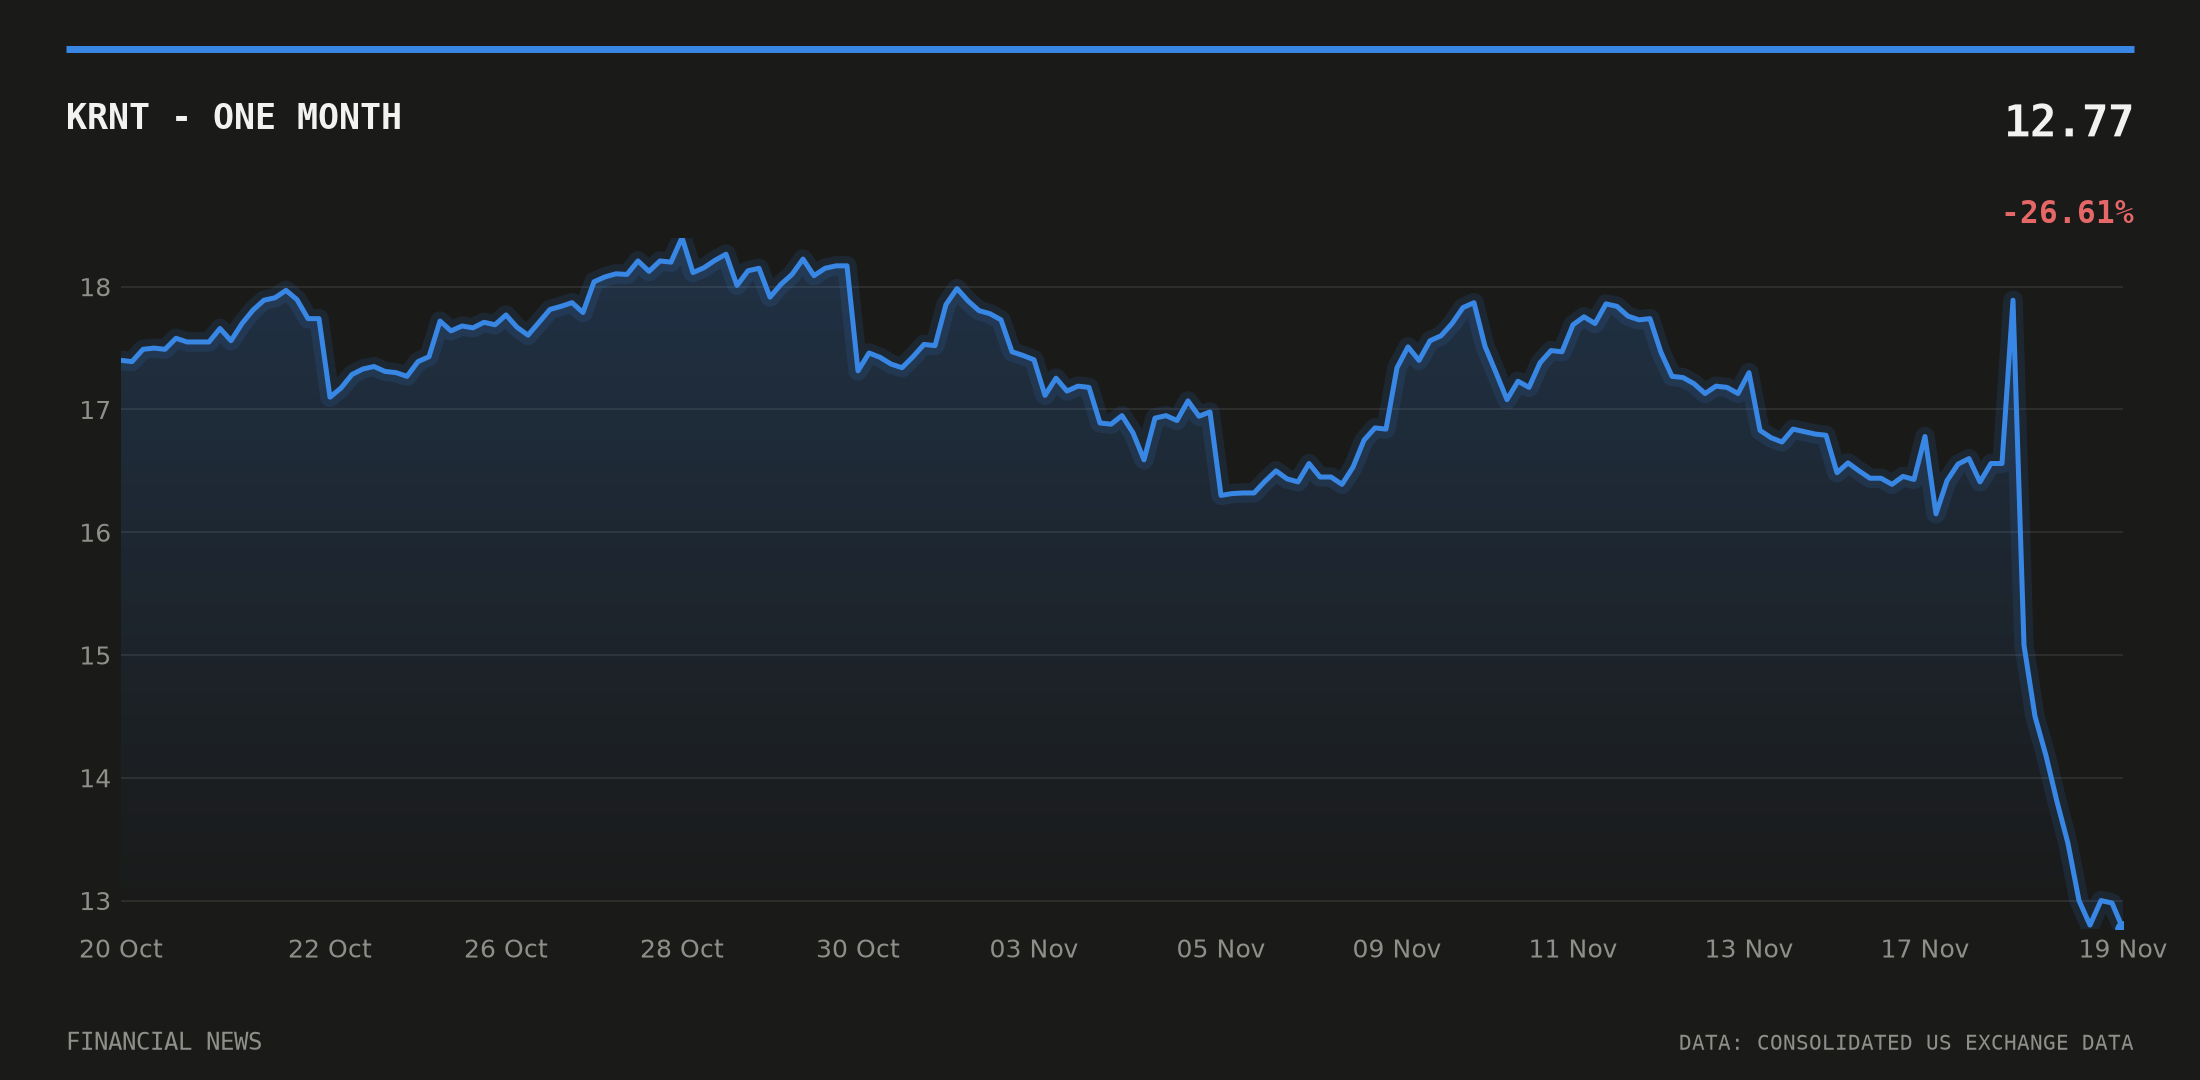
None of it held the stock up. Shares initially jumped around 8% premarket before reversing to close down 9.6% intraday, MarketBeat reported. By the next day the stock traded at $12.77, down 9.94% over 24 hours and 28.72% over 20 days – a fresh 20-day low, with volume running at 2.81 times the 20-day average.
Q4 guidance spooked the market
The reversal traced to forward guidance, not the quarter just reported. Kornit guided Q4 2026 revenue to $60 million-$65 million with adjusted EBITDA margin of just 6.5%-9%, a range that Investing.com said disappointed investors expecting stronger profitability as the business scales.
The pattern is familiar: a company clears consensus on the quarter it has already finished, then stumbles on the guidance for the quarter ahead. Investors priced the latter, not the former.
Filings and positioning around the print
A Form 4 filed with the SEC on 17 November – the day before the earnings release – showed a transaction by Kornit’s chief technology officer, Yaaqov Mann. The filing’s public index confirms the transaction occurred but does not break out share counts or value in the material available.
Short-sale activity ahead of the report was elevated but not extreme. FINRA’s daily short-sale volume data put Kornit’s short ratio at 0.451 on the day of the print, having swung between roughly 0.19 and 0.68 over the prior two weeks – a range consistent with active two-way positioning rather than a crowded short bet going into the numbers.
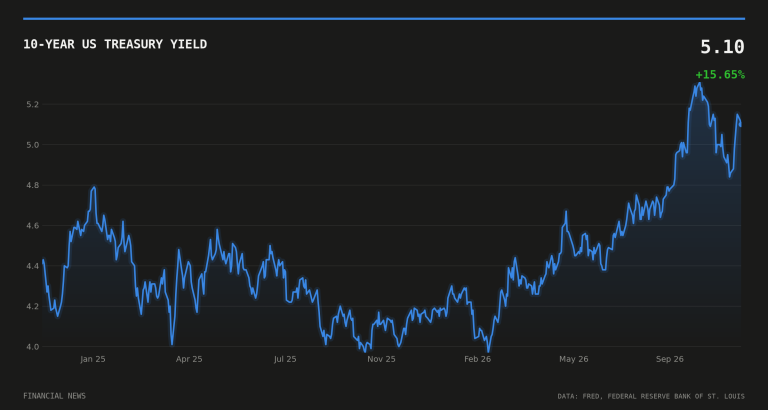
The macro backdrop offered little shelter for growth-stock disappointments. The 10-year Treasury yield stood at 5.1% and the two-year at 4.8% around the time of the report, per Federal Reserve Bank of St. Louis data, with the 10-year/2-year spread at 0.27 percentage points. Investing.com’s explainer described that rate environment as offering “no cushion” for companies that miss on forward guidance, even when the quarter just reported beats estimates.
A recurring-revenue story overshadowed
The 83% jump in annual recurring revenue is the detail most likely to get lost in the guidance-driven selloff. For a company whose printing hardware sits in a cyclical, capital-intensive segment, a growing subscription-style revenue base changes the quality of earnings over time, even if it did not change Wednesday’s share-price arithmetic.
Kornit’s next test is whether the Q4 guidance proves conservative or accurate. Investors will be watching the $60 million-$65 million revenue range and the 6.5%-9% adjusted EBITDA margin band the company itself set out, alongside any update on recurring-revenue growth when fourth-quarter results are reported.
This article is for information only and is not investment advice or a recommendation to buy or sell any asset. Markets move quickly; figures are correct as sourced at the time of writing. Always do your own research before making financial decisions.