

Time Out Group‘s Time Out Media arm returned to adjusted EBITDA profit in the year to 30 June, with revenue from the division rising 17% to £21m and its global monthly audience expanding 31% to around 280 million people.
The London-based group, which trades on AIM under the ticker TMO, reported group revenue of approximately £72m for the period, broadly flat on the prior year. That figure reflects the closure or franchising of several operations during the year.
Stripping those out, revenue from continuing operations rose to £61m from £55m, an increase of 11%.
Time Out Media Arm Drives the Recovery
The Media division’s return to adjusted EBITDA profitability follows a difficult prior year. Investegate records that in FY25, total group revenue was £73.2m and the company simultaneously launched an £8m placing.
Chief executive Chris Ohlund said the turnaround reflected accelerated transformation rather than a simple cyclical bounce. ‘FY26 was a year of significant operational and strategic progress,’ he said. ‘We opened three new Markets, expanding the portfolio to 13 locations worldwide, and signed new capital-light Market franchise agreements for India and Brazil.’
He added: ‘At the same time, we accelerated the transformation of Media and returned the division to adjusted EBITDA profitability. Monthly reach grew by 31% to approximately 280 million people, active registered users increased to 2.5 million and we continued to broaden revenues across direct advertising, live experiences, commerce, sponsorship and our physical Markets.’
The Media rebound was driven by sales growth in the UK and US, improved client retention, new business wins and a cost-efficiency programme, the company said.
Markets and Debt: The Other Moving Parts
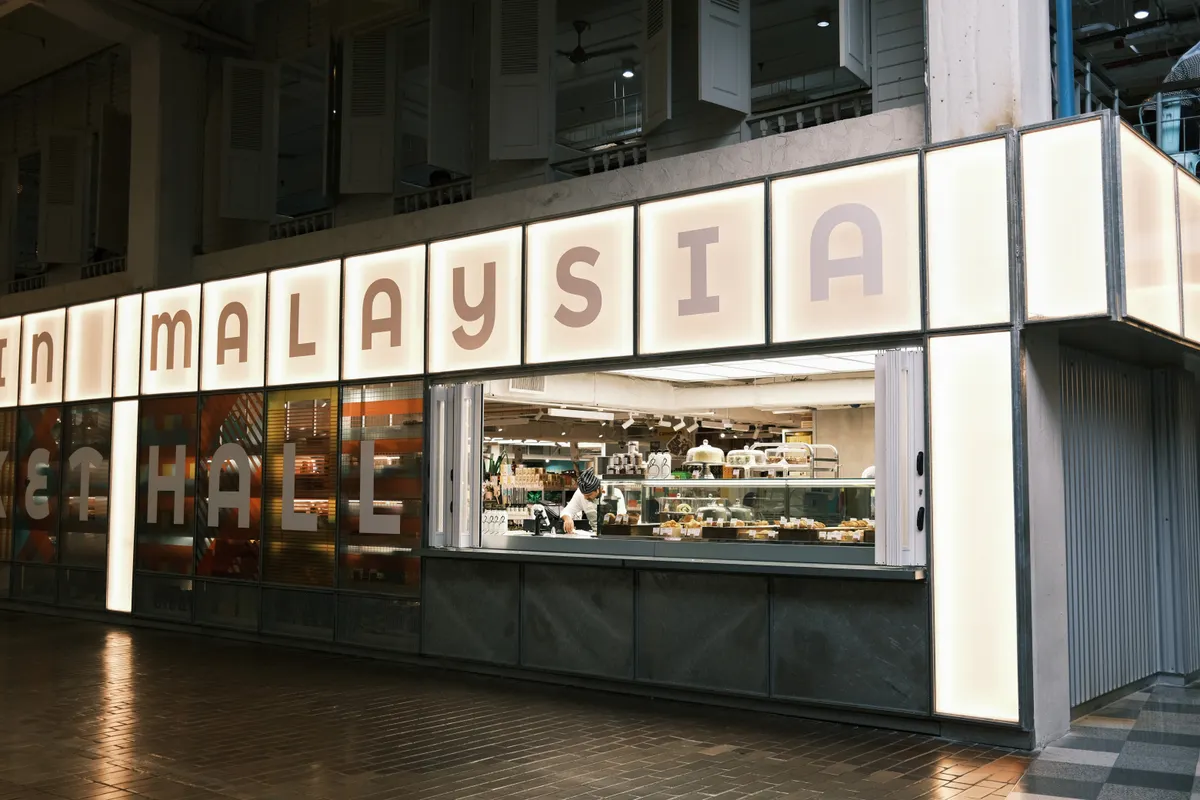
The Markets business, which operates Time Out’s food halls, lifted revenue 8% to £40m. Three new sites opened in Budapest, New York and Vancouver during the year, taking the portfolio to 13 venues and attracting 12 million visitors.
On the balance sheet, the company disclosed that the refinancing of its maturing senior debt is ongoing and progressing in line with expectations.
The debt picture has been evolving for some time. According to Time Out Group’s interim report, the company entered a loan note instrument to raise £6.0m of additional growth capital from existing shareholder Oakley Capital during the half-year period. A related facility was restructured to pay-in-kind interest at 9.5% plus three-month EURIBOR for specified quarters, reverting thereafter to cash interest at 8.5% plus three-month EURIBOR.
Separately, as part of a December 2025 placing, the company issued conversion shares to Oakley Capital in consideration for the release of £4.9m in aggregate principal. The transaction was classified as a related-party transaction under AIM Rule 13.
The franchise agreements signed for India and Brazil represent an extension of the capital-light model the company has pursued to grow the Markets brand without the full capital outlay of a company-owned site. The three company-opened sites in Budapest, New York and Vancouver show that company-operated expansion has continued in parallel.
With senior debt refinancing still to close and the Media division having delivered its first year of adjusted EBITDA profitability, the terms and structure of that refinancing will be the next concrete test of whether the operational recovery translates into an improved credit position.
