The Nscale IPO filing landed with the US Securities and Exchange Commission on 18 September 2026, with the Nvidia-backed AI infrastructure firm seeking to list on the New York Stock Exchange under the ticker NSCL.
Revenue for the six months to 30 June hit $140.6m, up 1,252% from $10.4m a year earlier, according to the S-1 prospectus. Net losses widened to $1.02bn from $368.9m, as first reported by CNBC.
Revenue soars, losses balloon
The London-headquartered company rents Nvidia (NASDAQ: NVDA) graphics processors to AI developers including OpenAI and Anthropic. Its growth curve reflects the wider scramble among “neocloud” operators to build data-centre capacity for AI training and inference.
But the scale of the losses underlines how expensive that build-out is. Nscale disclosed $56.4bn in remaining performance obligations, a measure of contracted future revenue, according to figures confirmed by Reuters. Separately, the company’s broader pipeline of active and contracted business reached $103.4bn as of 31 August, up from $38.0bn at the end of 2025, according to figures reported by Yahoo Finance.
One customer, half the revenue
More than half of first-half revenue, 52%, came from a single unnamed customer, according to Reuters reporting carried by The Business Standard. That concentration echoes a dynamic already familiar to investors in CoreWeave (NASDAQ: CRWV), the rival neocloud whose own IPO in March 2025 drew scrutiny over customer reliance.
A large chunk of Nscale’s backlog jump traces to a single deal: Anthropic agreed in August 2026 to pay $45bn to rent AI computing capacity from Nscale’s West Virginia data-centre campus, the Business Standard reported. That contract now dominates the pipeline figures in the prospectus.
Nvidia’s money is already in the building
Nvidia holds a stake of more than 5% in Nscale through non-voting shares issued in an earlier financing round, according to Bloomberg reporting carried by Yahoo Finance. The chipmaker has also gone further this week, agreeing to buy $1bn of a $3.1bn convertible bond issue from Nscale, the Business Standard reported.
Goldman Sachs, J.P. Morgan and Morgan Stanley are lead bookrunners on the offering, according to Pulse2. Nscale is targeting a valuation of roughly $30bn and aims to raise up to $3bn, per Reuters coverage cited by the Business Standard.
The company’s board carries recognisable names from Big Tech’s front office: former Meta executives Sheryl Sandberg and Nick Clegg both sit on it, according to Yahoo Finance.
A crowded queue of AI listings
Nscale would become the third pure-play AI neocloud to go public in roughly 18 months, following Nebius Group in October 2024 and CoreWeave in March 2025, according to ECM Source. Each has tested investor appetite for capital-hungry infrastructure bets tied to AI demand that has yet to prove durable beyond a handful of large buyers.
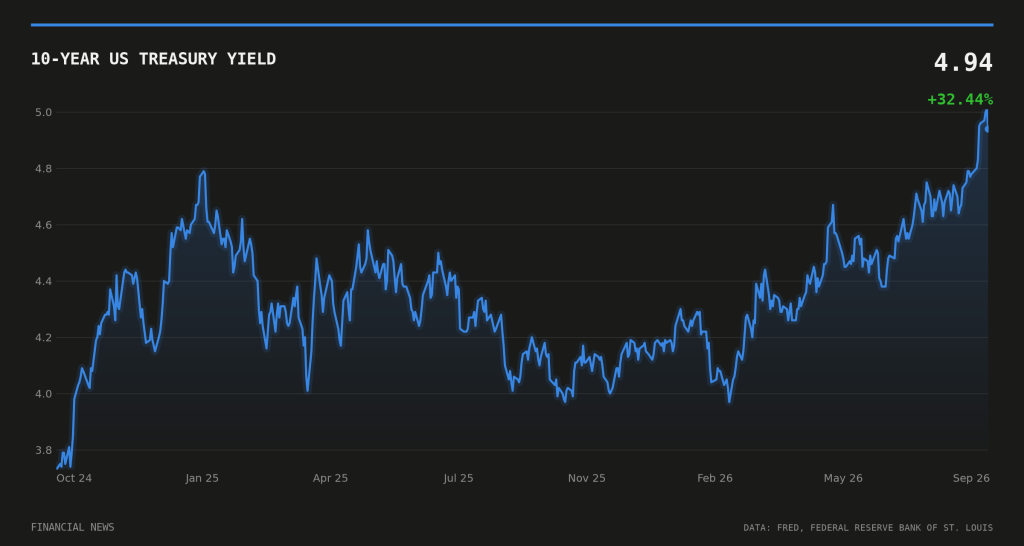
The filing arrives against a moderate-rate backdrop: the 10-year US Treasury yield stood at 4.94% on 17 September, against 4.67% for the 2-year, according to FRED data from the Federal Reserve Bank of St Louis. Borrowing costs at that level still matter for a company burning through cash at Nscale’s pace.
Same-week SEC filings also showed a cluster of routine Form 4 disclosures from Nvidia executives, including chief executive Jensen Huang and finance chief Colette Kress, alongside insider filings at CoreWeave and Dell Technologies (NYSE: DELL). None of those filings relate to the Nscale investment.
Nscale has not disclosed a pricing date. Investors will now turn to the roadshow and any updated prospectus filings for detail on how the company plans to narrow losses that, on current figures, run roughly seven times its half-year revenue.
This article is for information only and is not investment advice or a recommendation to buy or sell any asset. Markets move quickly; figures are correct as sourced at the time of writing. Always do your own research before making financial decisions.