
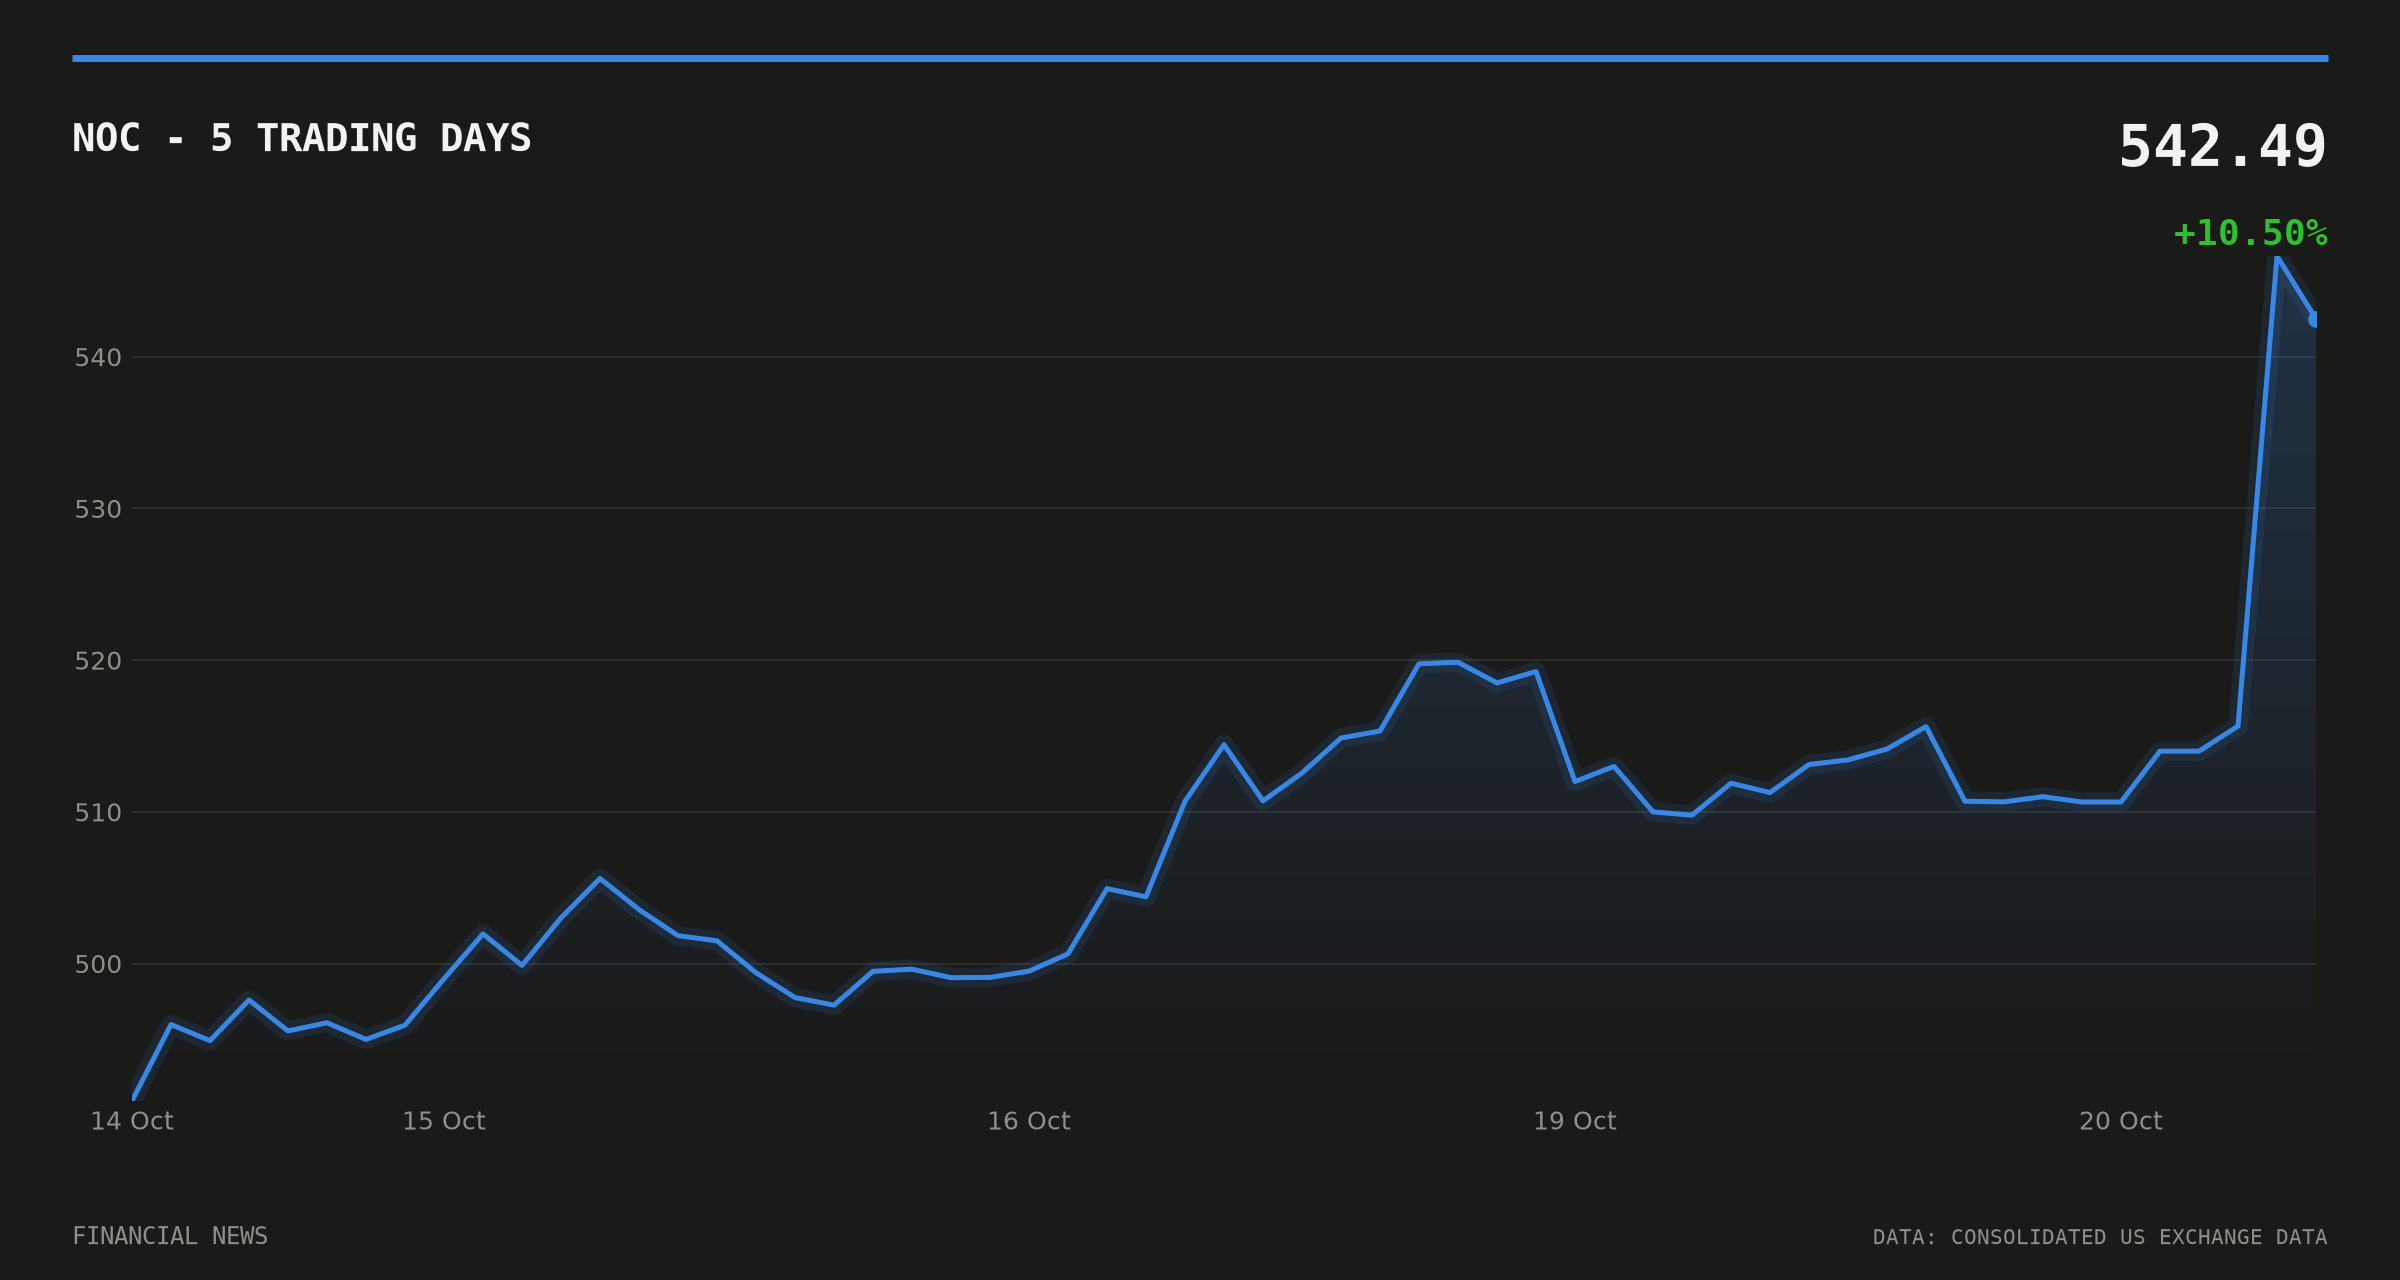

Northrop Grumman (NYSE: NOC) raised its full-year profit guidance on 20 October 2026 after a third-quarter earnings beat driven by a record order backlog.
The defence contractor lifted its 2026 earnings-per-share guidance to $29.35-$29.75, up from $28.60-$29.10, after posting diluted EPS of $7.89 for the quarter, against a consensus estimate of $7.18, according to Investing.com.
Record backlog drives the Northrop Grumman guidance raise
The company reported a book-to-bill ratio of 1.5x for the quarter, with net awards of $16bn pushing its backlog to a record $110bn, according to its earnings release filed with the SEC.
Quarterly sales rose 7% to $11.1bn, with a segment operating margin rate of 12.1%, as MarketScreener reported. That figure was marginally below the $11.12bn analysts had pencilled in, according to GuruFocus, making this an earnings and margin story rather than a top-line one.
Northrop also raised segment operating income guidance by $65m at the midpoint, to a range of $4.94bn-$5.04bn, Reuters reported via Investing.com. Full-year revenue guidance held at $43.75bn-$44.25bn, the Associated Press reported, citing the company’s own figures carried by WTOP.
Shares jump on the print
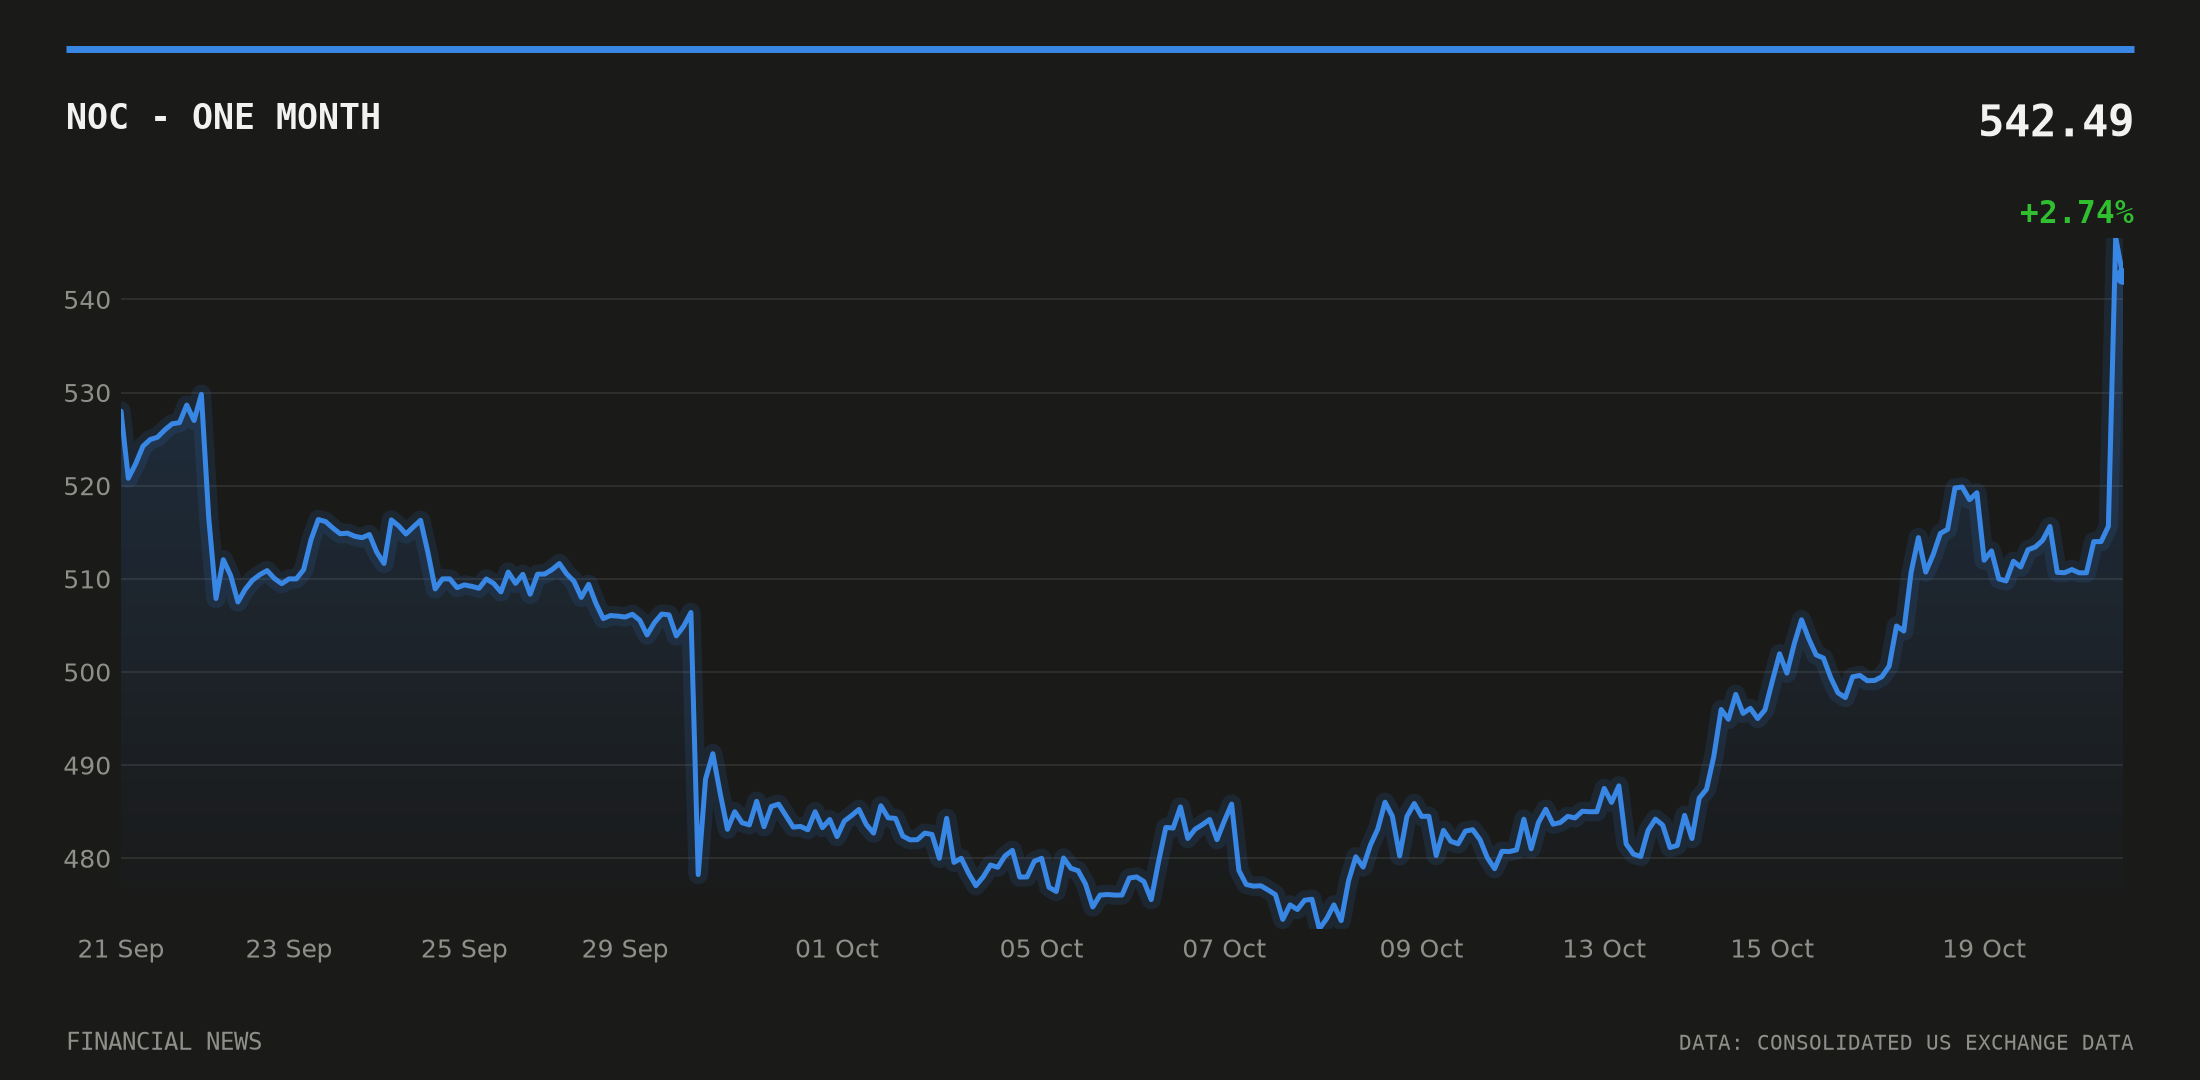
NOC shares rose 7.2% intraday, trading as high as $545.44, according to MarketBeat. Separate exchange data put the stock at $541.85 as of mid-morning trading, up 6.04% on the day and 7.24% over 20 sessions, with volume running 23% above its 20-day average.
Growth in the quarter was led by a 14% increase at the Aeronautics Systems unit, Reuters reported via Investing.com. Chief executive Kathy Warden tied the raised outlook directly to the record backlog and the group’s portfolio positioning, according to the same report.
2027 growth target follows the backlog build
Management guided to sales growth of 5%-7% in 2027, with further acceleration expected in 2028, according to the company’s third-quarter earnings call transcript. Executives pointed to the Sentinel programme and a satellite-launch schedule as drivers of that outlook, alongside continued investment in space systems, munitions and autonomous systems.
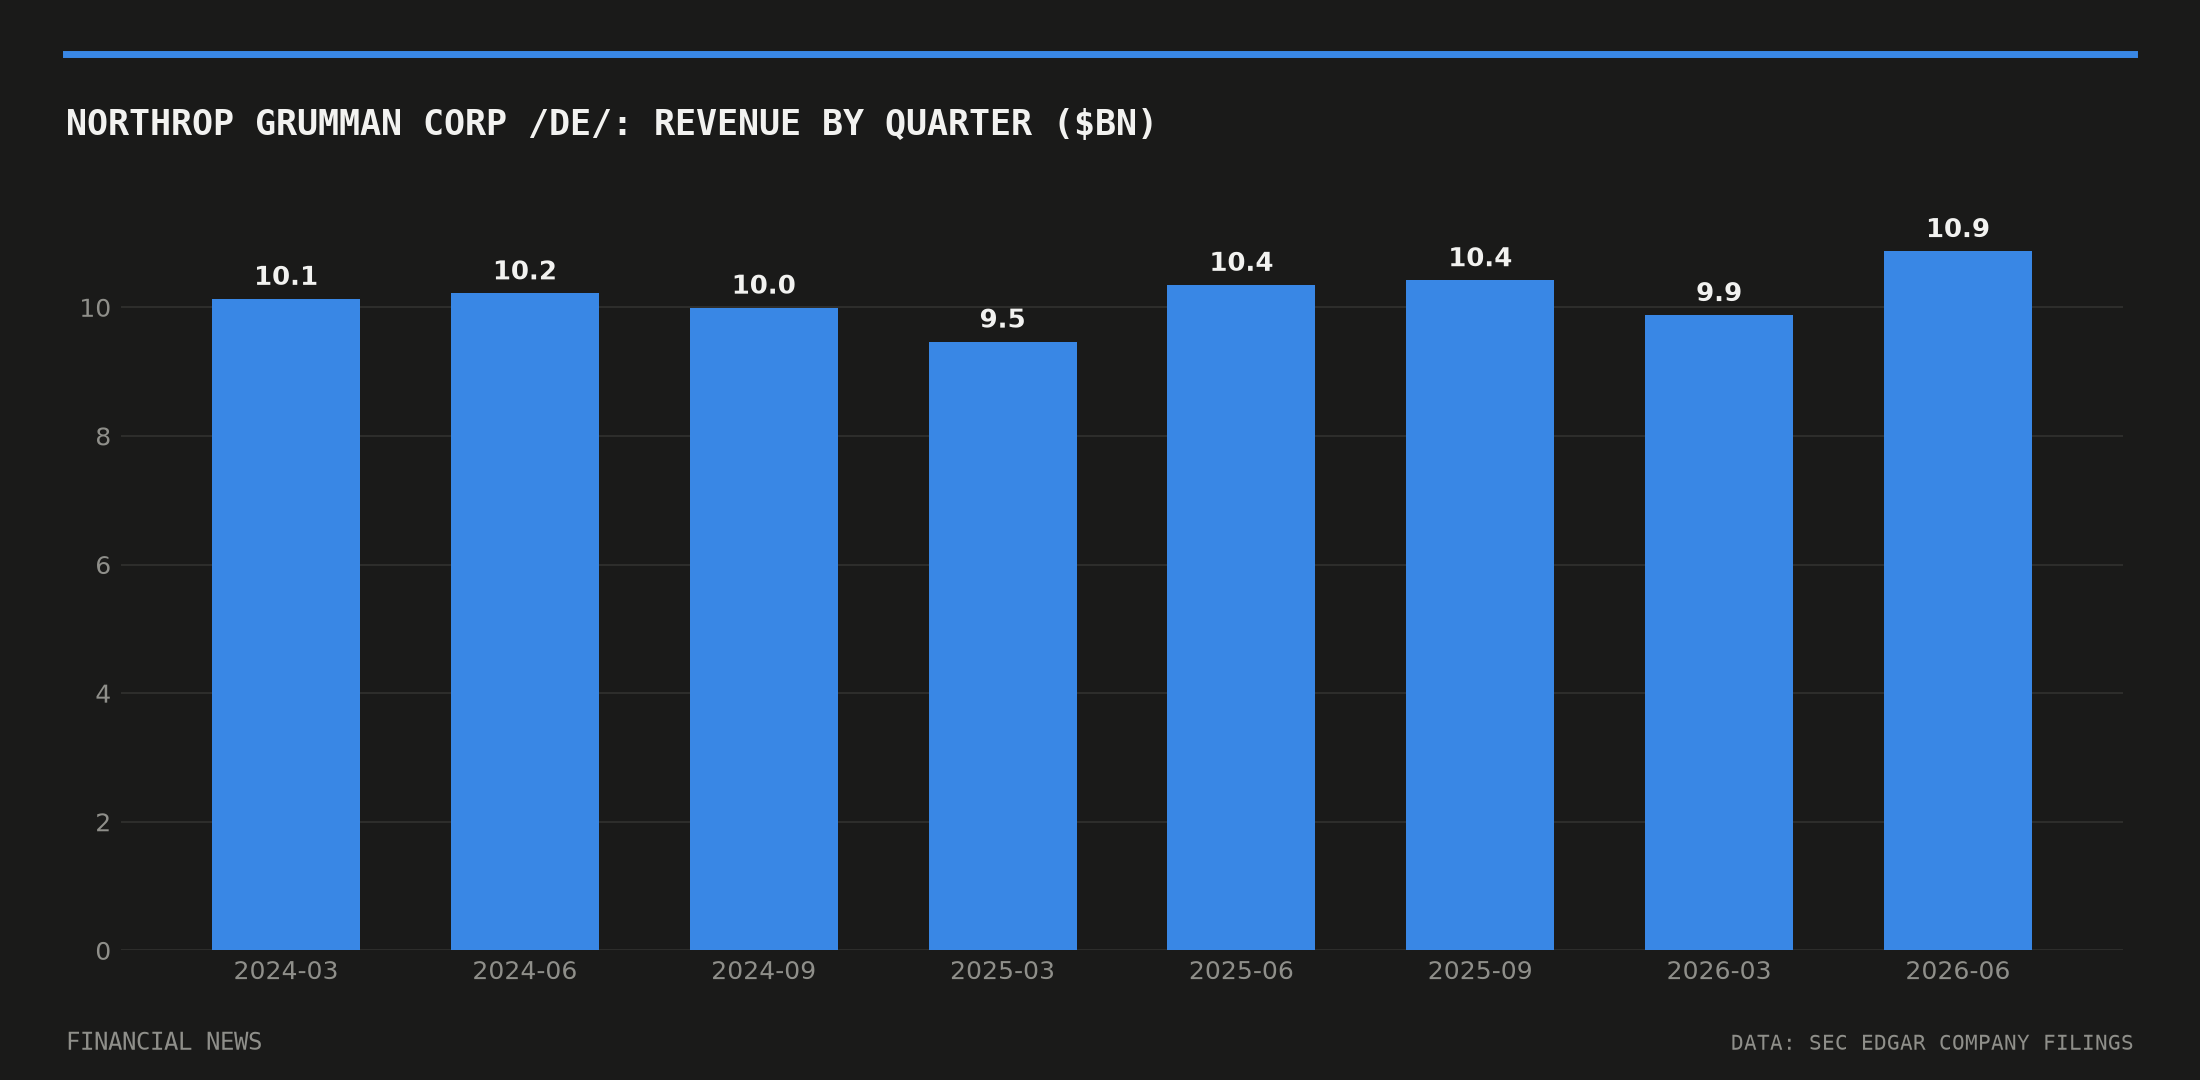
The guidance raise follows a run of improving quarters. Northrop’s diluted EPS climbed from $6.14 in the first quarter of 2026 to $7.68 in the second, on revenue of $10.876bn, according to a 10-Q filed with the SEC in July. Net income over that same second quarter came to $1.094bn, up from $875m in the first quarter, filings show. The third-quarter net income figure of roughly $1.12bn, reported by the Associated Press, extends that upward trajectory.
The improvement also marks a recovery from a weaker patch a year earlier. Northrop’s first-quarter 2025 net income came in at $481m, roughly half the levels seen either side of it, before rebounding to $1.174bn in the second quarter of 2025 and $1.1bn in the third, according to the company’s quarterly SEC filings. Quarterly revenue across that period ranged between $9.468bn and $10.423bn, filings show, putting the latest $11.1bn print at the top of the recent range.
Positioning and the rate backdrop
Short interest in NOC had eased into the print. FINRA data show the daily short-sale ratio falling from 0.469 on 7 October to 0.348 on 19 October, the day before results, according to FINRA’s short-sale volume data.
The earnings beat also landed against a backdrop of elevated borrowing costs. The 10-year US Treasury yield stood at 5.09% on 16 October 2026, according to FRED data from the Federal Reserve Bank of St. Louis, a level that has kept investors scrutinising cash generation and dividend coverage at industrial and defence names. The US unemployment rate ticked up to 4.2% in September, from 4.1% the prior month, separate FRED data show, a labour-market shift some investors have watched alongside federal spending commitments to defence contractors.
Northrop’s next scheduled update will be its fourth-quarter results, when the company is expected to confirm whether the raised 2026 guidance range holds and to detail progress toward the 5%-7% sales growth it has flagged for 2027.
This article is for information only and is not investment advice or a recommendation to buy or sell any asset. Markets move quickly; figures are correct as sourced at the time of writing. Always do your own research before making financial decisions.
