

Northern Trust (NASDAQ: NTRS) reported sharply higher third-quarter earnings on 21 October 2026, with net income climbing to $642.9m from $457.6m a year earlier. Diluted earnings per share rose to $3.40 from $2.29, according to the firm’s 8-K filing with the SEC.
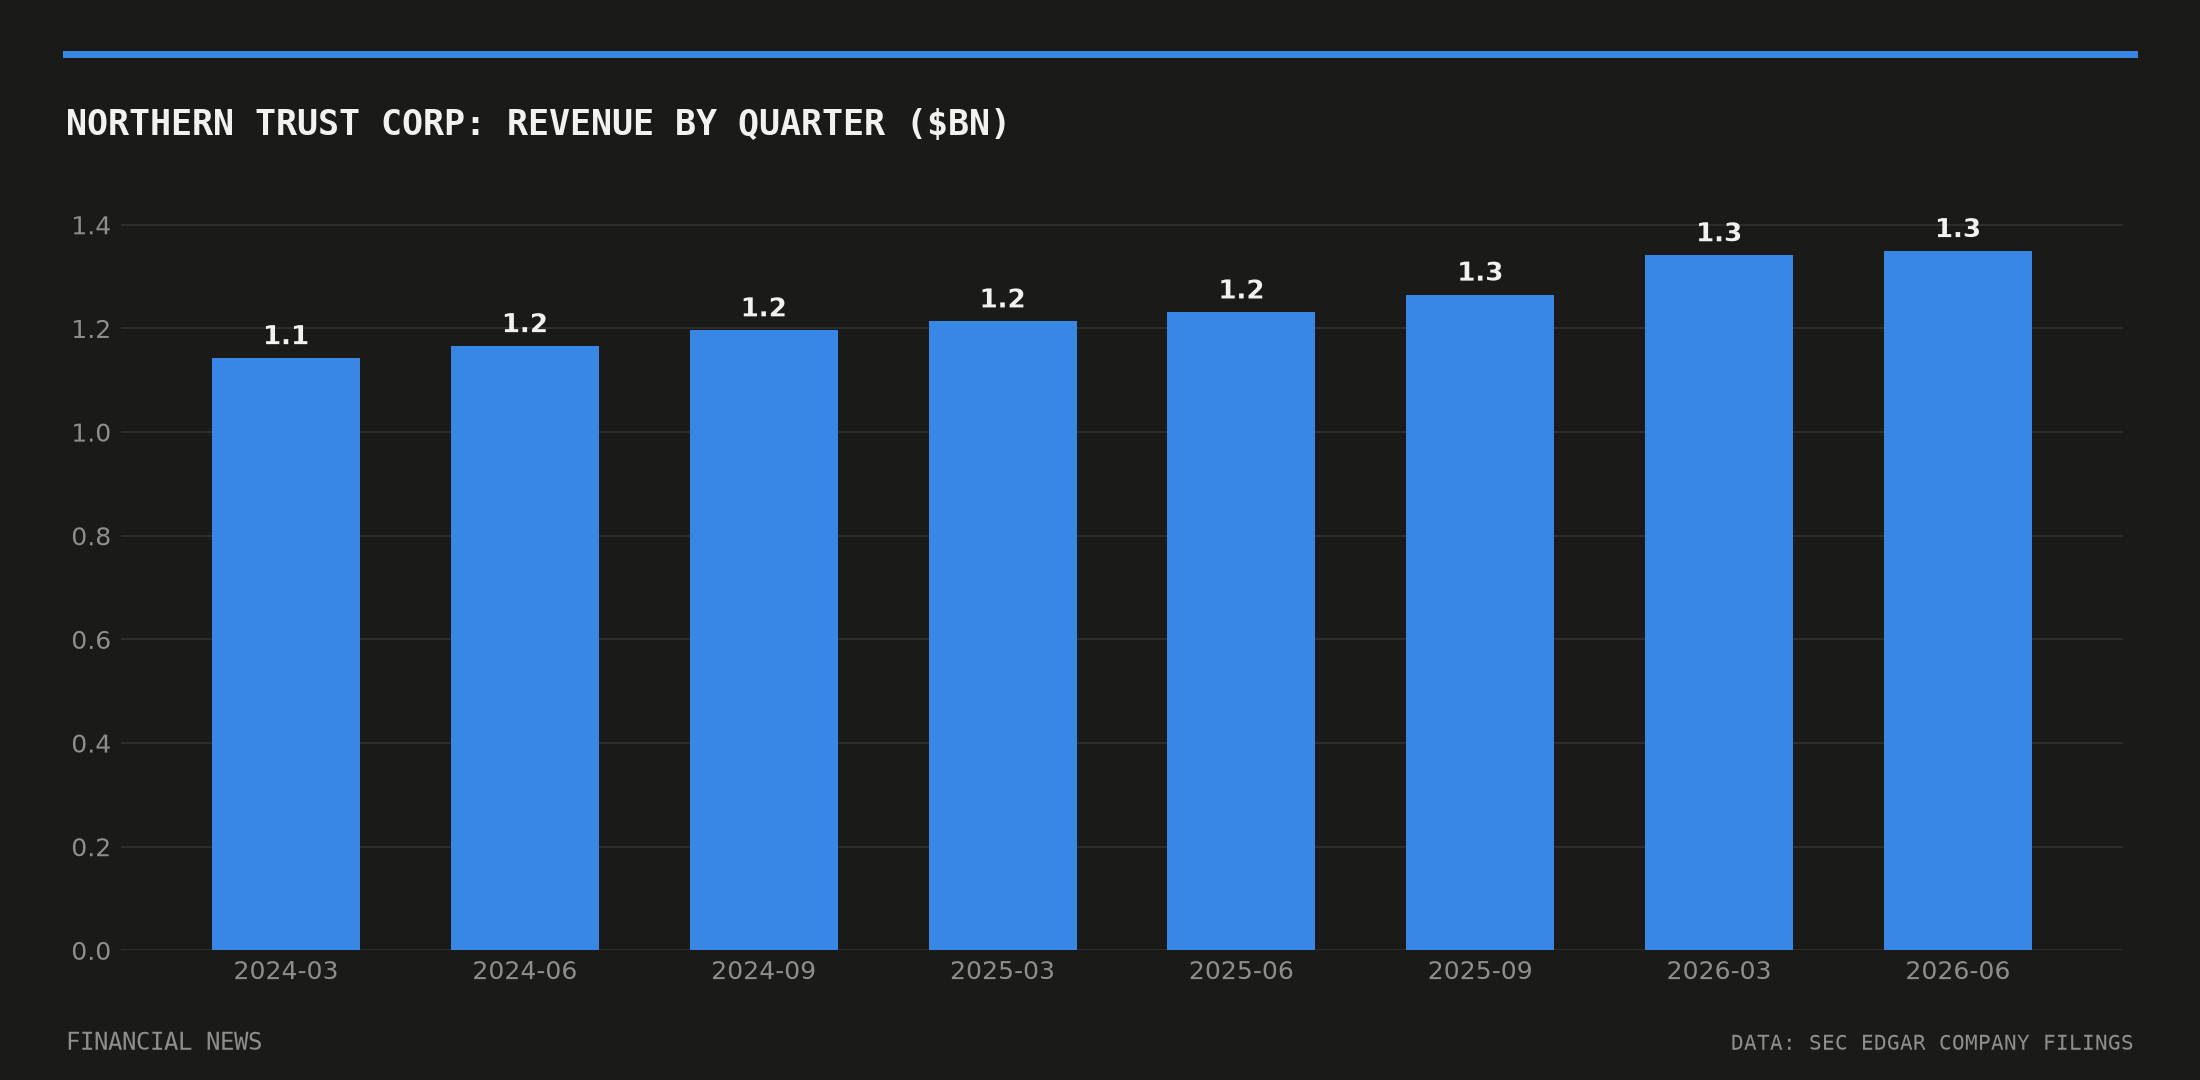
That is a roughly 40% year-on-year increase in net income, as The Motley Fool noted from the earnings call. Revenue on a fully taxable-equivalent basis reached $2,302.1m, up 13% from the same quarter last year, according to the trust bank’s financial highlights presentation filed alongside the results.
Northern Trust Q3 earnings beat forecasts
Adjusted EPS of $3.20 beat the Zacks Consensus Estimate, with the gain attributed to higher net interest income and growth in assets under management, according to Zacks Investment Research. Analysts had pencilled in EPS of $2.87 on revenue of $2.26bn ahead of the report, according to a MarketBeat preview, making the print a comfortable beat on both lines.
Despite the scale of the beat, shares barely moved. Northern Trust closed at $166.91, down 0.38% on the day, having traded near $165.52 earlier in the session, according to Investing.com. The stock sits 2.75% below its 20-day high of $171.63 and well above its 20-day low of $159.96.
Quarterly net income has swung sharply before
Northern Trust’s quarterly profit has been uneven over the past two years, a pattern that complicates simple year-on-year reads. Net income spiked to $896.1m in the second quarter of 2024 before settling to $464.9m the following quarter, SEC filings show. More recently, the bank posted $792.2m in net income in the second quarter of 2026, nearly double the $525.5m recorded in the first quarter of that year.
Revenue has moved more steadily. Fee-based revenue, measured under the RevenueFromContractWithCustomerExcludingAssessedTax tag and excluding net interest income, rose from $1,196.6m in the third quarter of 2024 to $1,265.5m in the third quarter of 2025, then to $1,349.5m in the second quarter of 2026 – a trajectory that has tracked the broader climb in assets under custody and management at the Chicago-based trust bank.
One data write-up from GuruFocus described the same $3.40 EPS figure as a miss against a $3.40 estimate – an internally inconsistent framing not corroborated by other outlets covering the results.
Rates backdrop and positioning
The report landed against a rising-rate backdrop that matters directly for a trust bank’s net interest income. The 10-year Treasury yield rose to 5.15% on 19 October from 5.09% previously, according to data from the Federal Reserve Bank of St. Louis. The 2-year yield edged up to 4.77% from 4.74% over the same stretch, narrowing the 10-year/2-year spread to 0.33 percentage points from 0.38.
Positioning data also pointed to elevated attention ahead of the print. FINRA’s daily short-sale volume ratio for NTRS climbed from 0.259 on 8 October to 0.622 on 20 October, the session before earnings, before easing slightly to 0.613 on the day the results were published, according to FINRA data.
Trading volume on the day of the release ran 1.73 times the 20-day average, consistent with the heightened short-sale activity recorded in the run-up to the announcement.
Northern Trust executives discussed the results on a call that began at 9:00am Eastern time, according to a Nasdaq notice ahead of the session, with transcripts later published by Seeking Alpha and other outlets. Market participants will next watch whether the bank’s forward guidance, discussed on that call, can sustain the pace of fee and net interest income growth seen through the first three quarters of 2026.
This article is for information only and is not investment advice or a recommendation to buy or sell any asset. Markets move quickly; figures are correct as sourced at the time of writing. Always do your own research before making financial decisions.
