

Prologis (NYSE: PLD) reported third-quarter 2026 results on 15 October, posting net earnings per diluted share of $0.86, up from $0.82 a year earlier.
The company also cut its full-year 2026 net earnings guidance to $4.05-$4.15 per diluted share, down from $4.40-$4.55, even as it narrowed Core FFO guidance to $6.25-$6.29, according to the company’s release.
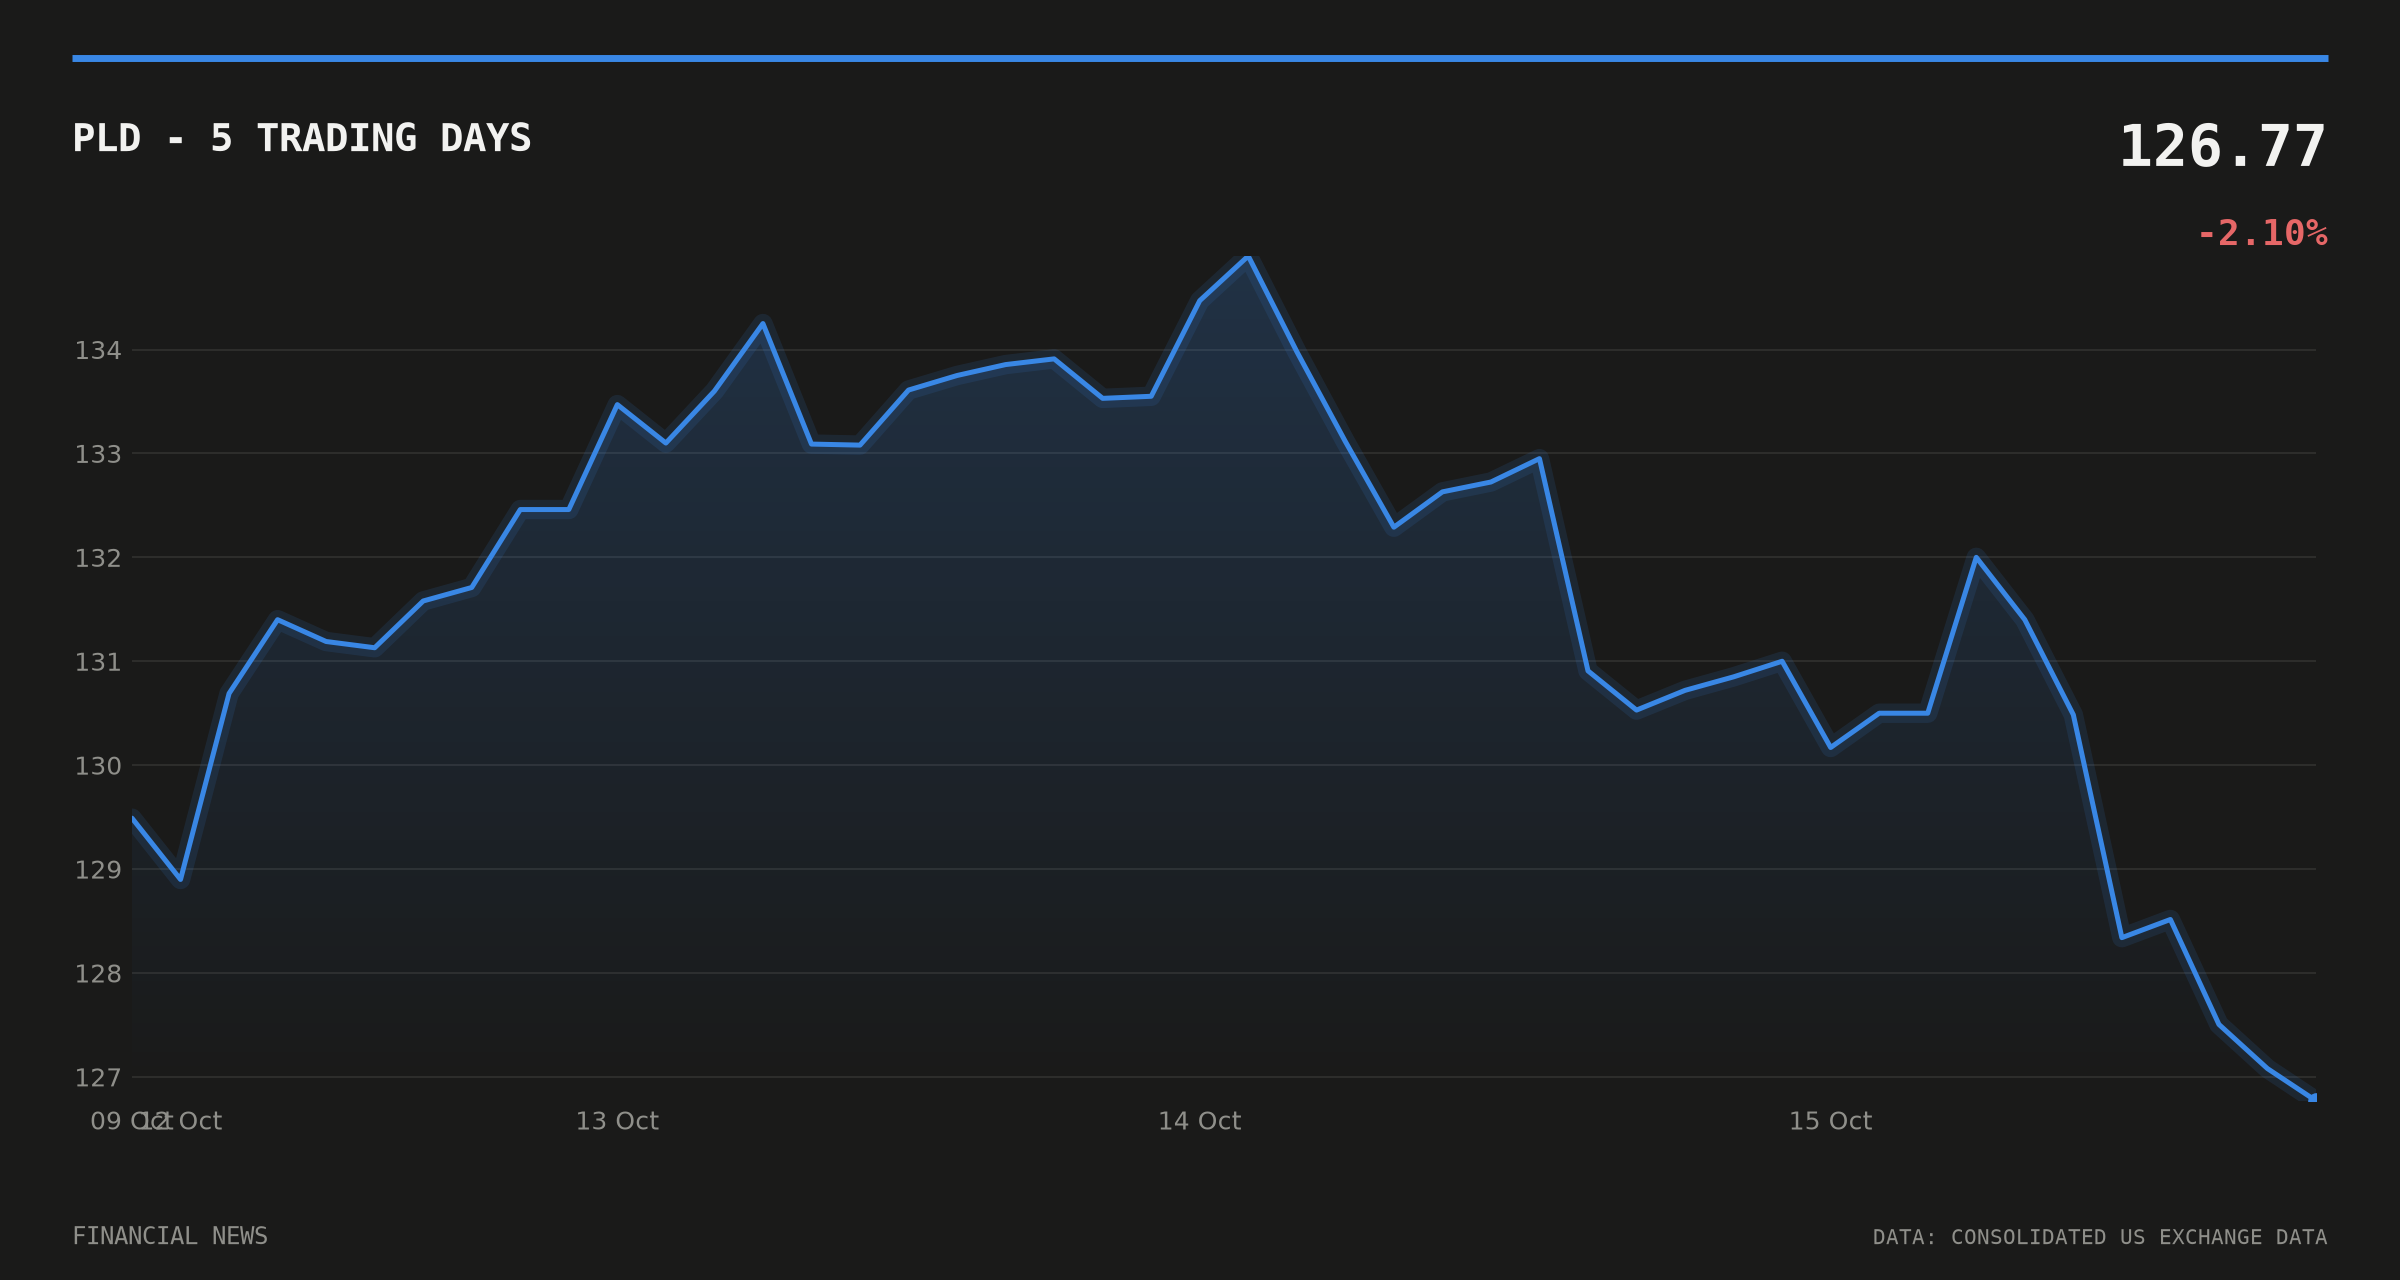
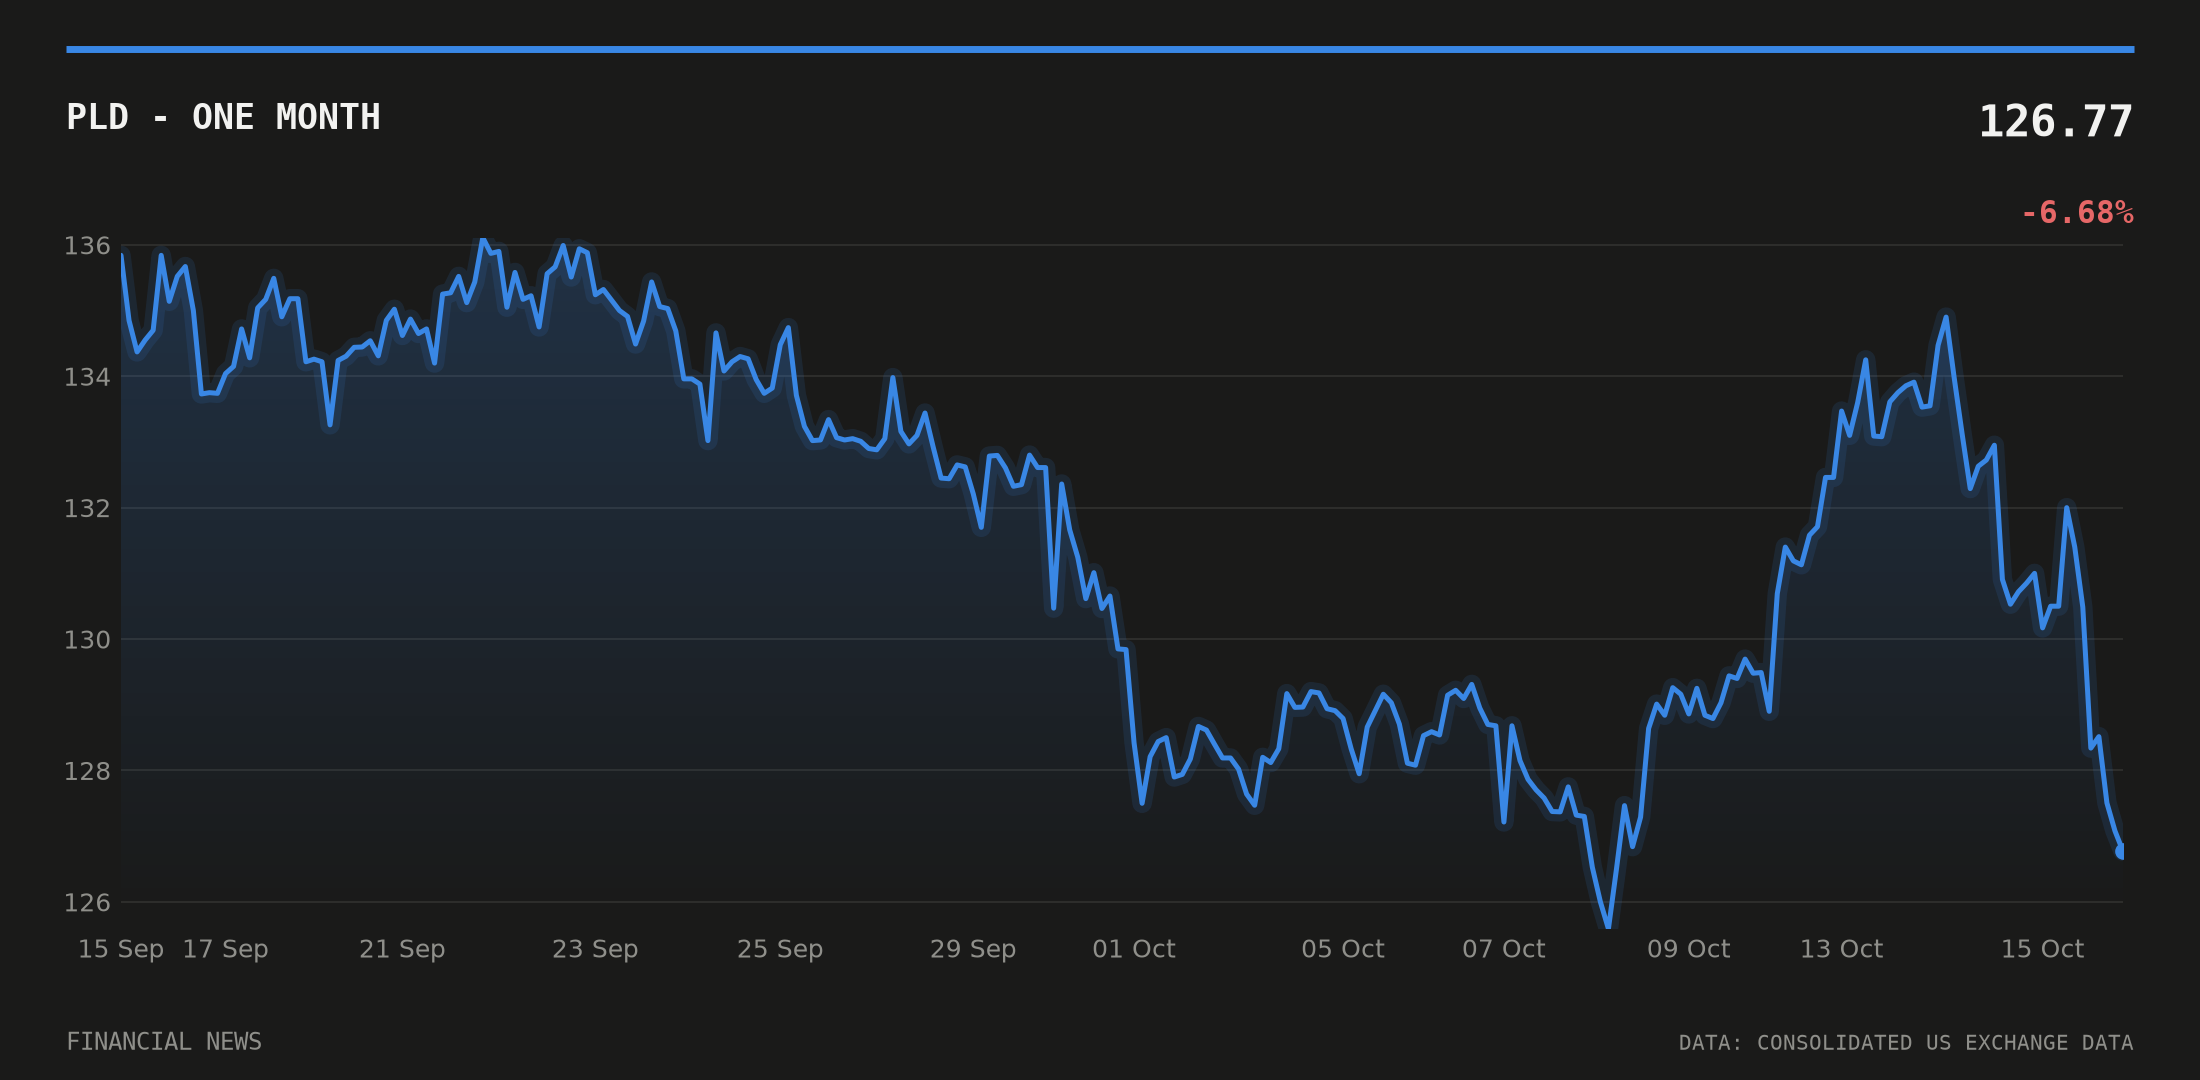
Shares fell 3.8% on the day to $126.985, extending a 5.11% decline over the prior 20 trading sessions, according to consolidated US exchange data. The stock had already slipped in premarket trading to $127.50 from a prior close of $130.46, despite beating on both headline metrics, as first reported by Investing.com.
Core FFO and revenue both climbed
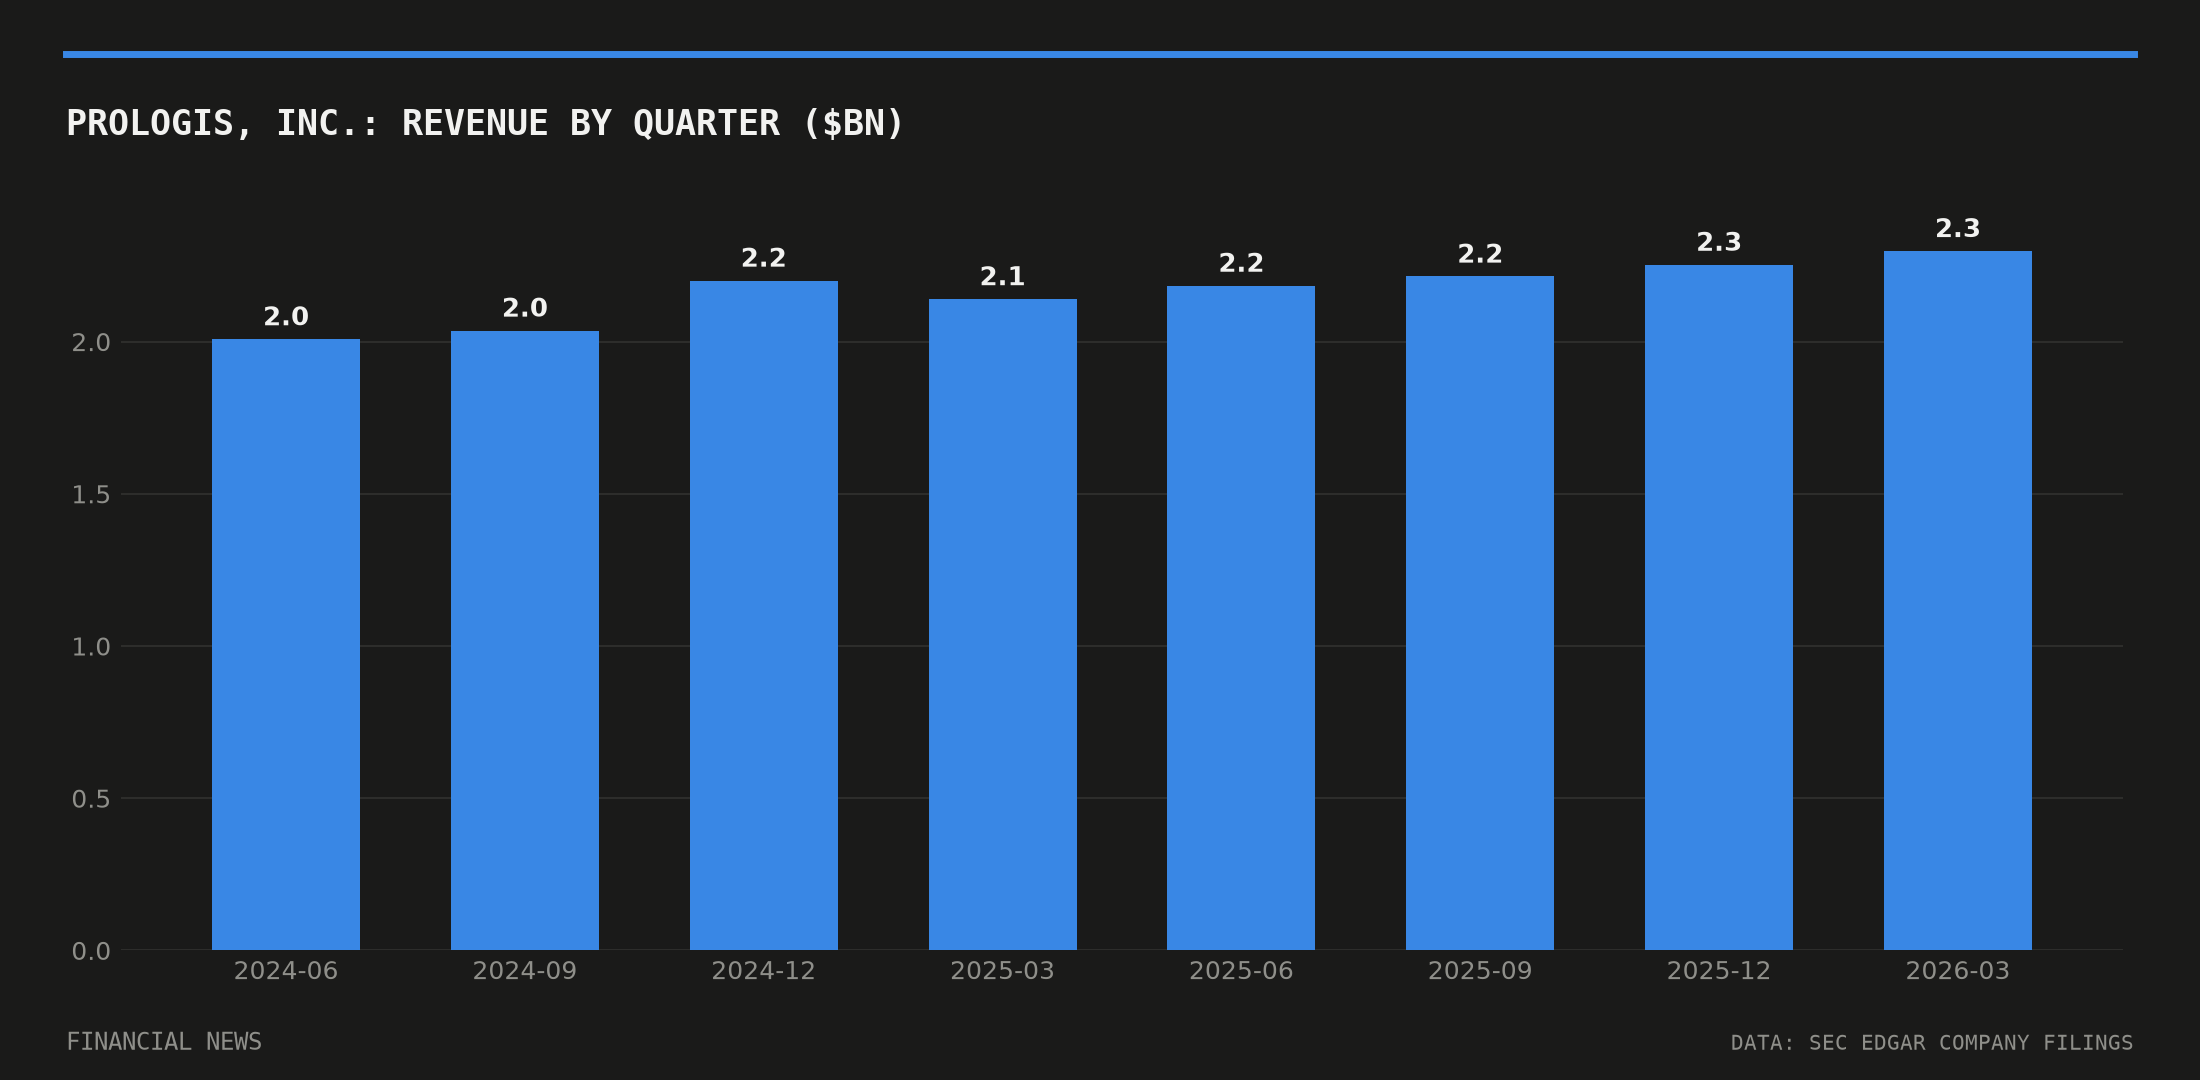
Core FFO per diluted share reached $1.60, up from $1.49 in the same quarter last year, the logistics landlord said in its filing with the SEC. Total revenue rose to $2,388m from $2,214m a year earlier, a 7.9% increase, Investing.com reported, while net earnings attributable to common stockholders climbed 6.9% to $816m.
Prologis signed 60 million square feet of leases during the quarter and announced nearly $2.3bn of transactions, the company said in its earnings release. Management told investors that replacement cost rents now sit roughly 27% above current market levels, a gap it said leaves room for further rent growth before new supply becomes economically viable, according to Investing.com’s transcript of the earnings call.
The quarter also marked a structural shift for the group. SEGRO shareholders approved a combination with Prologis, expanding the company’s European portfolio to 363 million square feet, Benzinga reported from the earnings call transcript. Not every outlet read the top-line figures the same way: one noted that rental-specific revenue of $2,224m fell short of some analyst estimates even as the headline numbers beat, a divergence that reflects different revenue-line definitions rather than any inconsistency in the figures Prologis reported.
Guidance cut lands against a stubborn rate backdrop
The reduction to net earnings guidance, even as Core FFO guidance narrowed rather than fell, points to a REIT still generating solid operating momentum while adjusting for items below the FFO line. Investors appeared to focus on the net earnings cut: shares dropped despite the EPS and Core FFO beats.
The move comes with the 10-year US Treasury yield at 5.21% as of 13 October, barely changed from 5.24% in the prior reading, according to Federal Reserve data. Elevated long-term rates have kept pressure on REIT valuations generally, since higher yields raise the discount rate applied to property income streams and make bond alternatives more competitive with dividend-paying real estate stocks.
FINRA short-sale volume data show the short-volume ratio for PLD climbing from 0.241 on 1 October to 0.627 on 14 October, the session before the results landed. The rise suggests positioning had shifted into the print, though short-volume ratios reflect the share of trading executed as short sales rather than net short interest.
What investors are watching next
Attention now turns to how quickly Prologis can integrate the enlarged European footprint following the SEGRO shareholder vote, and whether the gap between replacement cost rents and current market rents narrows or widens as new supply responds. The company’s full-year 2026 guidance range, now set at $4.05-$4.15 per diluted share for net earnings and $6.25-$6.29 for Core FFO, gives the market a fresh marker against which to judge the fourth-quarter print.
With the 10-year Treasury yield still above 5%, the key question for logistics landlords is less about operating execution and more about whether valuations can hold steady while financing costs stay elevated.
This article is for information only and is not investment advice or a recommendation to buy or sell any asset. Markets move quickly; figures are correct as sourced at the time of writing. Always do your own research before making financial decisions.
