
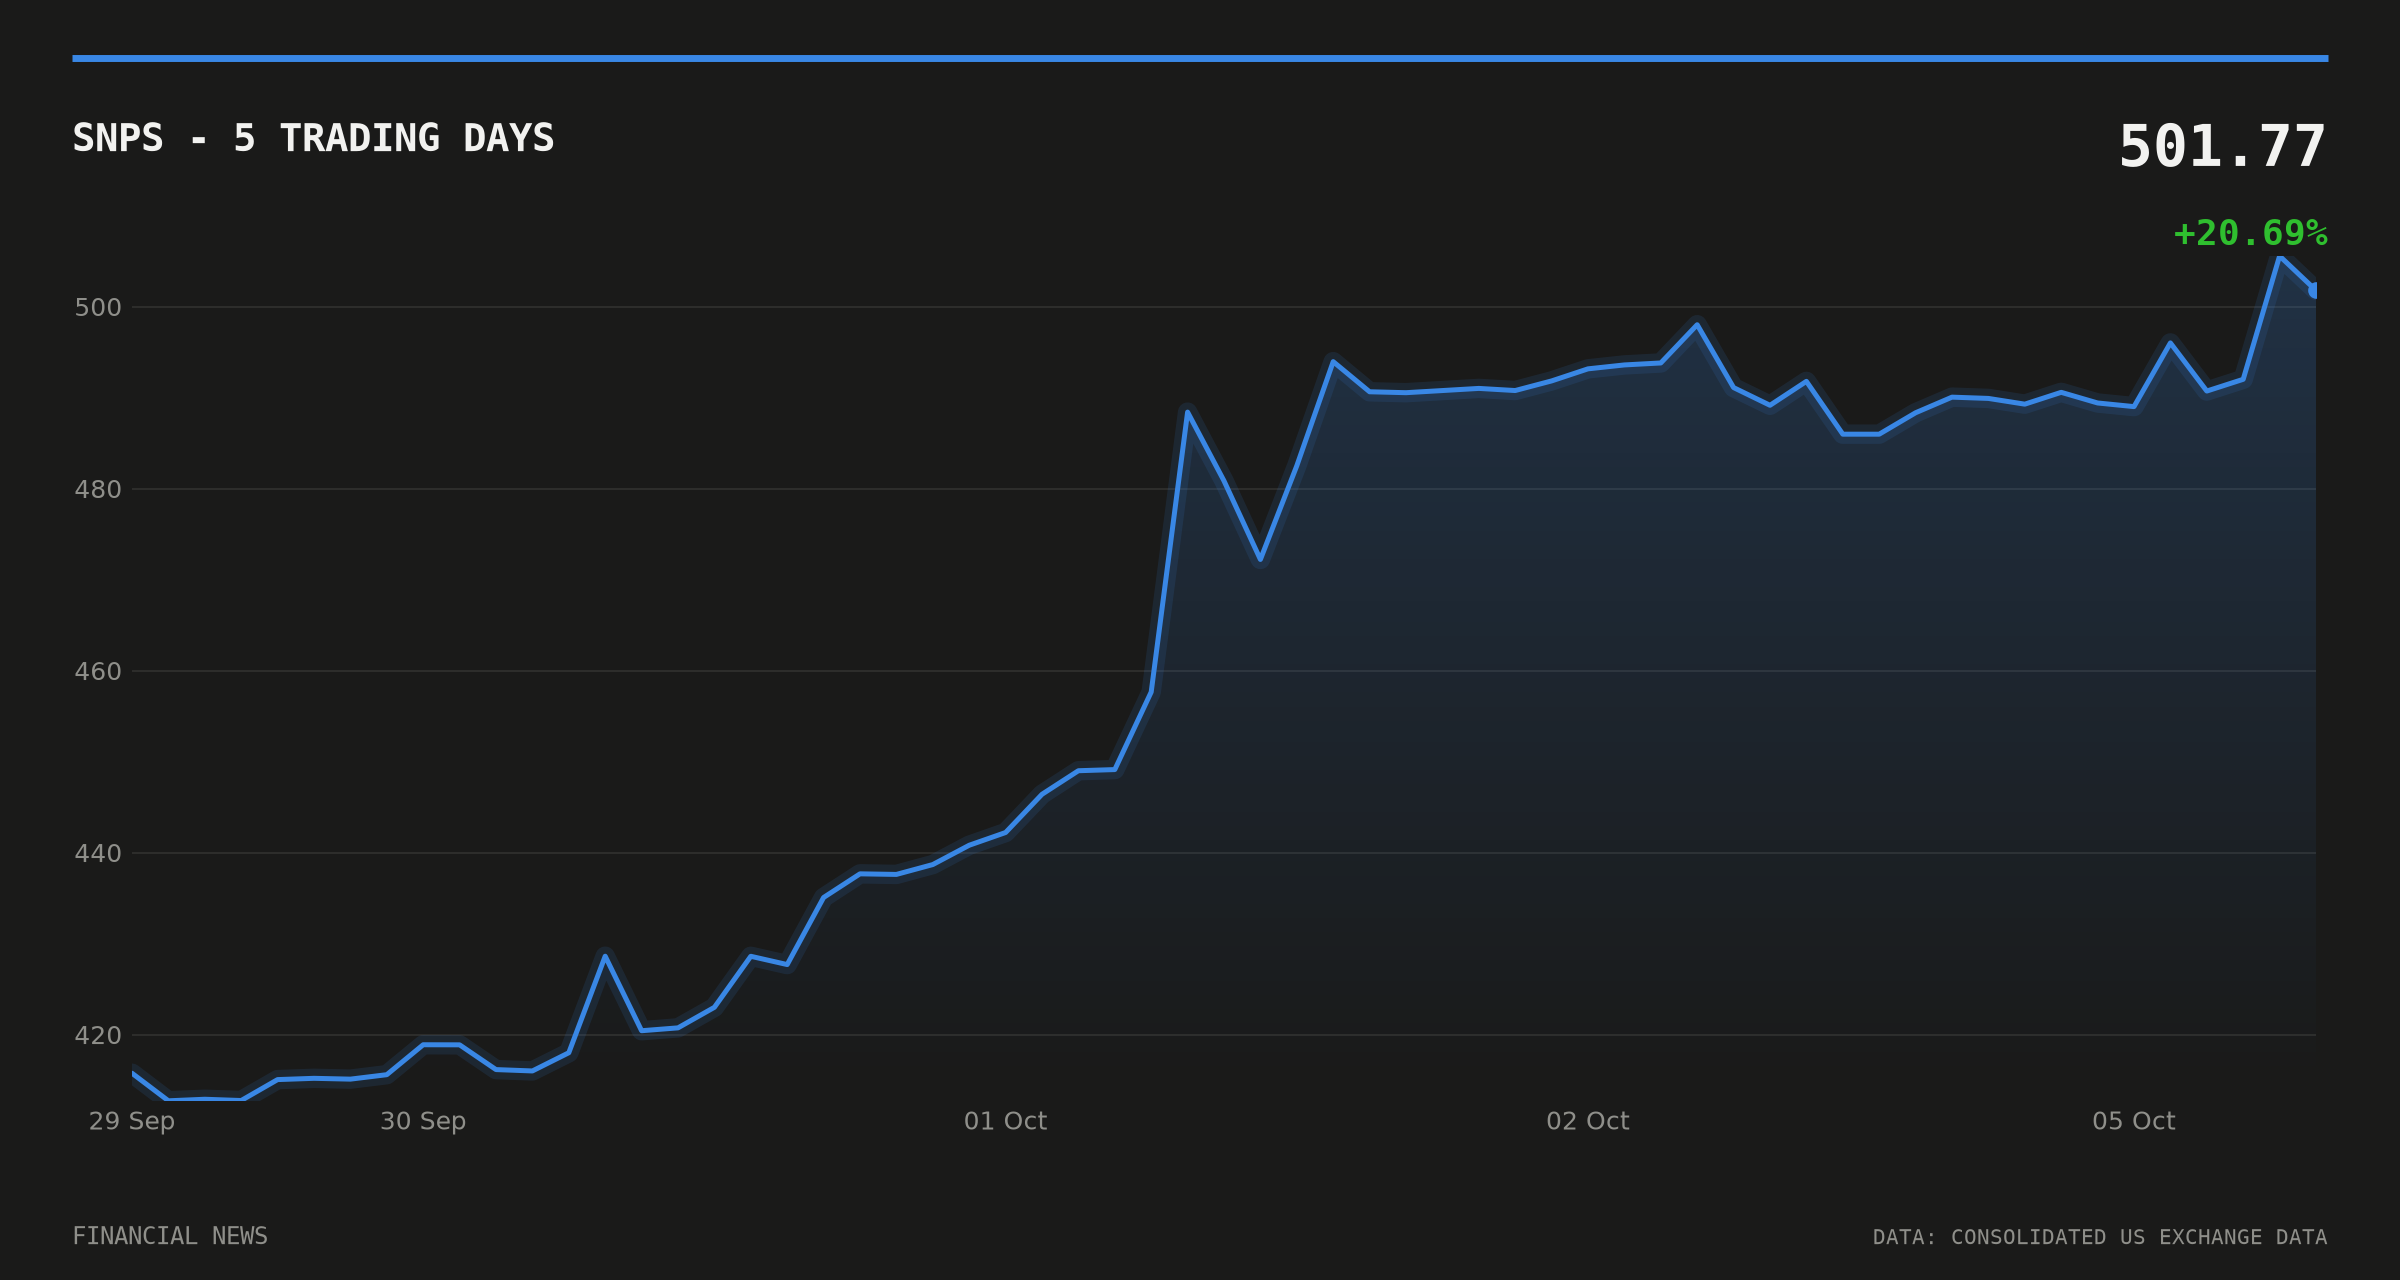

Synopsys (NASDAQ: SNPS) has entered a $1bn accelerated share repurchase agreement with JPMorgan Chase Bank, National Association, the design-software group said on 5 October 2026.
Under the deal, Synopsys will receive an initial delivery of roughly 1,735,000 shares, according to a Form 8-K exhibit filed with the SEC. Final settlement of any remaining shares is due on or before 5 January 2027.
Largest accelerated share repurchase on record for Synopsys
The $1bn accelerated share repurchase dwarfs Synopsys’s previous buyback agreements with JPMorgan, which included programmes of $200m in 2017, $125m in 2016 and $100m in both 2017 and 2020, based on historical 8-K filings. This is by some distance the company’s biggest use of the mechanism.
An accelerated share repurchase lets a company retire a large block of stock immediately, funded upfront, with the bank later adjusting the final share count against a volume-weighted average price over the settlement window. The structure typically signals confidence in near-term valuation rather than an opportunistic trickle of open-market buying.
Timing follows an Investor Day surge, not the other way round
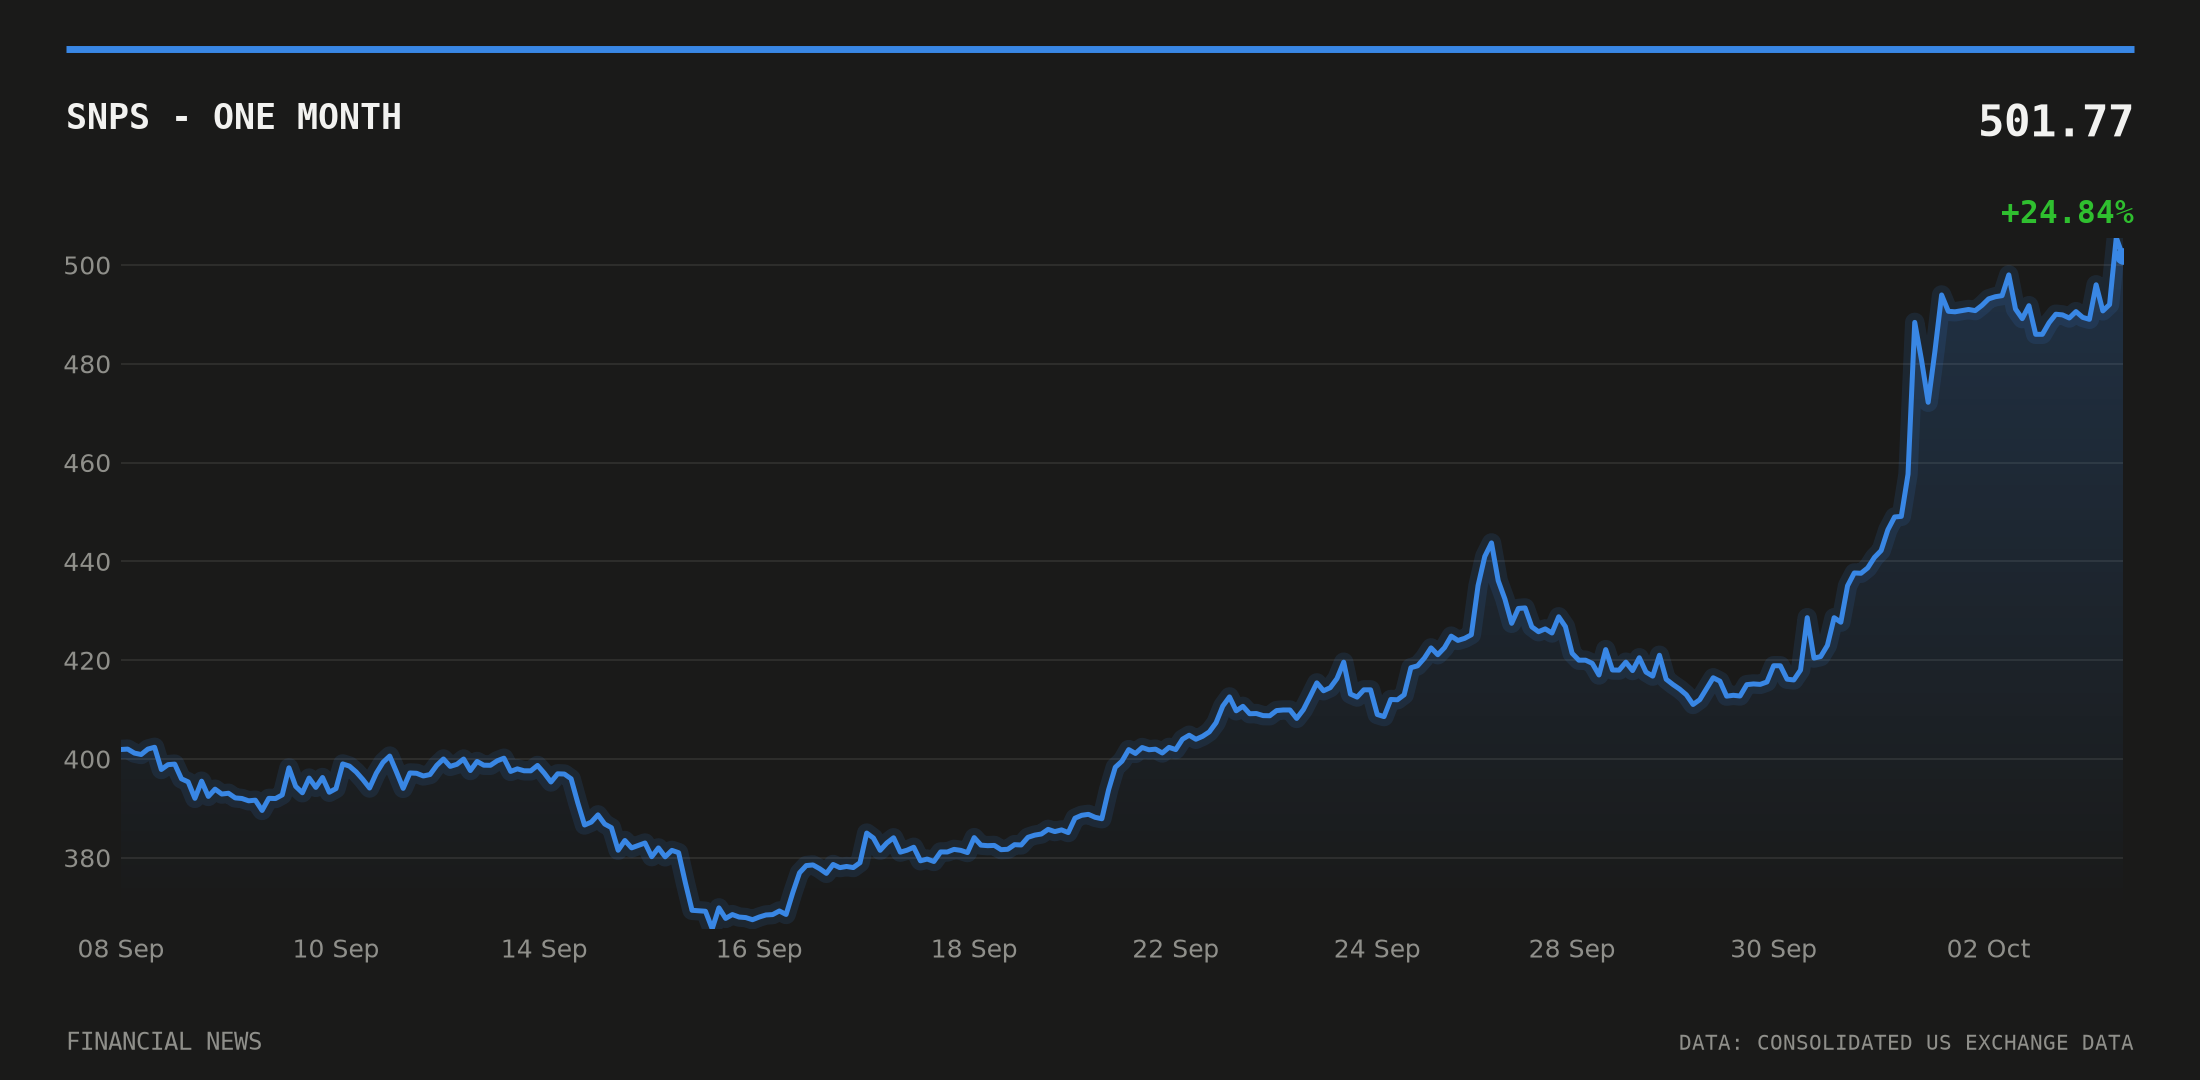
The buyback lands days after Synopsys shares jumped nearly 13% on 1 October 2026 following an Investor Day at which the company unveiled an OpenAI partnership and an Amazon custom-chip deal, alongside upgraded long-term growth targets, as reported by GuruFocus. Shares last traded at $506.41, up 3.5% on the day and up 30.98% over 20 days, against a 20-day low of $365.62.
Analysts moved price targets sharply higher around the same announcements: Rosenblatt Securities lifted its target to $620 from $575, while HSBC upgraded to Buy with a $700 target, according to Blockonomi. That leaves the buyback arriving into a stock already re-rated on the AI-royalty growth narrative, rather than driving the move itself.
Earnings volatility either side of the Ansys deal
The timing also follows a bumpy run of results since Synopsys completed its acquisition of Ansys on 17 July 2025, according to the company’s FY2025 10-K. Diluted earnings per share fell to $0.34 in fiscal first-quarter 2026 and to just $0.09 in fiscal second-quarter 2026, reflecting integration-related costs, before net income rebounded sharply to $545.8m and diluted EPS to $2.84 in fiscal third-quarter 2026, filings show.
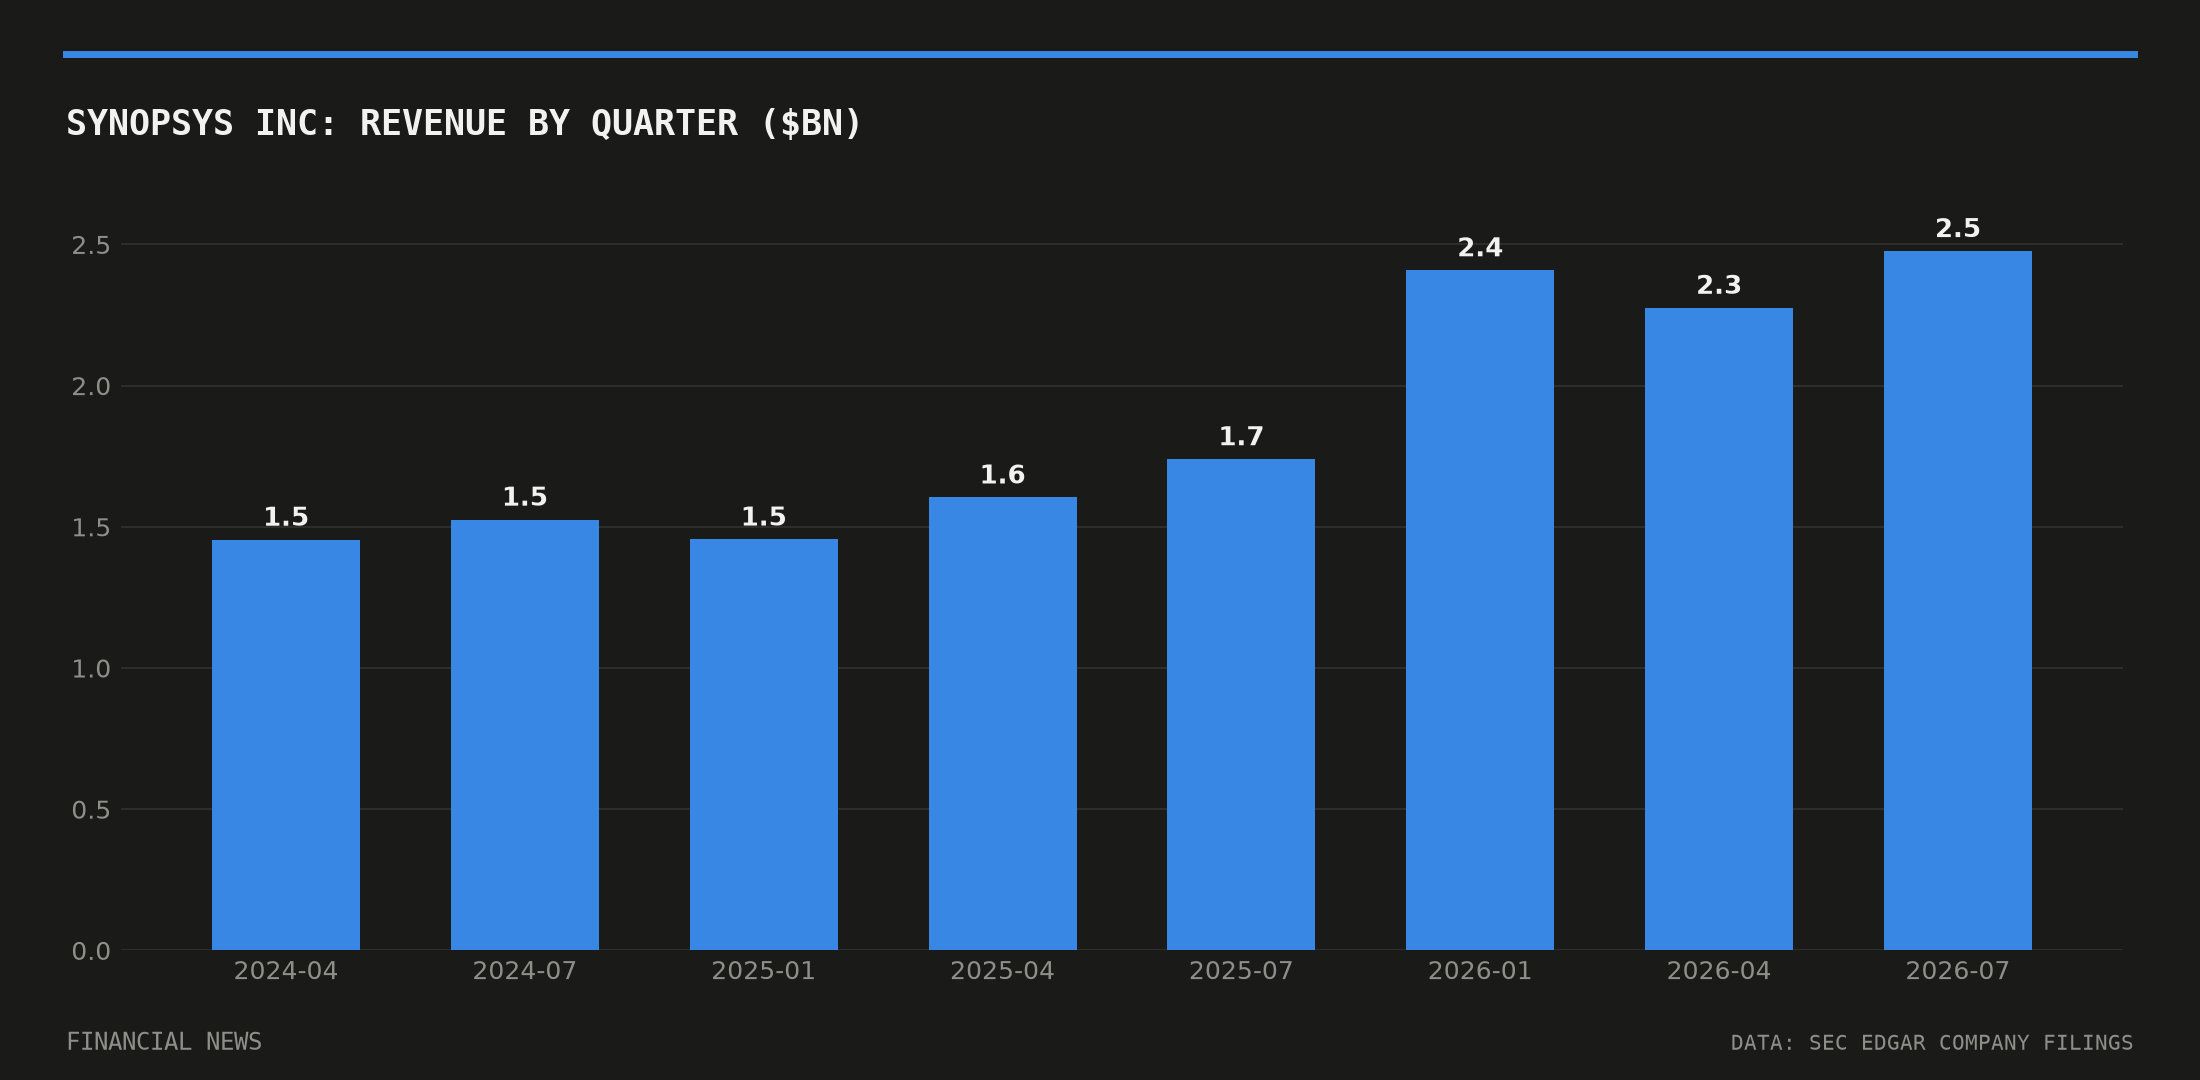
That third-quarter swing compares with net income of $242.5m and diluted EPS of $1.50 a year earlier, in fiscal third-quarter 2025, and with $408.1m net income and $2.61 diluted EPS in fiscal third-quarter 2024, according to successive 10-Q filings. Quarterly revenue has also climbed through the period, from $1.45bn in the second quarter of fiscal 2024 to $2.48bn in the third quarter of fiscal 2026, as the Ansys business layered onto the core electronic design automation franchise.
The sequence leaves the $1bn buyback looking as much like a statement of confidence in the post-Ansys earnings recovery as a routine capital-return exercise, coming only weeks after the weakest quarterly profit figures the merged group has reported.
A buyback against a still-restrictive rate backdrop
Synopsys is committing the cash into a market where the 10-year US Treasury yield stood at 5.24% and the two-year at 4.78% as of 1 October 2026, according to data from the Federal Reserve Bank of St. Louis. At those levels, a large cash-funded repurchase carries a clearer opportunity cost against debt paydown or reinvestment than it would in a lower-rate environment, even for a company flush with a rebounding earnings base.
The 10-year/2-year spread held at 0.45 percentage points, little changed from 0.46 points previously, pointing to a yield curve that has stayed only mildly upward-sloping through the announcement window. US unemployment ticked up to 4.2% in September 2026 from 4.1% the prior month, while headline CPI rose to 334.131 from 332.813, according to the same Federal Reserve data series, underscoring a macro backdrop that remains watchful on growth even as individual technology names post standout quarters.
Settlement of the remaining shares under the agreement is due on or before 5 January 2027, a date investors will watch for confirmation of the final share count once JPMorgan completes its volume-weighted average price calculation.
This article is for information only and is not investment advice or a recommendation to buy or sell any asset. Markets move quickly; figures are correct as sourced at the time of writing. Always do your own research before making financial decisions.
