
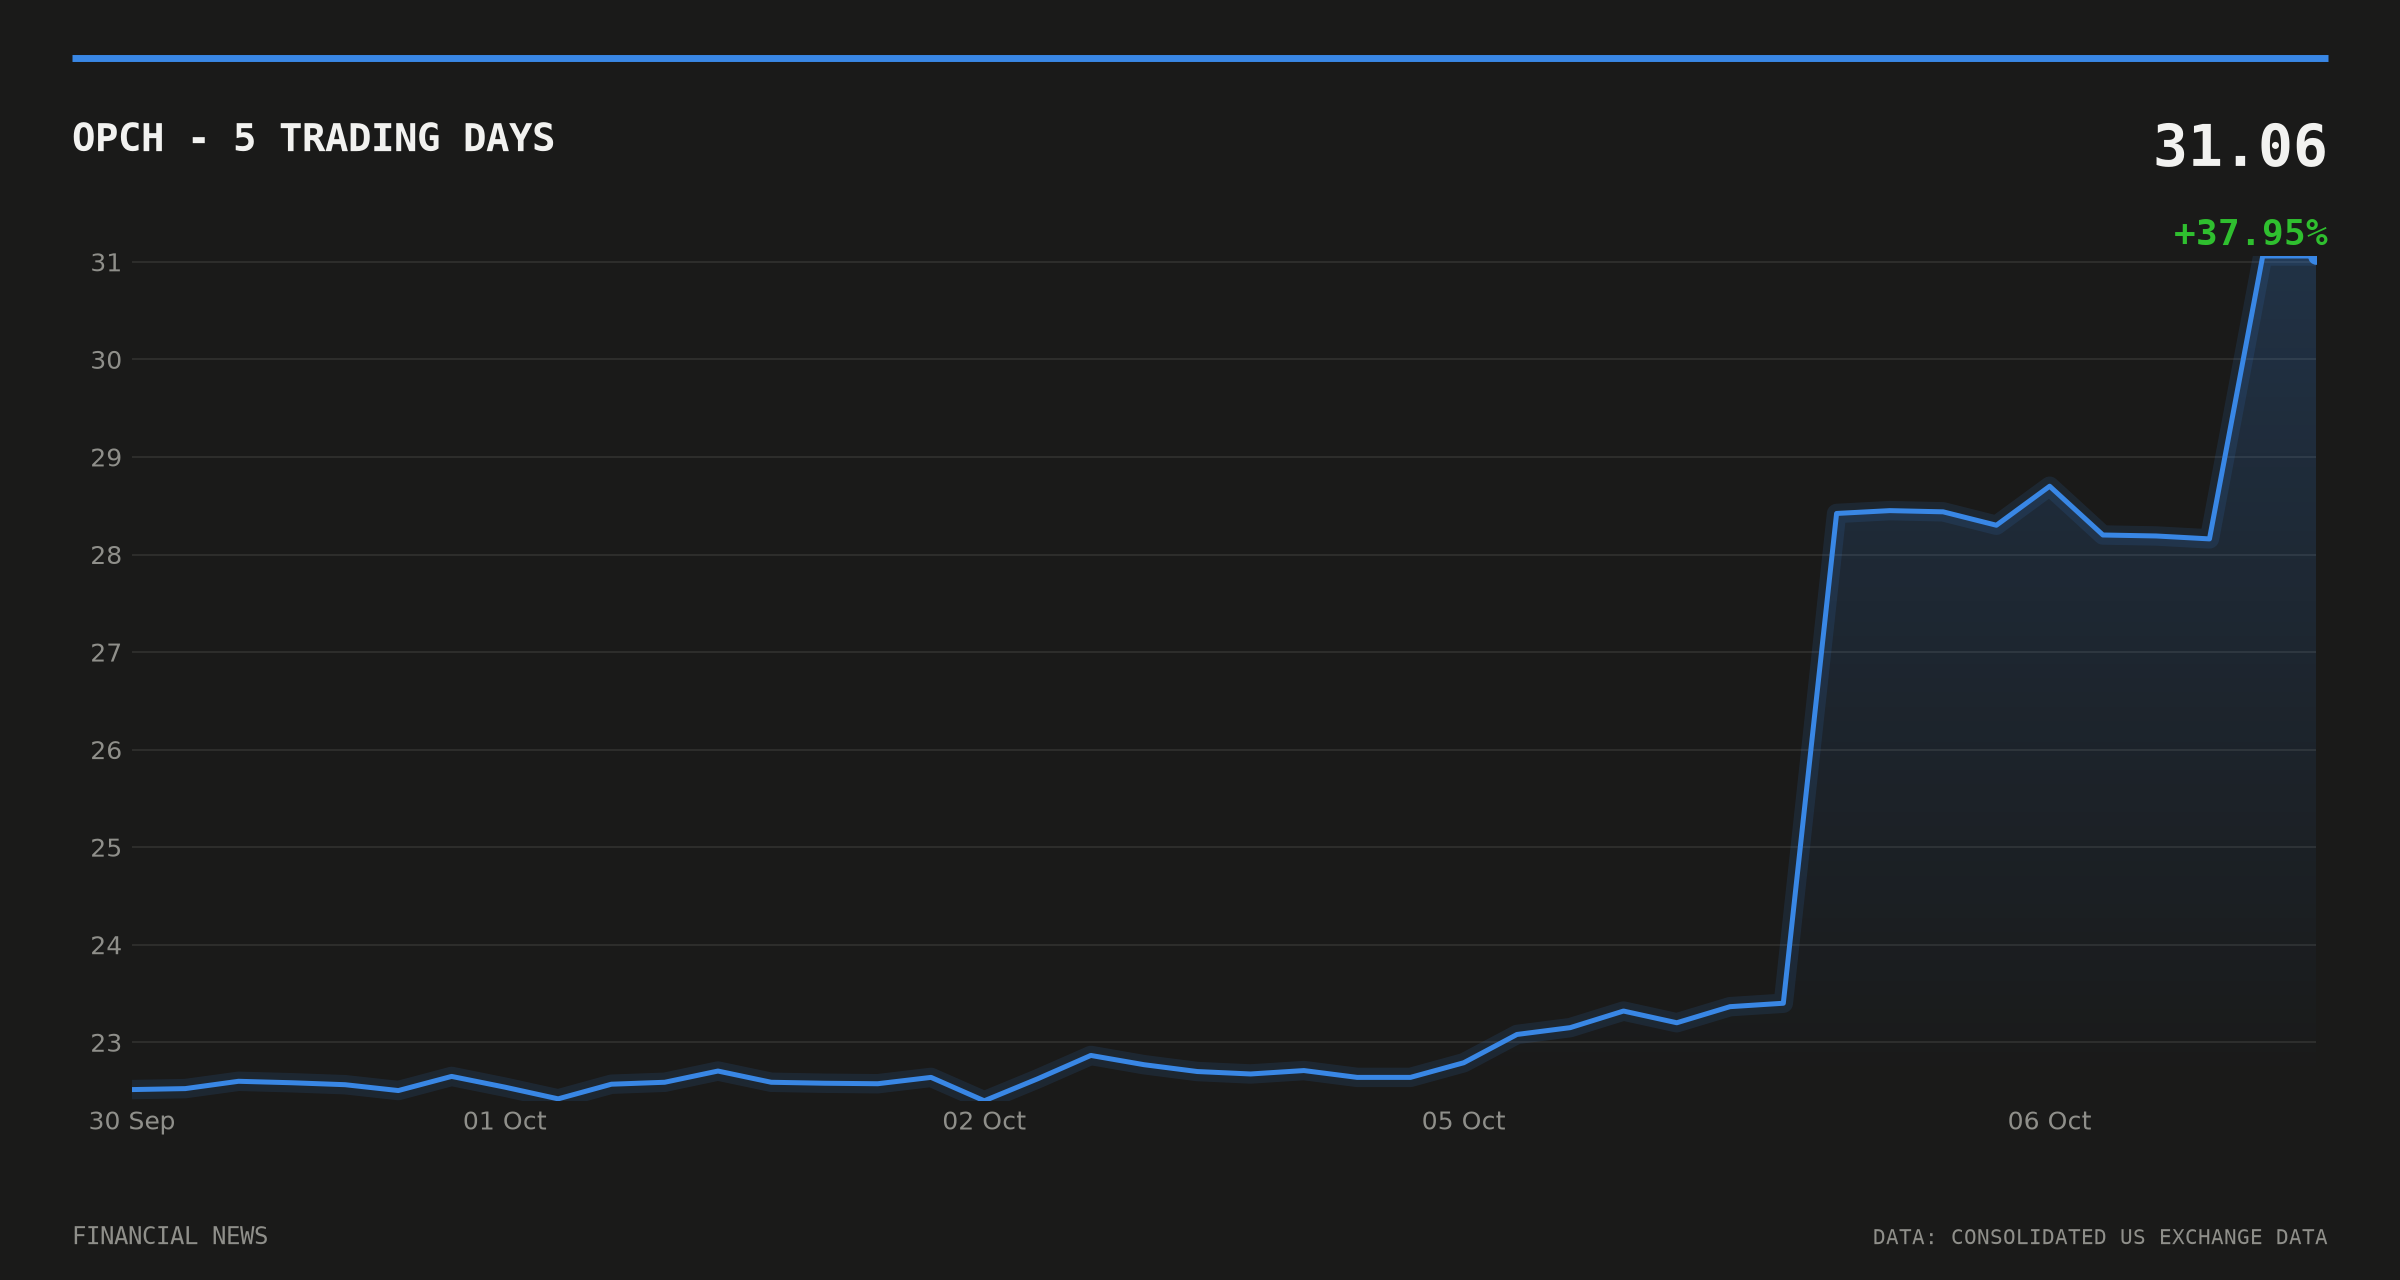

CD&R and McKesson Corporation (NYSE: MCK) have signed a definitive agreement to acquire Option Care Health (Nasdaq: OPCH), the companies said on 6 October 2026.
The buyers will pay $32.05 a share, valuing the home and alternate-site infusion provider at roughly $5.8bn in enterprise value.
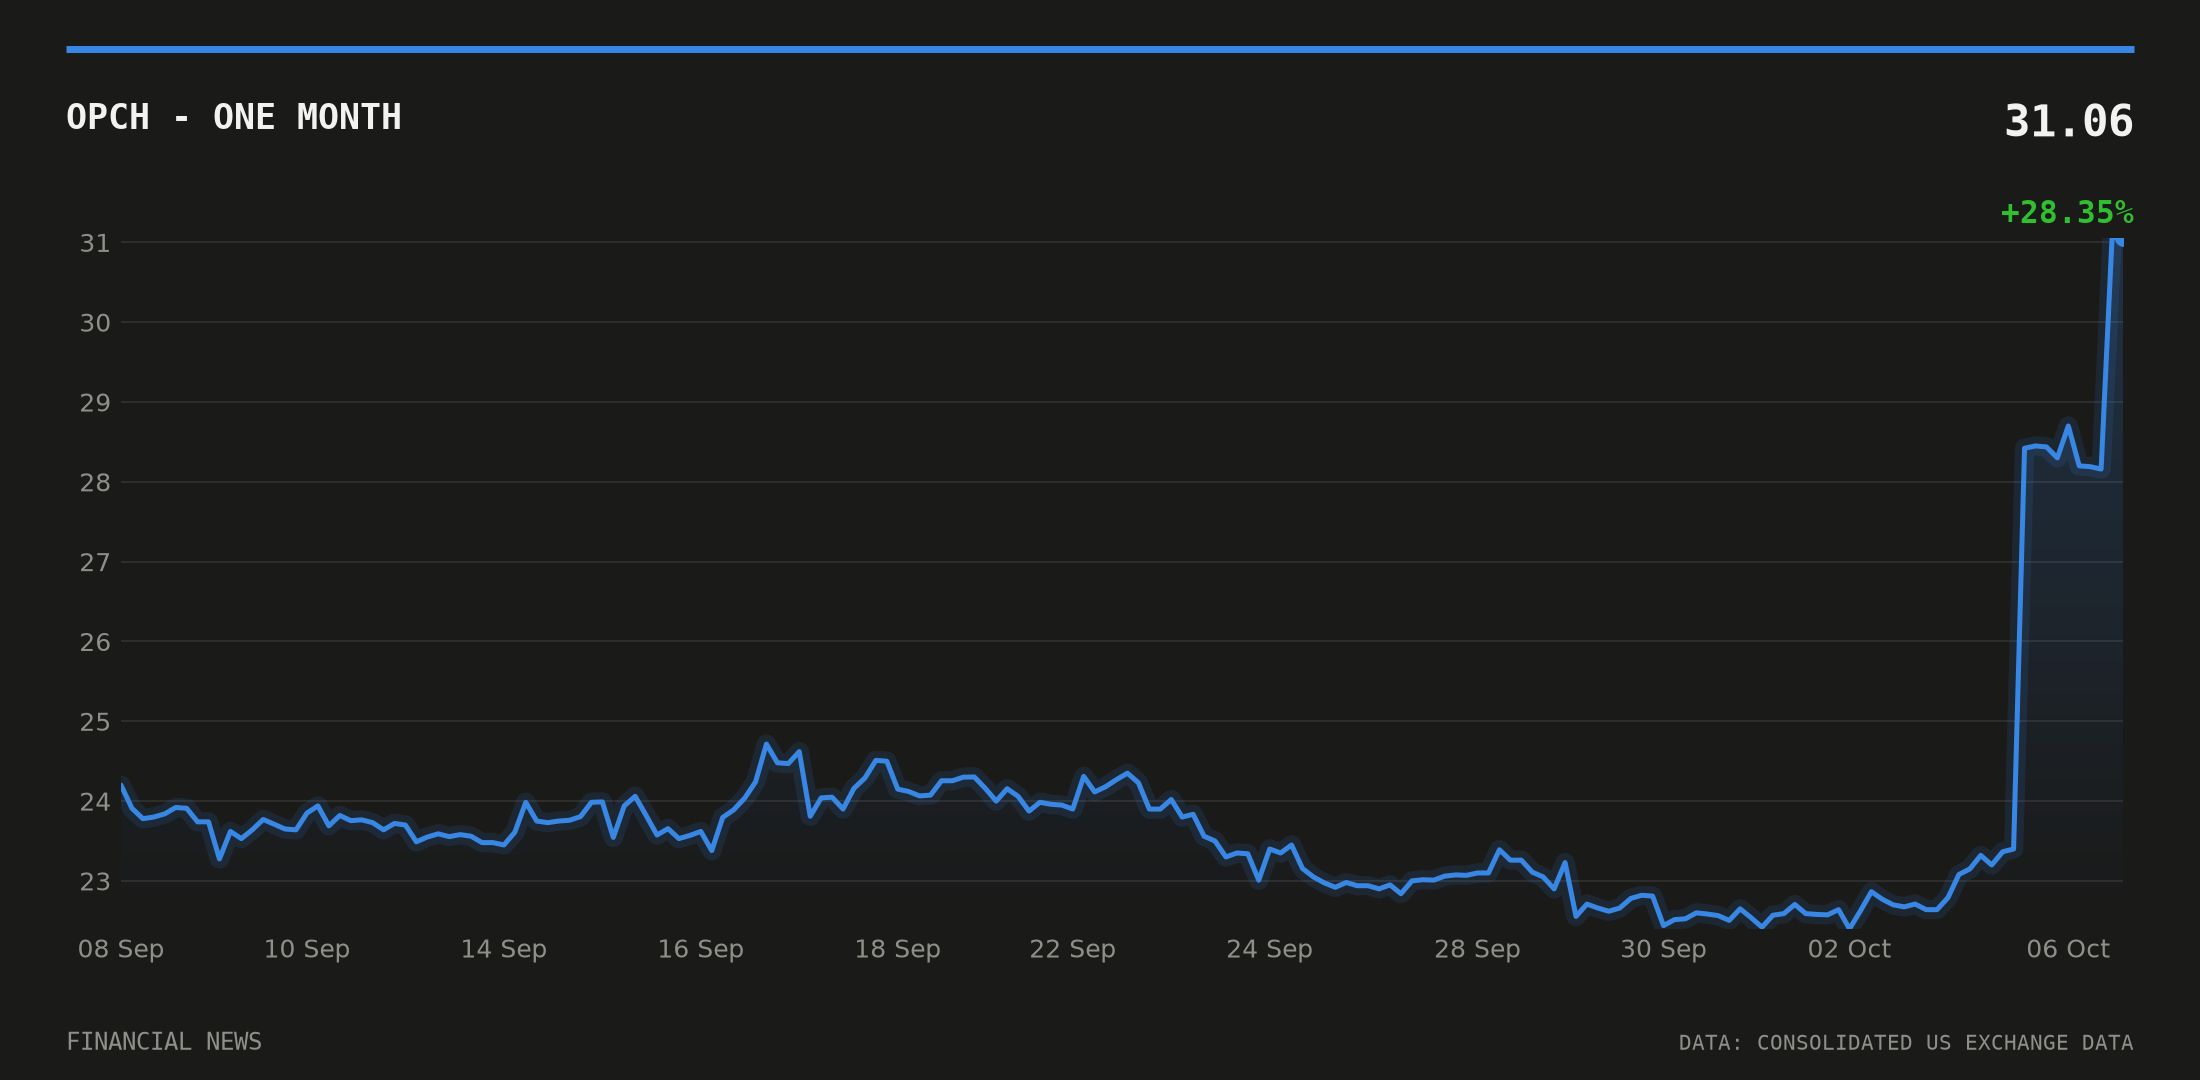
Option Care shares closed the morning session at $31.05, up 9.19% on the day and 29.7% over 20 days, with volume running at 5.83 times the stock’s 20-day average, according to consolidated exchange data. The stock had traded as low as $22.40 in the preceding 20 days, putting the deal price at a premium of roughly 37% to 43% over that range.
Deal structure: CD&R takes control, McKesson buys in
Under the agreement, confirmed in Option Care’s own 8-K filing with the SEC, CD&R will hold majority ownership of the combined private company once the deal closes, with McKesson taking a minority stake. The split echoes earlier reporting, cited by Finimize, that the two parties were discussing a 49%/51% ownership structure well before the formal announcement.
The deal takes Option Care private, ending its run as a Nasdaq-listed independent. The company describes itself as the largest independent infusion therapy provider in the US, serving more than 308,000 patients a year through over 197 locations, according to AP reporting carried by KSL.
A beaten-down stock, not a surprise approach
The premium looks generous on paper, but it arrives after a rough stretch for the shares. Option Care stock had fallen roughly 27% over the prior year before deal talk emerged, according to Private Equity Wire, which put the pre-premium enterprise value nearer $4.7bn once around $1.2bn of debt is included. That makes the buyout less a bolt from nowhere and more a floor being put under a stock that had already been clawing back some of its losses before the announcement.
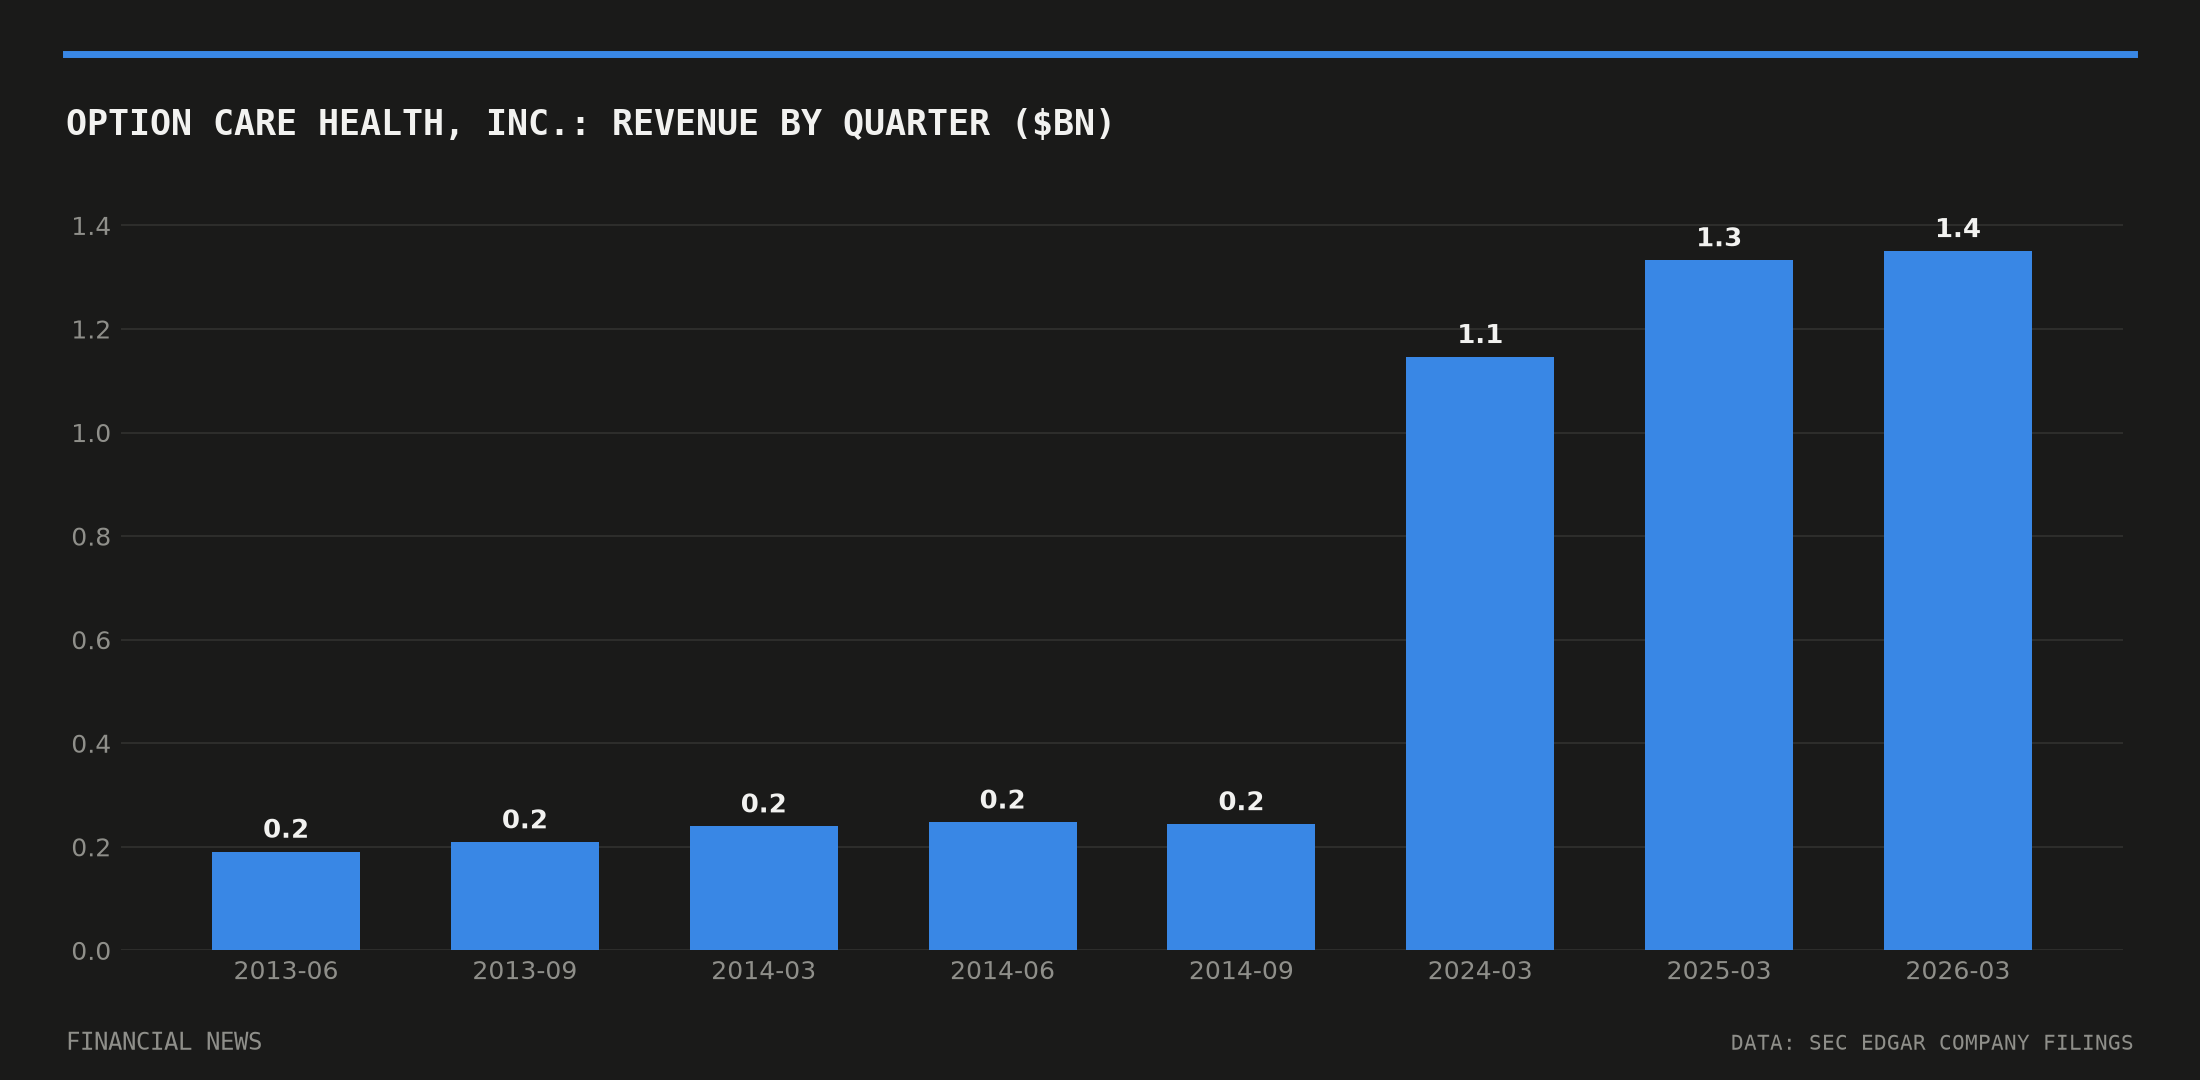
Option Care’s revenue growth over the past decade gives some sense of how the business has scaled since its earlier incarnation as a smaller infusion specialist. Quarterly revenue ran at $190.7m in the second quarter of 2013 and had climbed to $247.1m by the second quarter of 2014, according to filings with the SEC. By the first quarter of 2026, quarterly revenue stood at $1.35bn, up from $1.33bn a year earlier, filings show, underscoring how far the company has grown since those early 10-Q reports.
Financing backdrop: a high-rate environment for leverage
The take-private structure typically relies on leveraged financing, and CD&R is striking this deal against a backdrop of elevated borrowing costs. The 10-year US Treasury yield stood at 5.28% on 2 October 2026, up from 5.24% a few days earlier, while the 2-year yield stood at 4.83%, according to data from the Federal Reserve Bank of St Louis. The 10-year/2-year spread, a gauge watched for signs of yield-curve inversion risk, stood at 0.47 percentage points as of 5 October, little changed from 0.45 a few days prior.
That rate backdrop makes debt-funded buyouts costlier to finance than in the low-rate years that preceded it, a constraint private equity sponsors have had to work around across the sector this year. Separately, US consumer prices rose to an index level of 334.131 in August 2026 from 332.813 the month before, while the unemployment rate ticked up to 4.2% in September from 4.1%, Federal Reserve data show — a macro picture of gradually cooling but still-firm economic conditions against which healthcare dealmaking has continued.
Short interest in Option Care shares had been unremarkable in the fortnight before the announcement, with FINRA’s daily short-sale ratio for the stock ranging between roughly 0.45 and 0.66 through late September and early October, data from the FINRA short-sale volume series show, giving little indication the market had anticipated the scale of the premium.
Independent confirmation of the terms came from multiple outlets beyond the companies’ own statement, including MLex and Newsquawk, both of which verified the $32.05-a-share price and the roughly $5.8bn enterprise value. Completion of the transaction remains subject to customary closing conditions, including regulatory clearance, with the companies yet to confirm an expected closing date.
This article is for information only and is not investment advice or a recommendation to buy or sell any asset. Markets move quickly; figures are correct as sourced at the time of writing. Always do your own research before making financial decisions.
