

FactSet Research Systems (NYSE: FDS) reported fourth-quarter and full-year fiscal 2026 results on Wednesday, with organic annual subscription value climbing 7% to $2.56bn and topping the company’s own guidance.
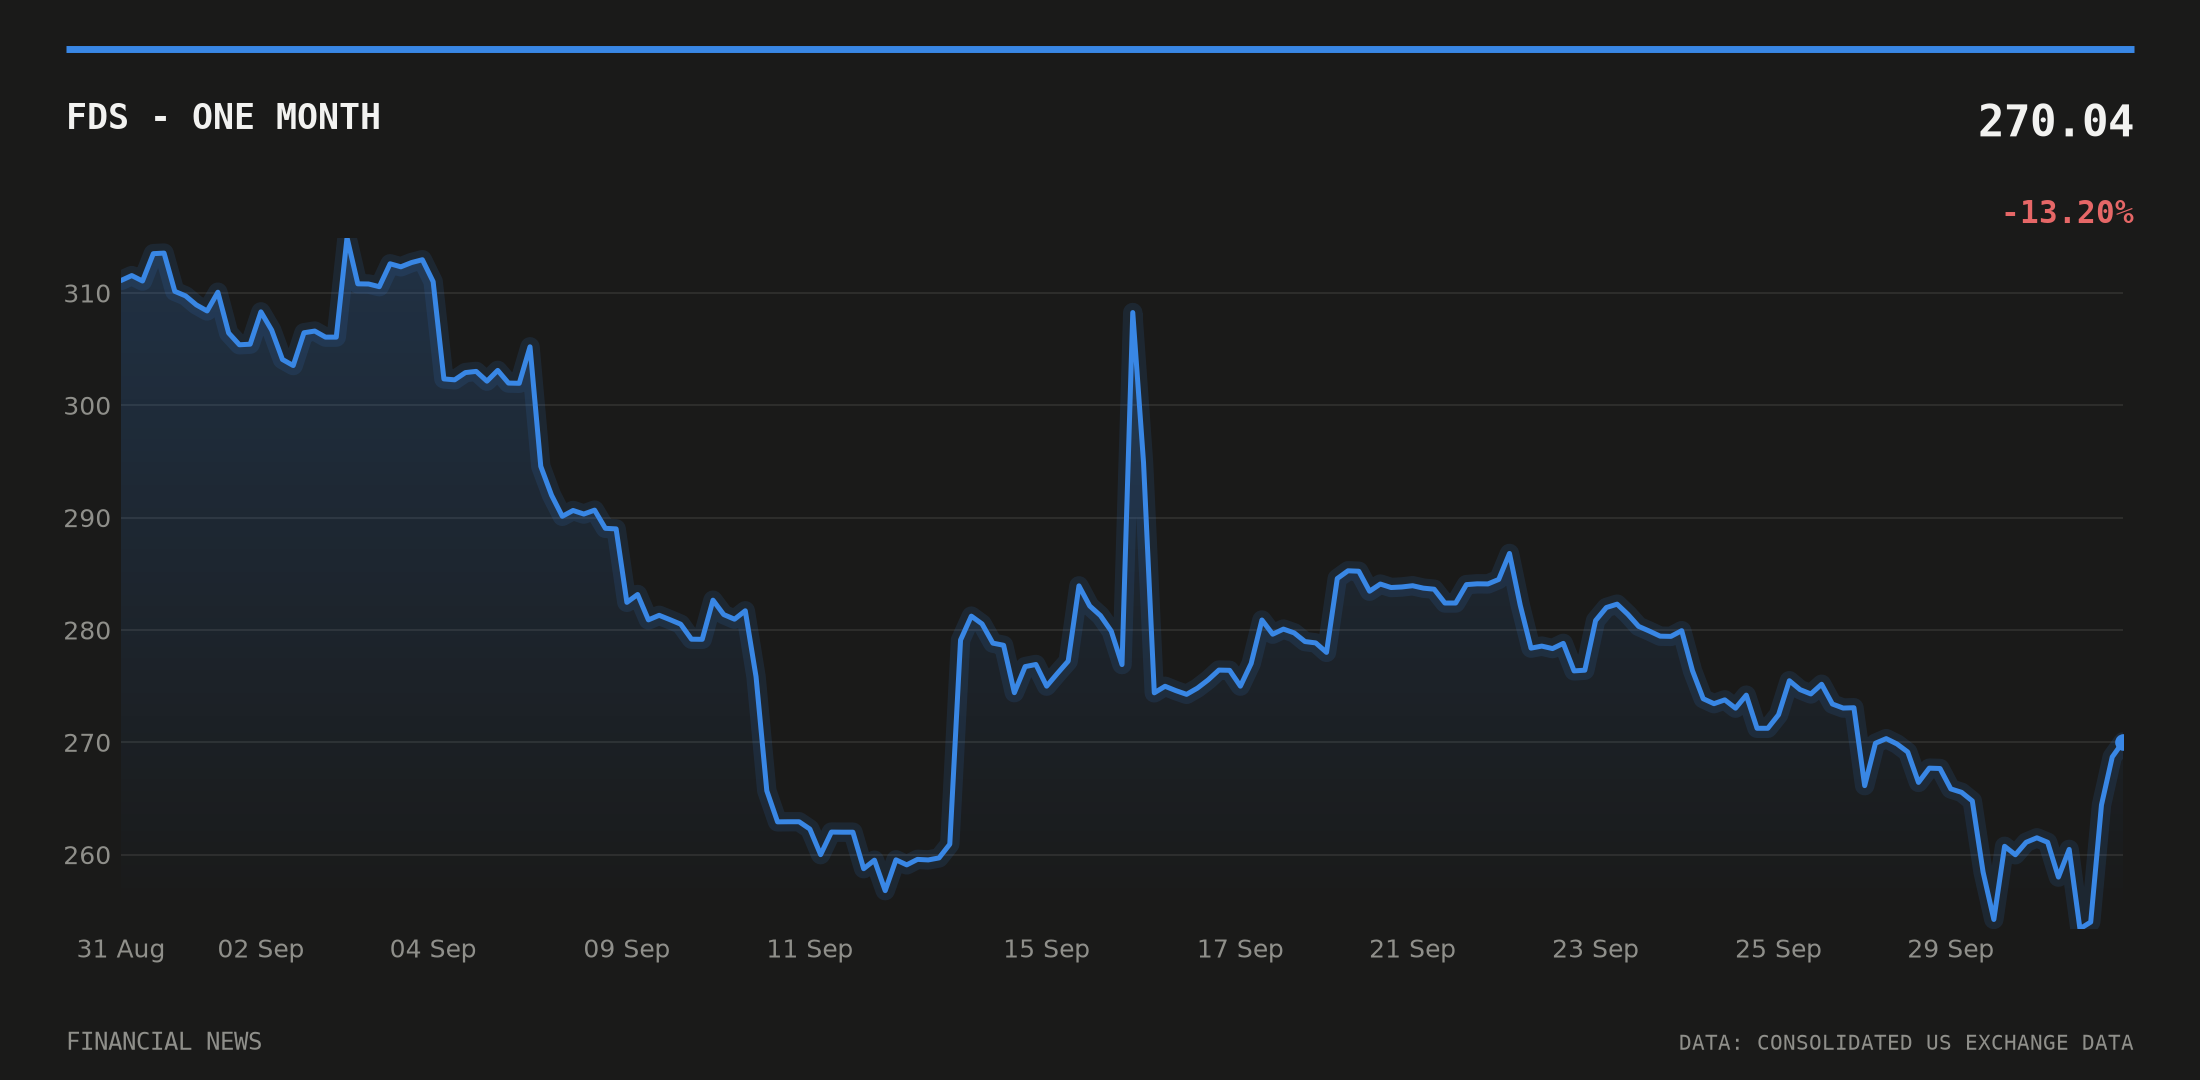
Adjusted diluted earnings per share rose 6.1% to $18.01 for the year, while adjusted operating margin came in at 34.5%, FactSet said in its earnings release filed with the SEC. Shares traded at $270.23 as of 3pm UTC, up 3.5% on the session.
FactSet Q4 earnings top guidance on ASV growth
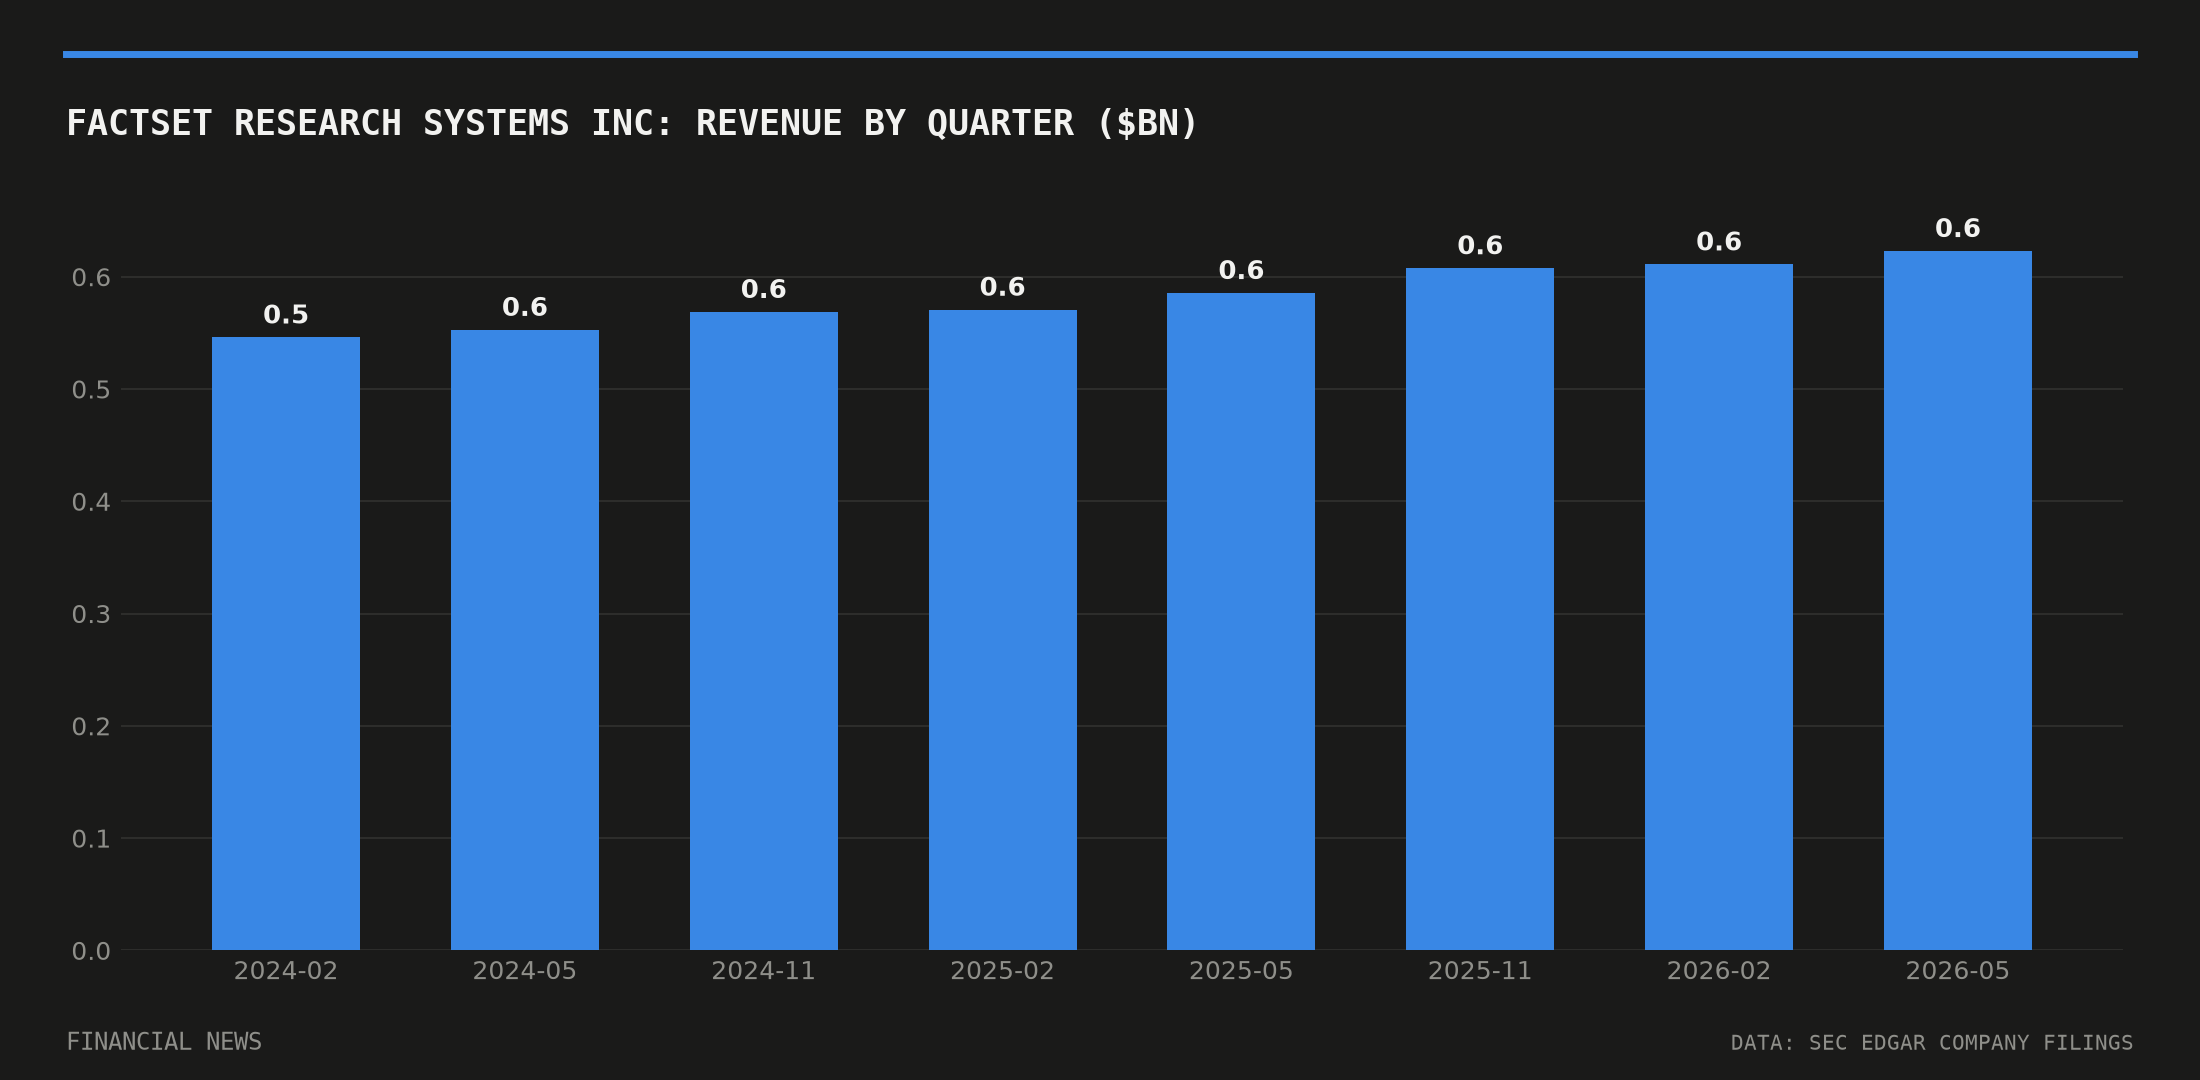
Organic ASV rose $168.2m over the year to $2,568.2m, a 7% growth rate that exceeded the range FactSet had guided to, according to the SEC filing. Fourth-quarter revenue grew 6.3% to $634.7m, with organic revenue up 7.1%.
The company pointed to new AI products as a driver of the beat, including AI tools for banking clients and Model Context Protocol servers that let clients query FactSet data through large language models. More than 650 clients are now actively consuming MCP data through paid subscriptions or trials, Investing.com reported from the earnings call.
Shares rose roughly 2.25%-2.4% in pre-market trading before extending those gains through the session, Investing.com reported, reflecting investor approval of the beat despite softer guidance for the year ahead.
Adjusted figures diverge from GAAP results
The headline numbers all come from FactSet’s adjusted, non-GAAP presentation. On a GAAP basis, diluted earnings per share fell to $14.57 from $15.55 a year earlier, and GAAP operating margin dropped to 28.3% from 32.2%, according to the GlobeNewswire release.
Fourth-quarter net income fell 21.1% to $121.1m even as adjusted EPS rose over the same period, StockTitan’s summary of the 8-K filing showed. FactSet attributed the gap to one-time restructuring charges and costs tied to executive compensation.
The pattern shows up across FactSet’s recent quarterly filings, too. Net income has drifted lower each quarter this fiscal year, from $152.58m in the first quarter to $126.72m in the third, according to 10-Q filings with the SEC. Diluted GAAP EPS followed the same path, falling from $4.06 to $3.50 over the same three quarters.
FY2027 guidance points to slower growth
For fiscal 2027, FactSet guided to organic ASV growth of 5% to 6.5%, a step down from the 7% pace just delivered, with adjusted operating margin expected to improve by 25 to 75 basis points from the 34.5% base. That would put the margin range at roughly 34.75% to 35.25%, per the filing summary.
FactSet returned $808m to shareholders through dividends and buybacks in fiscal 2026, a 75% increase from the prior year, and marked its 27th consecutive year of dividend increases, according to the earnings release. The company also extended its run to 47 consecutive years of revenue growth and 30 consecutive years of adjusted EPS growth since its 1996 initial public offering, Investing.com noted.
Analyst sentiment on the stock stayed split after the print, with a consensus of 3 buy, 13 hold and 9 sell ratings, according to Alphastreet. The narrower ASV growth guided for fiscal 2027, against a widening gap between adjusted and reported profit, gives investors two different pictures of the same year to reconcile before the company’s next quarterly update.
FactSet executives discussed the results and outlook on a conference call Wednesday, a transcript of which was carried by Benzinga. The 10-year US Treasury yield stood at 5.24% on 28 September, up from 5.17% the prior reading, according to Federal Reserve data, a backdrop against which data-and-analytics vendors like FactSet compete for institutional client budgets.
This article is for information only and is not investment advice or a recommendation to buy or sell any asset. Markets move quickly; figures are correct as sourced at the time of writing. Always do your own research before making financial decisions.
