

Cabot Corporation (NYSE: CBT) confirmed an interim CFO appointment for Steve Delahunt on 15 September 2026, effective from 1 October. Delahunt, currently vice president and corporate treasurer, steps into the finance chief’s role while the Boston-based chemicals maker searches for a permanent successor, according to a company statement.
The date matters: 1 October is also when current CFO Erica McLaughlin moves up to become Cabot’s president and chief executive, succeeding Sean Keohane, according to a Cabot exhibit filed with the Securities and Exchange Commission. The interim CFO appointment is the direct consequence of that reshuffle at the top.
Interim CFO appointment follows CEO succession plan
Keohane told Cabot’s board in July that he would retire as president and chief executive and leave the board on 30 September 2026, according to a separate 8-K filed in July. McLaughlin, who has served as executive vice president, CFO and head of corporate strategy, was elected to replace him, according to the same filing that confirms Delahunt’s stopgap role.
Cabot’s press release, quoted verbatim, said Cabot had ‘appointed Steve Delahunt, Vice President and Corporate Treasurer, to serve as Chief Financial Officer on an interim basis, effective October 1, 2026’, while a search for a permanent replacement continues.
A Form 4 for McLaughlin was filed with the SEC on 14 September, a day ahead of the CFO announcement, part of the paperwork trail accompanying her move into the chief executive’s chair. Keohane’s departure caps close to a decade as chief executive and nearly 25 years at the company overall, with McLaughlin’s promotion an internal succession rather than an outside hire, according to European Coatings. Delahunt himself is a long-serving internal figure, having led Cabot’s investor relations function for nine years before moving to the treasurer’s role, according to the company’s own past investor updates.
Earnings slide sets the backdrop
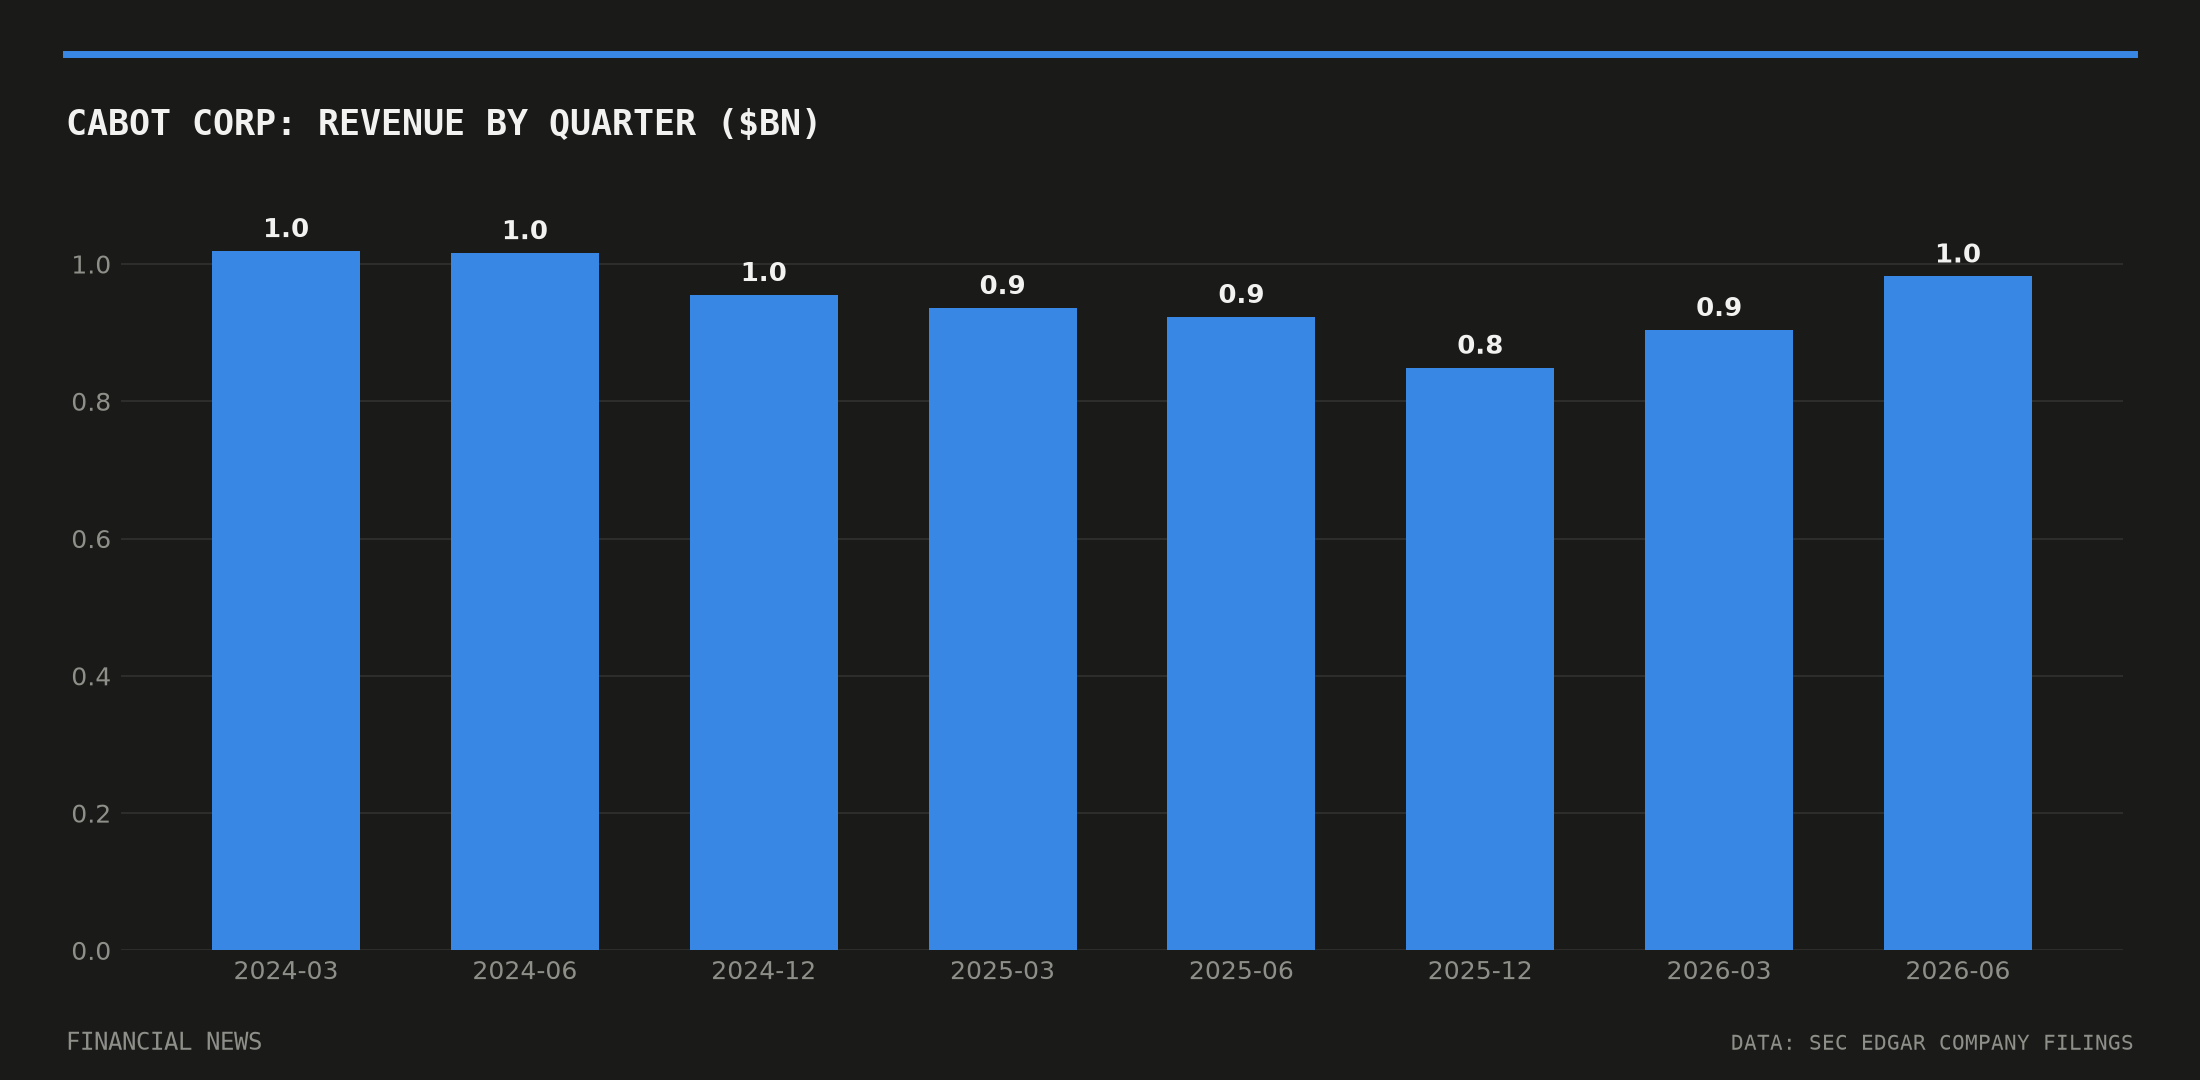
The leadership change lands as Cabot’s results have deteriorated sharply. Net income for the fiscal third quarter, ended 30 June 2026, fell to $6m from $101m a year earlier, according to the company’s 10-Q filing. Diluted earnings per share dropped to $0.12 from $1.86 over the same period.
Revenue held up better, at $982m for the quarter versus $923m a year earlier, but the profit collapse was driven by higher restructuring costs, weaker earnings in the Reinforcement Materials segment and a pension plan settlement charge, according to Cabot investor materials reviewed by Quartr. The quarter marked the sharpest earnings drop in the run of results Cabot has reported since early 2024, when quarterly net income ran between $84m and $109m.
Market reaction muted
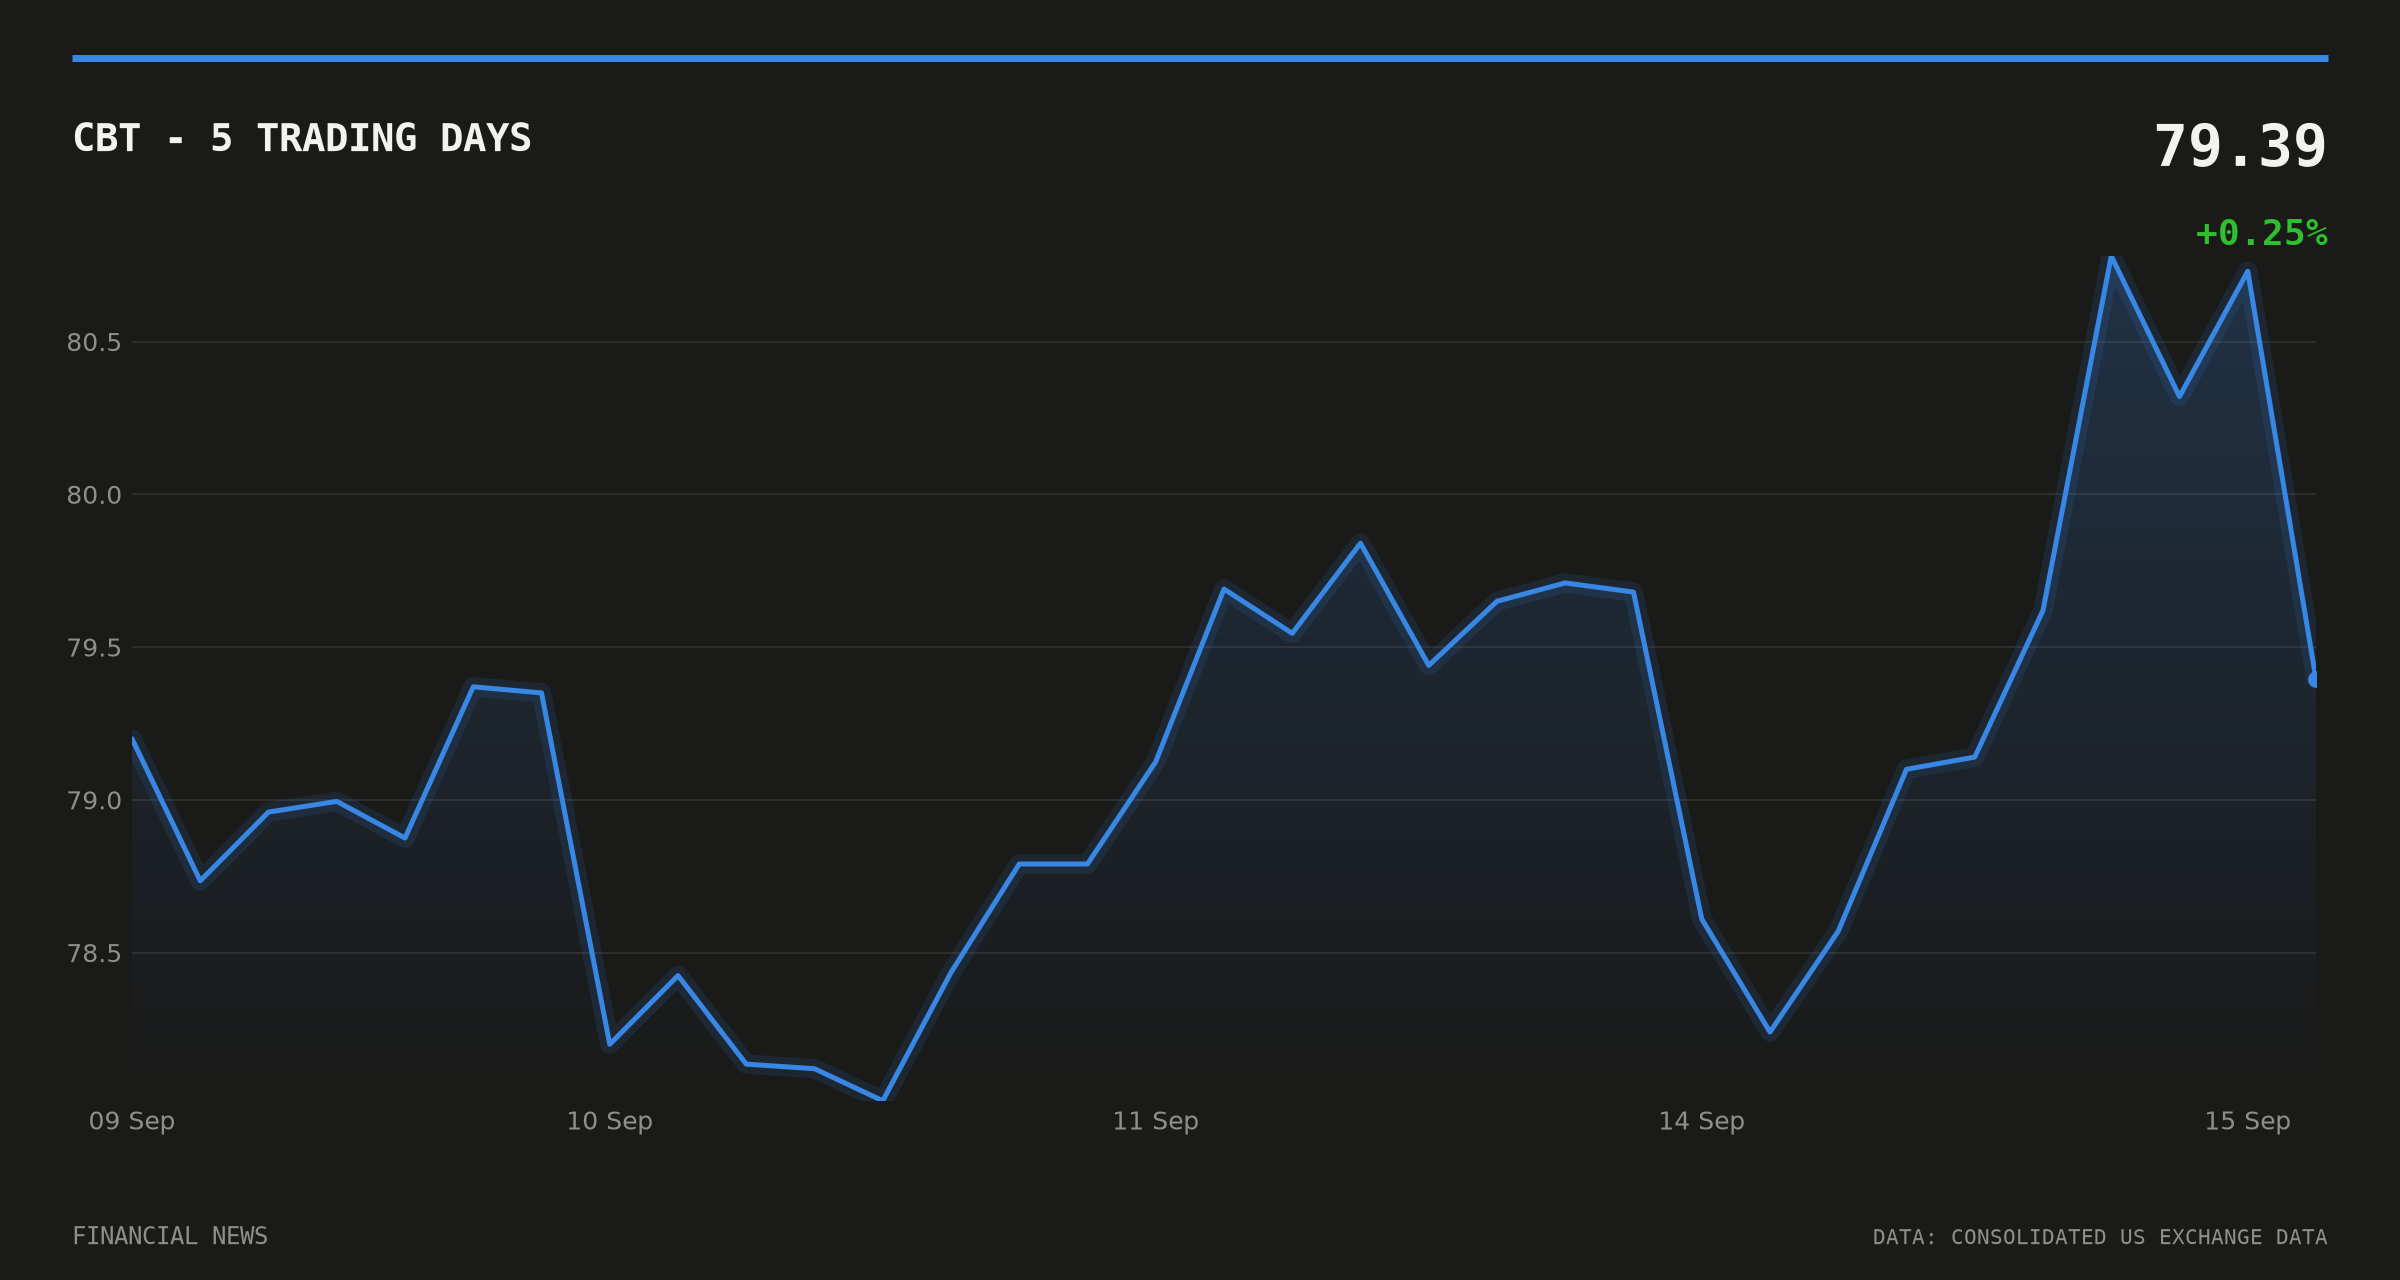
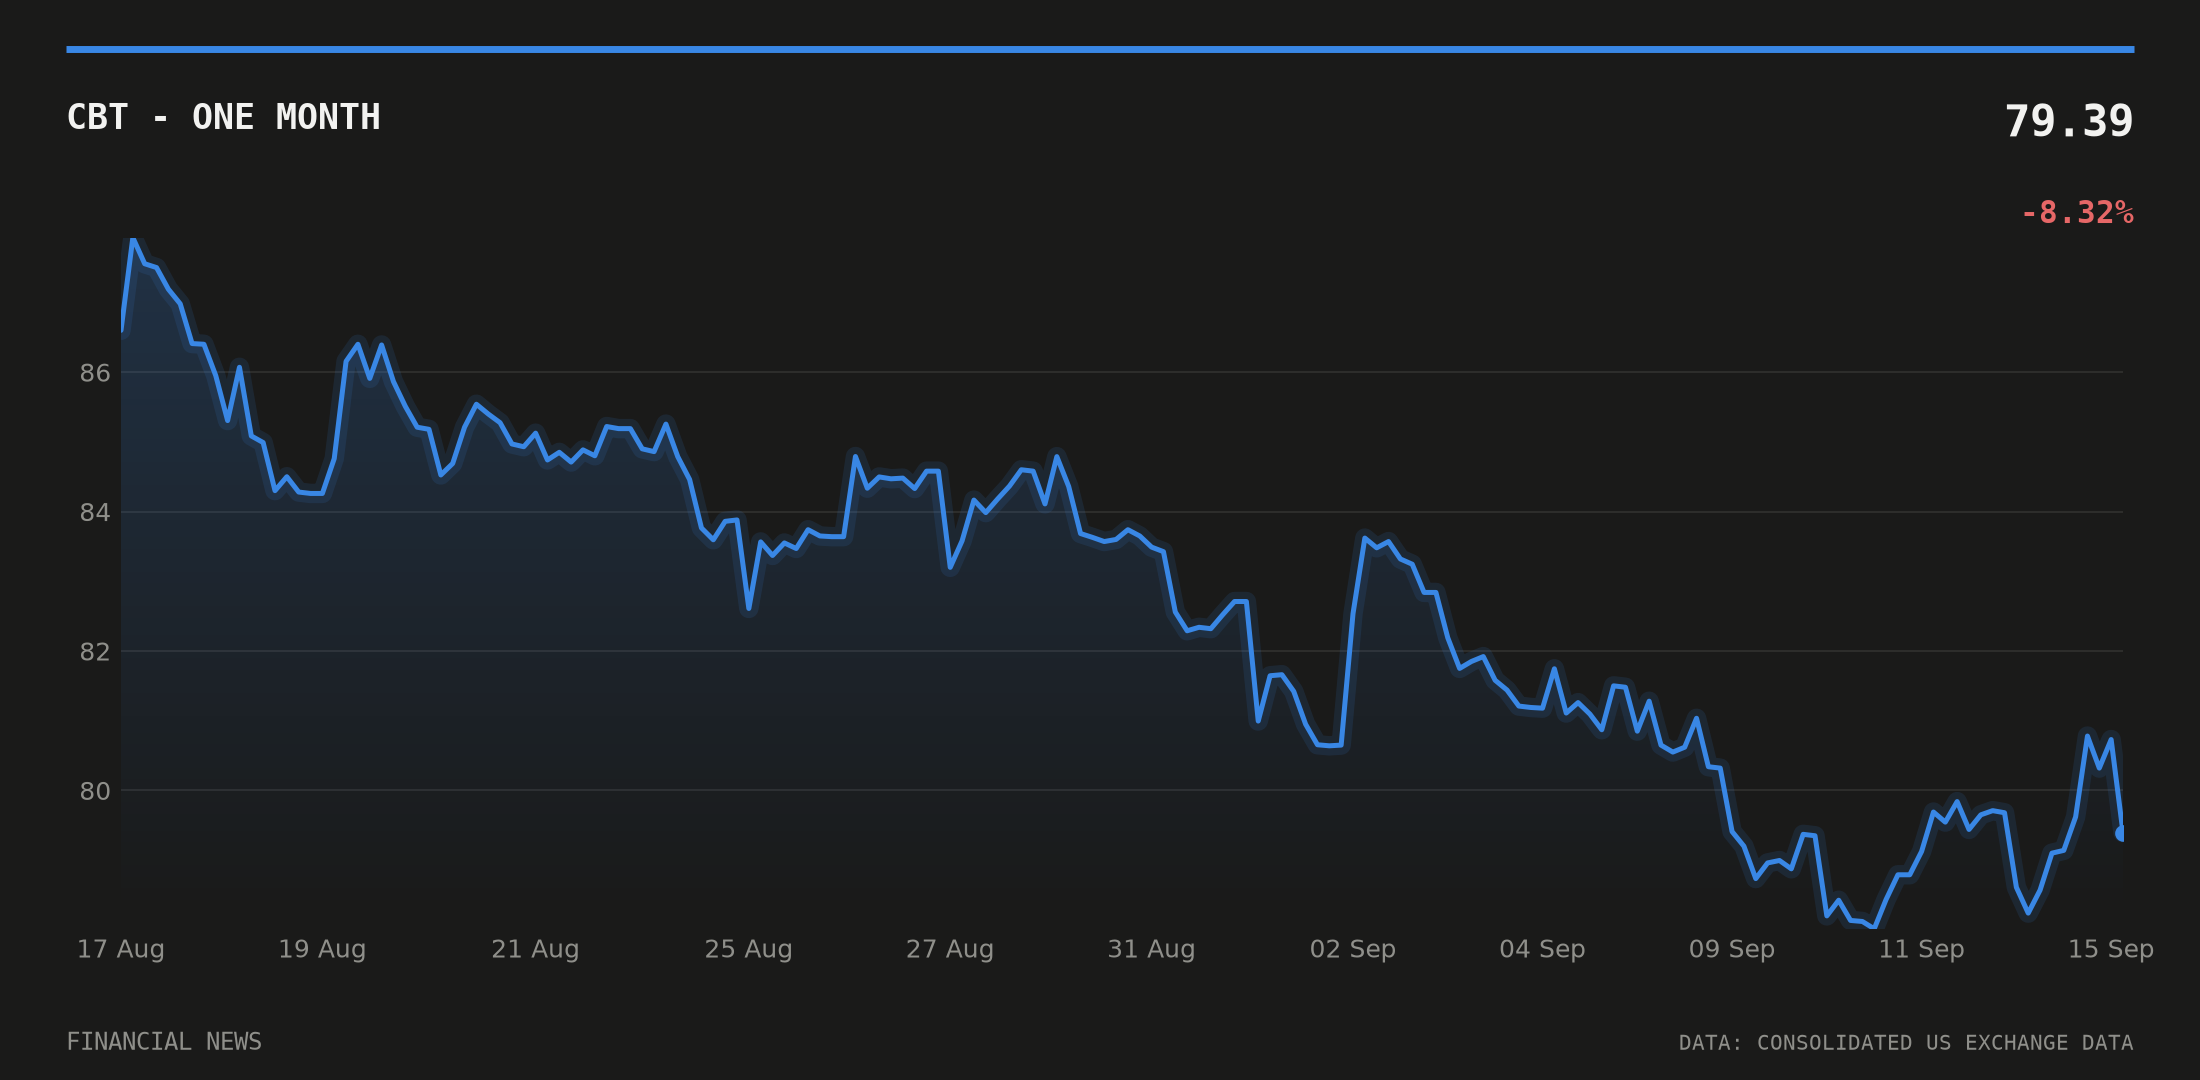
CBT shares last traded at $80.73 as of 15 September, up 3.18% over the prior 24 hours but still down 3.39% over the trailing 20 days, according to consolidated exchange data. The stock has traded in a range of $78.02 to $84.79 over that stretch, with volume running 1.4 times the 20-day average around the announcement.
FINRA daily short-sale data show no sign of unusual positioning ahead of the news: the short volume ratio for CBT ran between roughly 0.70 and 0.82 through the first two weeks of September, broadly in line with levels seen for weeks before the appointment was disclosed.
Cabot has not set a timetable for naming a permanent CFO. McLaughlin takes over as chief executive on 1 October, the same day Delahunt formally assumes the interim finance role, leaving the company running its leadership transition and its search for a permanent CFO in parallel.
This article is for information only and is not investment advice or a recommendation to buy or sell any asset. Markets move quickly; figures are correct as sourced at the time of writing. Always do your own research before making financial decisions.
