
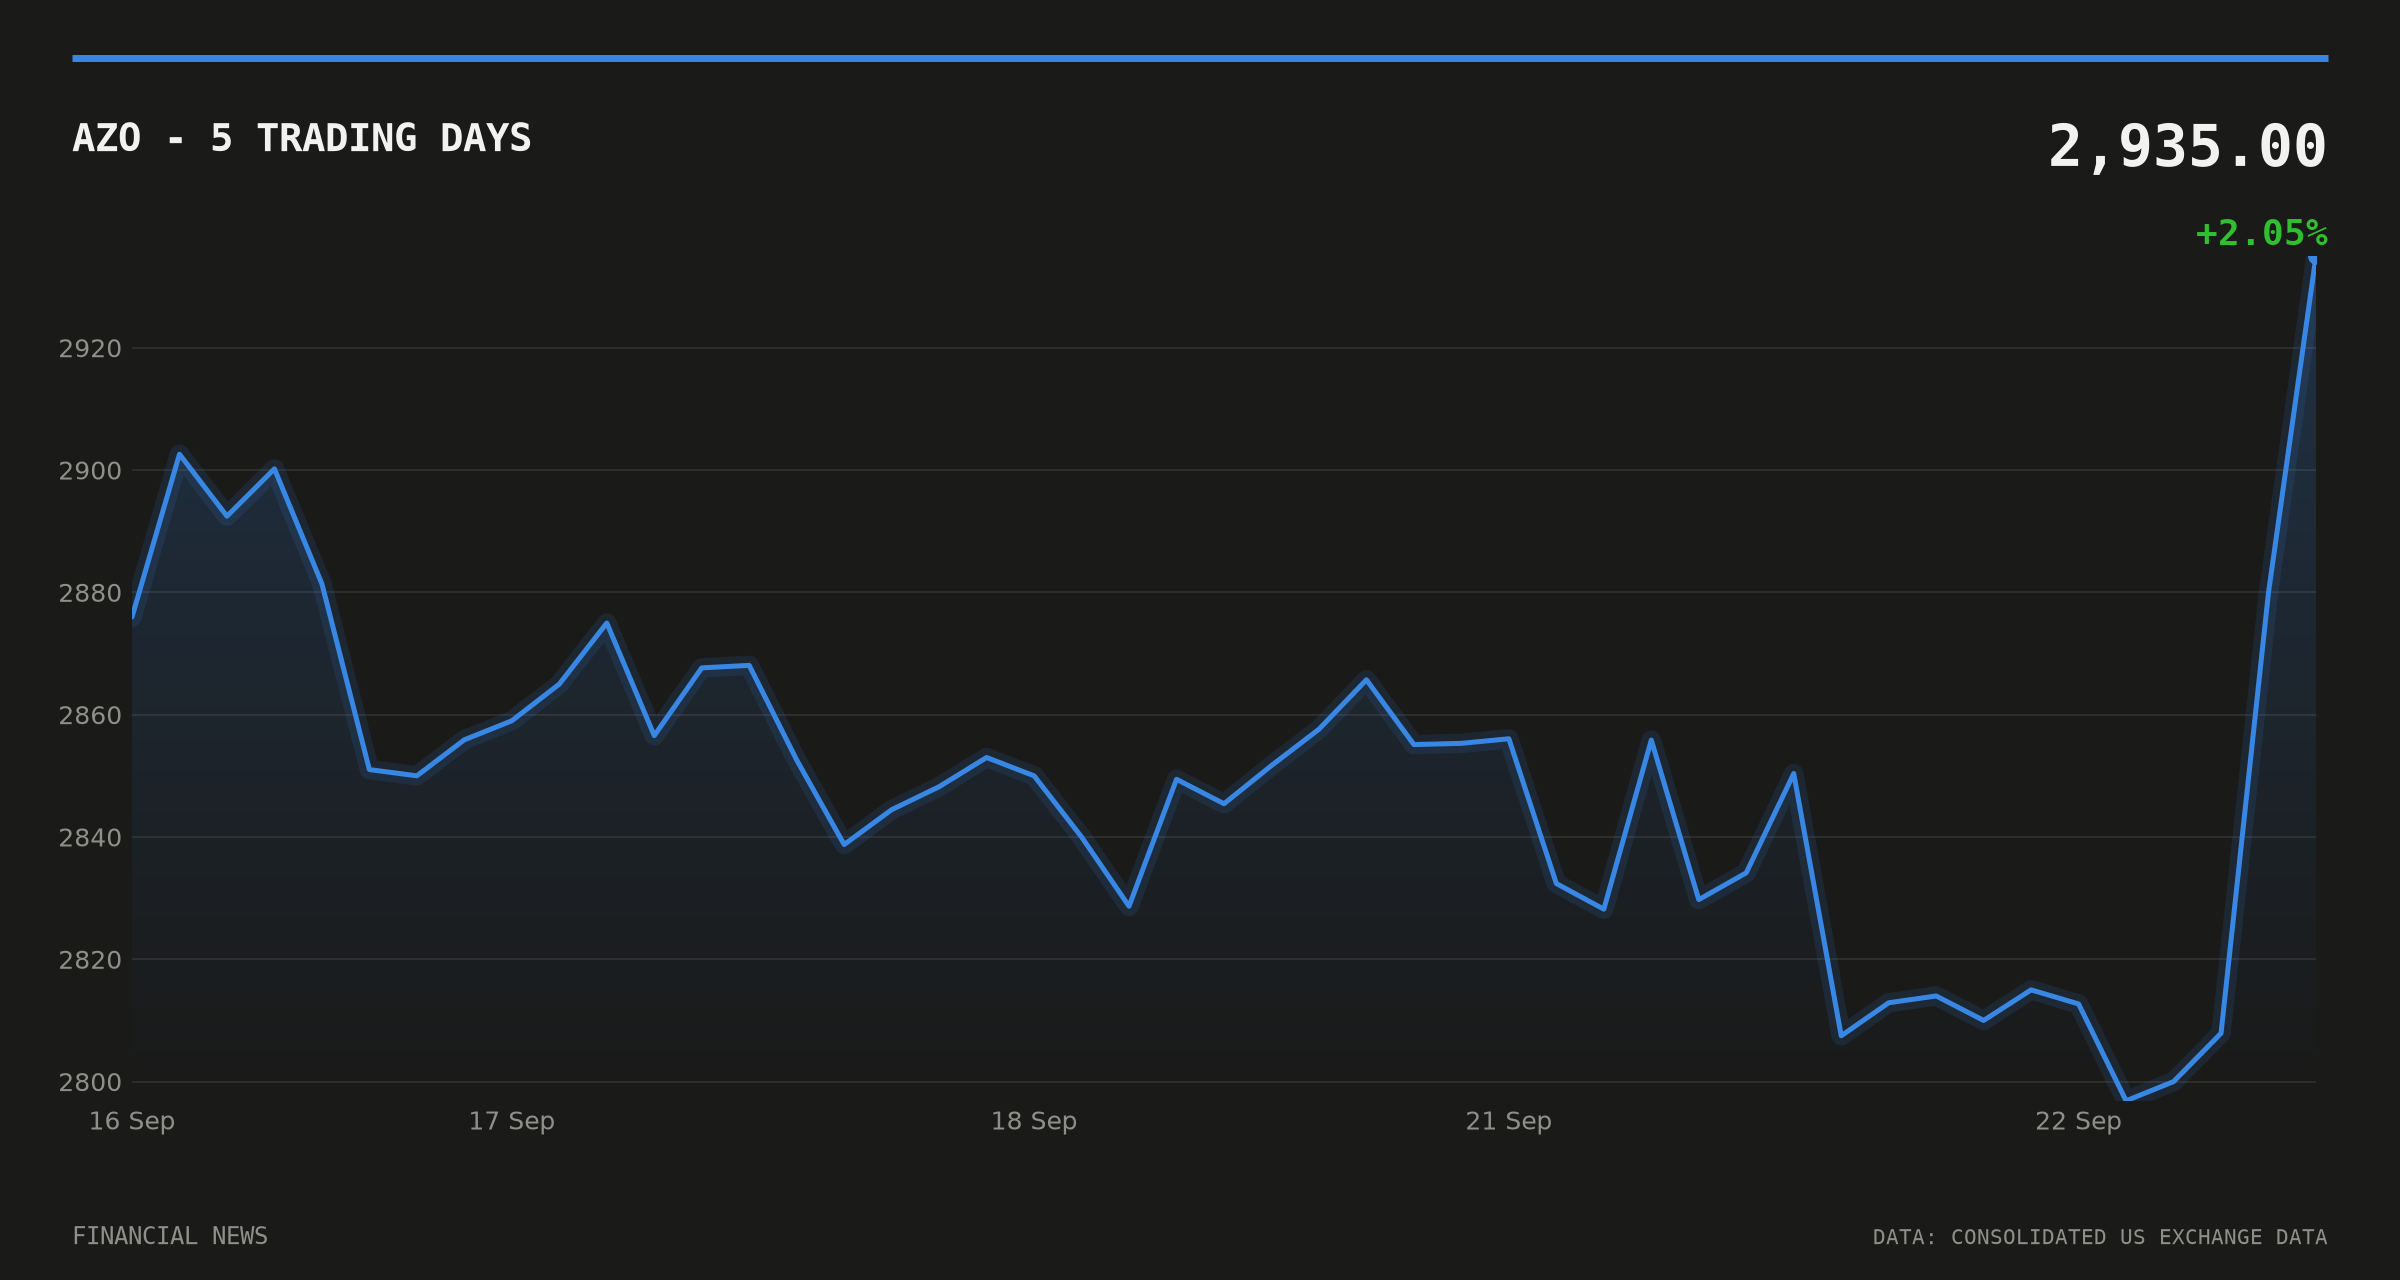

AutoZone (NYSE: AZO) reported fourth-quarter diluted earnings per share of $56.05 on 22 September 2026, up from $48.71 a year earlier.
Net sales for the 16-week quarter reached $6.6bn, a 5.6% rise year-on-year, the retailer said in its results.
AutoZone Q4 earnings beat masks a currency wrinkle
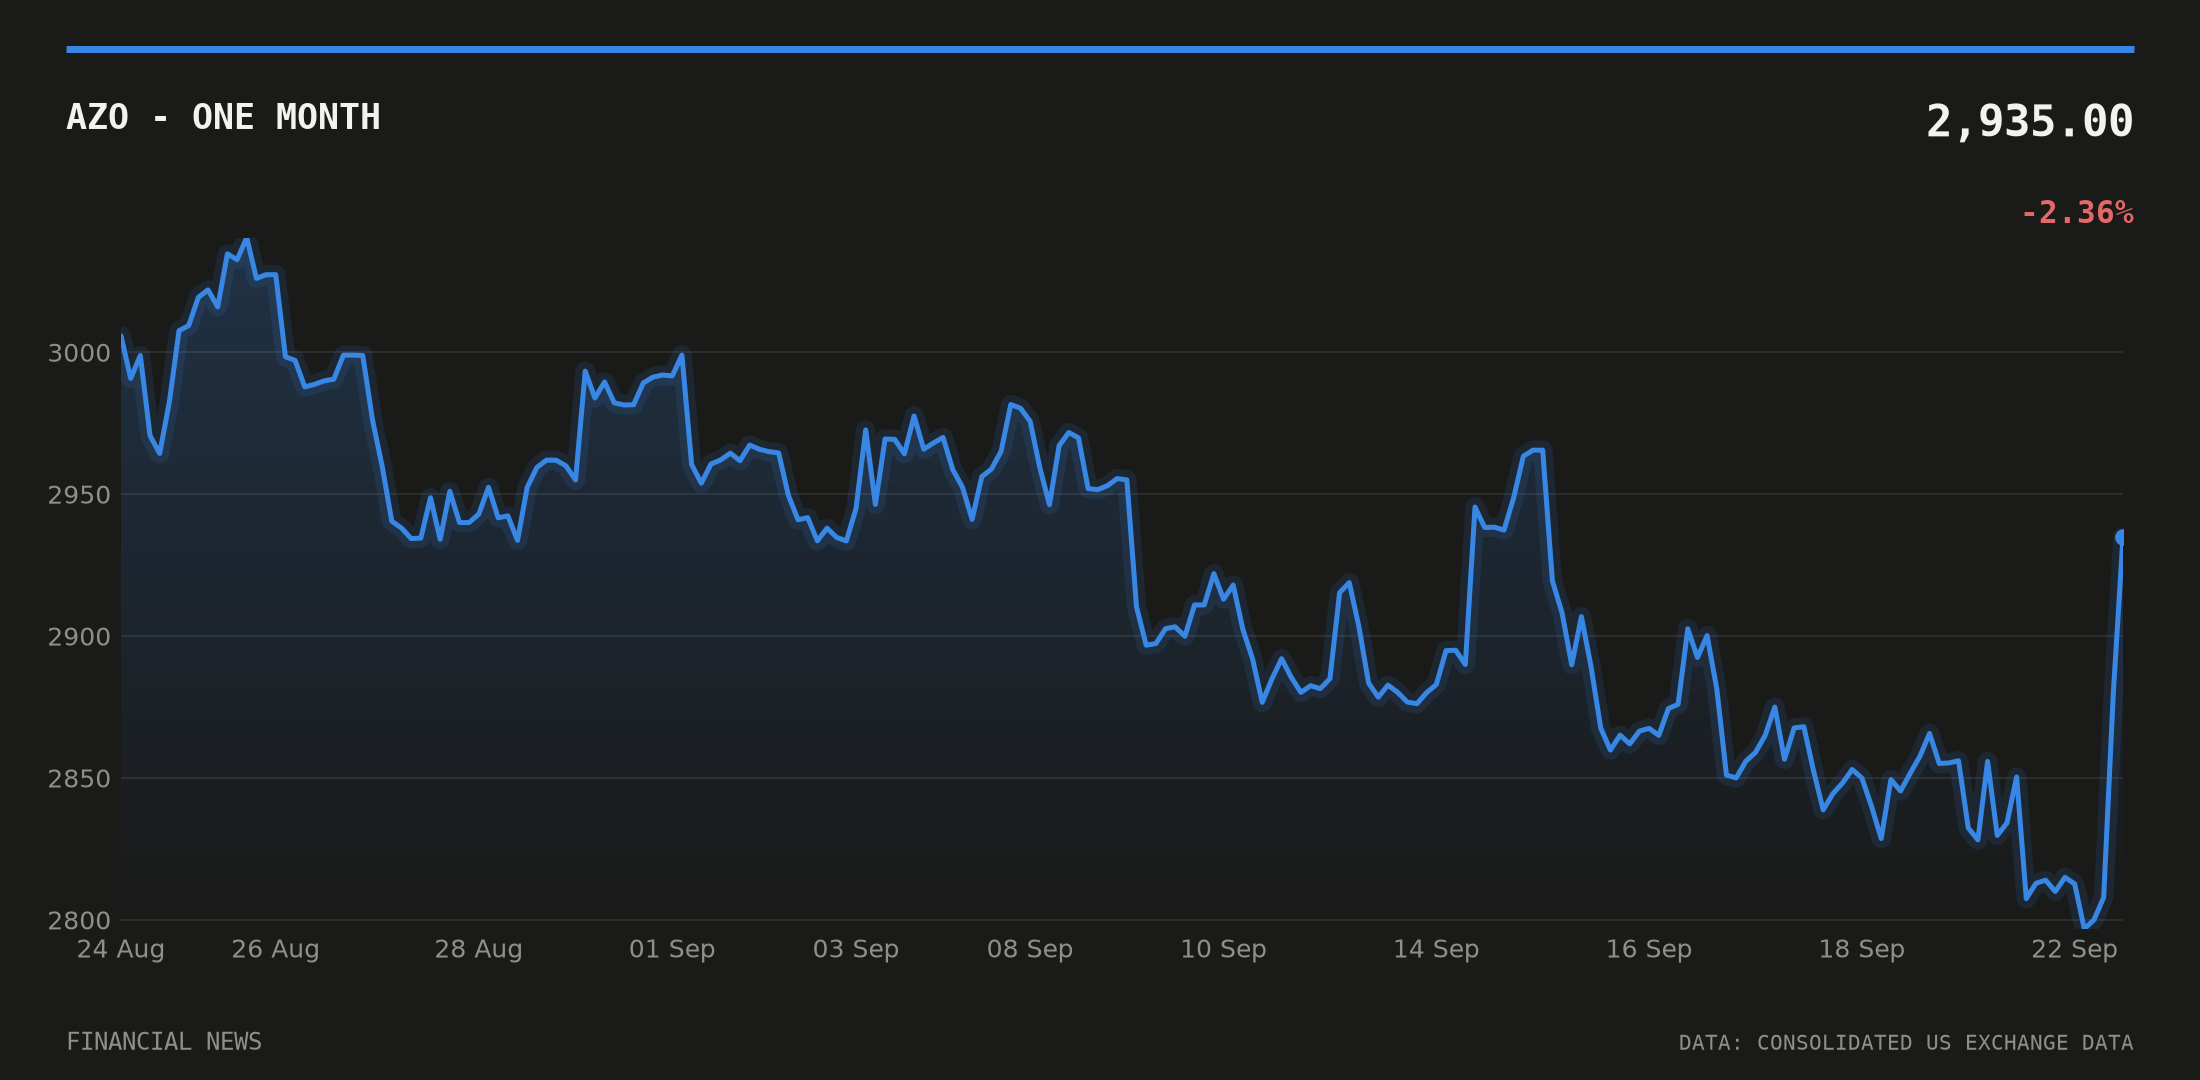
Domestic same-store sales rose 1.6% in the quarter ended 29 August 2026, AutoZone’s filing with the US Securities and Exchange Commission shows.
The headline “total company” same-store sales figure of 1.5% is the constant-currency measure. The as-reported, nominal total-company comparable-sales growth was 2.7%, according to the same SEC exhibit and figures reported by Benzinga. International same-store sales climbed 10.7% as reported, or 1.3% on a constant-currency basis.
Q4 net income totalled $931.6m, up from $837.0m a year earlier, GuruFocus reported. Full fiscal 2026 net sales came to $20.3bn, up 7.4% on the prior year.
Tariff refunds and LIFO lift gross margin
Gross margin reached 53.3% in the quarter, up 182 basis points, with 145 basis points of that gain coming from a tariff-refund benefit and a further 105 basis points from a non-cash LIFO benefit, the company’s SEC filing shows. Those one-off items help explain why quarterly earnings growth outpaced the full-year trend: full-year diluted EPS rose to $152.55 from $144.87, a 5.3% gain versus the fourth quarter’s 15.1% jump, according to StockTitan.
The scale of the swing stands out against last year’s fourth quarter, when AutoZone’s EPS fell 5.6% to $48.71 from $51.58 in fiscal 2024, hit by a LIFO-related margin squeeze. This year’s rebound, then, follows a soft comparable period rather than building on an already-strong one.
Quarterly filings lodged with the SEC through the year show the pattern building steadily: revenue of $4.63bn in the first quarter, $4.27bn in the second and $4.84bn in the third, before the fourth-quarter net sales of $6.6bn (a figure that includes the year’s peak summer trading period) pushed the full-year total past $20.3bn. Net income across those earlier quarters ran from $468.9m in the second quarter to $641.5m in the third, underscoring how much of the year’s profit growth concentrated in the final period alongside the tariff and LIFO tailwinds.
Store expansion continues alongside the earnings beat

AutoZone opened 175 net new stores in the quarter — 97 in the US, 68 in Mexico and 10 in Brazil — ending the year with 8,031 stores in total, according to Alphastreet. The pace keeps the retailer’s long-running international expansion intact even as domestic same-store sales growth remains in low single digits.
Shares traded at $2,931.63 as of the latest snapshot, up 4.33% over 24 hours following the release, reflecting the market’s reception of the print even with the constant-currency nuance buried in the detail.
Positioning and rates going into the print
FINRA’s short-sale volume ratio for AZO climbed as high as 0.674 on 10 September before easing to 0.535 the day before earnings, FINRA data show, pointing to elevated short-side positioning heading into the results.
The report also lands against a firmer rate backdrop: the 10-year US Treasury yield stood at 5.01% on 18 September, up from 4.94% the prior reading, according to FRED data from the Federal Reserve Bank of St Louis. Higher borrowing costs bear on how investors weigh AutoZone’s debt-financed share buyback programme against the durability of its Q4 margin gains, much of which stemmed from one-off tariff-refund and LIFO benefits rather than underlying pricing power.
Investors will get their next clear read on whether the tariff-refund and LIFO benefits recur when AutoZone reports first-quarter fiscal 2027 results, with the constant-currency versus as-reported same-store sales gap likely to remain a detail worth checking line by line.
This article is for information only and is not investment advice or a recommendation to buy or sell any asset. Markets move quickly; figures are correct as sourced at the time of writing. Always do your own research before making financial decisions.
